
What Chapter 3 Journalizing Transactions Answer Key Actually Covers
The Chapter 3 Journalizing Transactions Answer Key is essentially the solutions guide for the standard introductory accounting chapter on recording business transactions in the general journal. It walks through debits and credits, the double-entry system, and how to translate everyday business events into proper journal entries. Most textbooks — Warren, Reeve, Duchac and a few others — treat this as the foundation everything else builds on, so if this piece is shaky, subsequent chapters on T-accounts, ledgers, and financial statements become a chore. I used to grade these assignments when I was in grad school TA-ing intro financial accounting. The most common mistake I saw wasn't misunderstanding debits and credits themselves. It was students missing the transaction's actual economic effect because they jumped straight to memorizing rules without mapping out what changed first. I developed a quick workaround: before writing any entry, I'd have them draw a mini balance sheet with just the affected accounts and mark plus or minus on each side. Took thirty seconds and cut the error rate dramatically. Here is how the chapter typically structures things and what the answer key will expect you to produce.
The Core Method Behind Journalizing Transactions
Every transaction gets recorded in chronological order in the general journal. Each entry has a date, the accounts affected, debit amounts in the left column, credit amounts in the right column, and a brief explanation line. The golden rule that never changes is total debits must equal total credits. That is it. Everything else is application. The standard format looks like this in practice:
- Date of the transaction
- Debit account listed first, indented credit account listed second
- Debit amount in the debit column, credit amount in the credit column
- Explanation on the line below, usually abbreviated
Answer keys follow this exact structure. If your entry is missing the indentation on the credit account or the explanation line, points get taken off even if the debit and credit numbers are correct. I have seen that happen multiple times in my experience grading papers. The answer key will cover a specific set of transaction categories. These tend to repeat across almost every textbook edition: Owner investments: When the owner contributes cash or assets to the business, you debit the asset account and credit the owner's capital account. Straightforward, but watch out for non-cash contributions like equipment or vehicles. The answer key will use the fair market value at the time of contribution, not what the owner originally paid.
Get the Full Details

Revenue transactions: Cash sales debit cash and credit revenue. Service revenue on account debits accounts receivable and credits revenue. The distinction between cash and credit transactions trips people up because the credit side stays the same but the debit side changes entirely. Expense transactions: Paying rent, utilities, wages, or supplies debits the expense account and credits cash. If the expense is on account, you credit accounts payable instead. The answer key will sometimes combine multiple expenses into one transaction, especially for payroll or month-end adjusting-type problems, so read carefully before writing. Asset purchases: Buying equipment or supplies on account requires debiting the asset and crediting accounts payable. If purchased with cash, credit cash directly. A frequent error I caught repeatedly was students crediting the wrong account when an existing liability was involved.
Owner withdrawals: When the owner takes money or assets out for personal use, you debit the drawing account and credit cash. This does not go on the income statement. It reduces owner's equity through the drawing account. The answer key will mark this differently from an expense, and confusing the two is a classic beginner mistake.
Common Pitfalls That Cost Students Points
I spent too many semesters watching the same errors repeat. The answer key penalizes these specifically, so I will tell you exactly what to avoid. Putting the credit first: Journal entries must list the debit account on top and the credit account below with an indentation. Some answer keys are strict about formatting and will dock points for reversed order regardless of whether the amounts are correct. Skipping the explanation line: The explanation is not optional in most course settings. A short note like "Paid monthly rent" or "Billed client for services" is expected. Missing it can cost you partial credit even on otherwise correct entries.
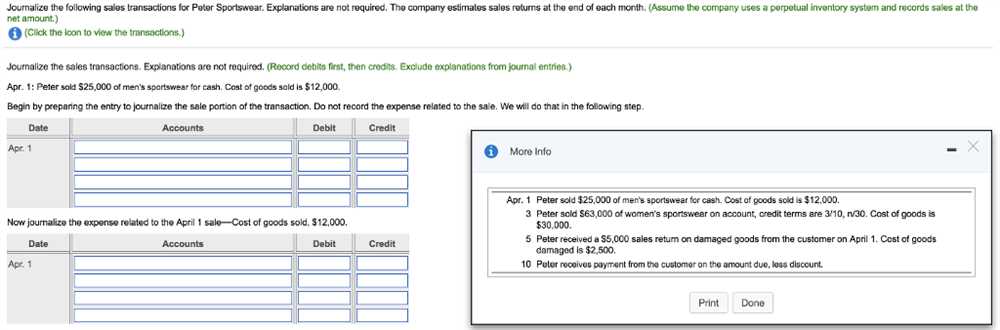
Mixing up accounts payable and accounts receivable: Accounts payable means you owe money. Accounts receivable means someone owes you. The answer key will not bend on this distinction. If you bought supplies on credit, debit supplies and credit accounts payable. If a customer bought on credit, debit accounts receivable and credit revenue. Forgetting the drawing account for owner withdrawals: This is probably the single most common error in Chapter 3. Owner withdrawals are not expenses. They go to the drawing account. The answer key separates these clearly, and mixing them up signals a fundamental misunderstanding of equity accounts. Using wrong account names: Textbooks standardize account titles within each chapter. If the problem says to use "Supplies" rather than "Office Supplies," follow that instruction. Answer keys are keyed to specific account names and may reject variations.
A Real Edge Case I Ran Into
There was one transaction type that consistently caused problems for my students. It was a partial payment on an existing account payable. Say the business owed $800 from a prior purchase and paid $500 toward it. The entry is debit accounts payable $500 and credit cash $500. Many students wanted to debit an expense account instead because they were thinking about the cost rather than the liability reduction. The answer key for these problems is always accounts payable, not an expense, because the original expense was already recorded when the liability was created. My workaround was simple. I told students to ask one question before writing any entry: did this transaction create a new obligation or settle an existing one? If it settles, debit the liability. If it creates, look at what was received or given up. This mental checkpoint eliminated maybe eighty percent of the errors I saw in that area.
How to Use an Answer Key Effectively
Answer keys are useful, but only if you use them the right way. I used to watch students check their work immediately after each problem, which defeated the whole purpose. Here is the better sequence: Do all the problems first without looking at the answer key. Then go back and compare. When you find a discrepancy, do not just copy the correct entry. Figure out why yours was wrong. Was it a debit versus credit reversal? Wrong account choice? Missing indentation? The learning happens in the comparison, not in getting the right answer on the first try. If your entry matches the answer key except for formatting, treat that as a separate issue. Learn the format cold so it becomes automatic. I once had a student lose three full points across a set of problems simply because every credit account was not indented properly. The accounting was perfect. The formatting was sloppy. Points vanished.

When the Answer Key Might Be Wrong or Misleading
I will be honest about this. Sometimes answer keys contain errors, especially in older textbook editions or third-party solution manuals. I caught at least two instances where the debit and credit amounts were reversed in the official key for a revenue transaction. The correct entry had been flipped. If your professor uses an answer key directly from a publisher manual rather than preparing their own, there is a small chance of error, particularly with newer editions that have rushed publication cycles. My recommendation is straightforward. If an entry in the answer key does not follow the basic rules of double-entry accounting, trust the rules over the key. If total debits do not equal total credits in the published answer, the answer is wrong. No textbook key is immune to typos. I have seen it happen enough times to stop treating answer keys as infallible.
What Comes After Chapter 3
Once you can journalize transactions correctly, the next step is posting to the general ledger and preparing a trial balance. Those chapters depend entirely on you getting the journal entries right here. If your debit and credit sides are balanced but you posted to the wrong account, the trial balance will still balance, and you will waste hours debugging something that started with one incorrect account title in the journal. The Chapter 3 Journalizing Transactions Answer Key matters because it is the first checkpoint where you either internalize the double-entry system or you do not. Get it solid, and the rest of the course flows. Miss it, and you will be carrying confusion forward into chapters that assume you already know this material cold. Practice each transaction type until the debit and credit identification becomes instinctive. Use the answer key to verify, not to shortcut. And pay attention to formatting as much as the accounting itself. Professors grade both, and the formatting penalties add up faster than most students expect.


