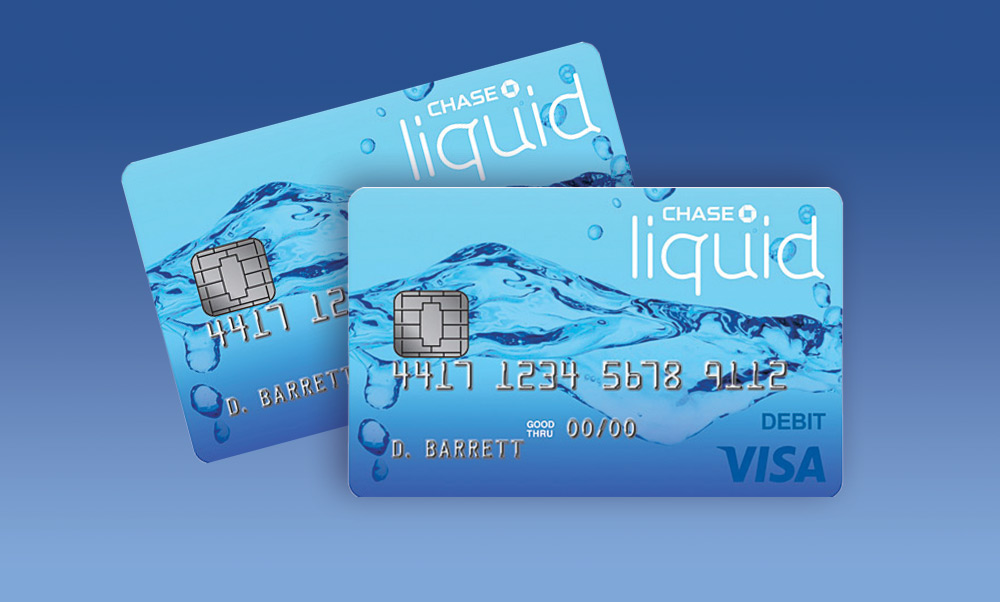
How the Chase Prepaid Card actually works in practice
I loaded up on prepaid cards back in 2019 when my main checking account got frozen during a wire transfer dispute. The bank said 5-7 business days. I had rent due in 48 hours. A colleague handed me a reloadable prepaid card and said just use it. That card is basically what the Chase Prepaid Card is — a Visa or Mastercard branded card linked to a stored value balance, not your actual bank account. You load money onto it, you spend up to that amount, and when it runs out you either discard it or add more funds. The thing nobody tells you upfront is that most prepaid cards, including the Chase variant, don't report to the three major credit bureaus. So using one responsibly won't build your credit score. If you're trying to establish or rebuild credit, this is the wrong tool. But for expense tracking, budget control, or a backup payment method while your primary account is under review, it does exactly what it claims.
Setting up your Chase Prepaid Card
First, you need to register online at chase.com/prepaid or download the Chase Mobile app. During registration you'll provide your name, address, SSN last four digits, and date of birth. This is an FBI Act requirement — prepaid cards above certain thresholds need KYC verification. The process usually takes 10-15 minutes if your information matches your ID documents exactly. Mismatched addresses or recent name changes can trigger manual review that adds 2-3 business days. Once registered, you can load funds through several methods. Direct deposit from your employer is the cleanest option — set it up once and the money lands automatically on payday. Bank transfer from your primary account takes 1-3 business days. Cash reload is available at over 130,000 participating retailers like Walmart, CVS, and 7-Eleven, but you'll pay a reload fee that typically ranges from $3.95 to $5.95 per transaction. Electronic transfers between your own accounts are usually free. The card arrives in 7-10 business days by mail. Some users report receiving it in 5 days if you live near a fulfillment center. Activate it through the app or by calling the number on the back. Then set your PIN immediately — you'll need it for debit transactions at gas stations and grocery stores where card-not-present signature-based processing gets declined more often than you'd expect.
What the Chase Prepaid Card can and cannot do
It works anywhere Visa or Mastercard is accepted. Online purchases, subscriptions, ATM withdrawals, contactless payments — all functional. The balance deducts in real time. If you have $200 on the card and buy something for $45, your available balance drops to $150 instantly. No hovering near credit limits, no surprise overage fees from merchants placing temporary authorizations that hold funds for 3-5 business days before releasing. But there are specific scenarios where this card completely fails. Hotel holds are the biggest offender. Most hotels place a hold of $50-200 per night plus incidentals on the card you present at check-in. If your prepaid balance doesn't cover the total hold amount, the reservation gets declined even if you can pay the actual bill afterward. I learned this the hard way at a Chicago airport hotel in March 2022. My balance was $380, the hold was $500 for a two-night stay. The front desk agent couldn't override it. I ended up paying out of pocket and reimbursing myself later, which defeated the whole budget control purpose. Another edge case I ran into: subscription services that do recurring billing. Netflix, Spotify, Amazon Prime — these charge the card monthly. If your balance is low when the charge hits, the transaction declines and your account gets suspended. Unlike a checking account where you might have overdraft protection, prepaid cards have zero fallback. I missed a PayPal auto-charge last September because I'd forgotten the balance had dropped to $12.87. PayPal locked my account for 30 days while they verified my identity again. The workaround was calling their support line and making a manual payment, which took 45 minutes on hold.
Get the Full Details
Common pitfalls and how to avoid them
Inactivity fees are the silent killer on prepaid cards. Chase typically charges a monthly maintenance fee of $5.95 after 12 consecutive months of no transactions. Some cards waive this if you set up direct deposit. Check your cardholder agreement carefully — the fee structure varies by product type. The regular reloadable prepaid card has different terms than the gift card version, and mixing them up leads to unexpected charges. ATM withdrawals carry double costs. First, your own card may charge a usage fee of $2.50 per withdrawal. Second, the ATM operator charges their own fee, usually $2.50 to $4.00. That's $5.00 to $6.50 lost every time you pull cash. If you withdraw $100, you're effectively paying a 5-6.5% transaction fee. For small daily expenses, this makes prepaid cards expensive compared to using your primary debit card. Reserve ATM use for emergencies or when you specifically need physical cash. Balances don't earn interest. Unlike a savings account or even a high-yield checking account, prepaid card balances sit at 0% APY. If you regularly carry $500 or more on the card waiting to spend it, you're losing potential earnings. In a 4.5% high-yield account, that's $22.50 per year. Not life-changing, but unnecessary if your spending pattern involves holding funds temporarily before use.
International transactions often get blocked. Many prepaid cards have geo-blocking enabled by default for fraud prevention. If you travel abroad and try to use the card in Canada or Mexico, transactions may decline even with sufficient balance. Call Chase customer service before traveling to request international use be enabled. This usually takes 10 minutes and prevents the panic of being stranded at a foreign gas station with a declined card.
When to use it and when to walk away
The Chase Prepaid Card makes sense if you need expense segregation — keeping work reimbursements separate from personal funds, or giving teenagers a controlled payment method without linking their spending to your primary account. It also works as a temporary bridge during bank account freezes, disputed transactions, or when you want to cap your monthly spending at a fixed loaded amount. The psychological effect of seeing a declining balance rather than a credit limit is real and measurable for people who struggle with overspending. Walk away if you're trying to build credit history, need interest earnings on stored value, make frequent international purchases, or rely on hotel and car rental reservations that require large holds. In those cases, a secured credit card or a standard debit card with overdraft protection serves you better. The secured card reports to all three bureaus and builds credit over 6-12 months of responsible use. The debit card with overdraft protection gives you a safety net without the inactivity fees that eat into prepaid card balances. I still keep a Chase Prepaid Card in my wallet as a backup, loaded with $100 and reloaded only when I remember. It's never failed me when I needed it, but I've also forgotten about the inactivity fee twice and paid $5.95 for doing nothing. The card works. It just requires the same attention to detail that any financial tool demands, and most people skip that step until they see an unexpected charge on their statement.