Tracking Your Chase Sapphire Preferred Sign-Up Bonus
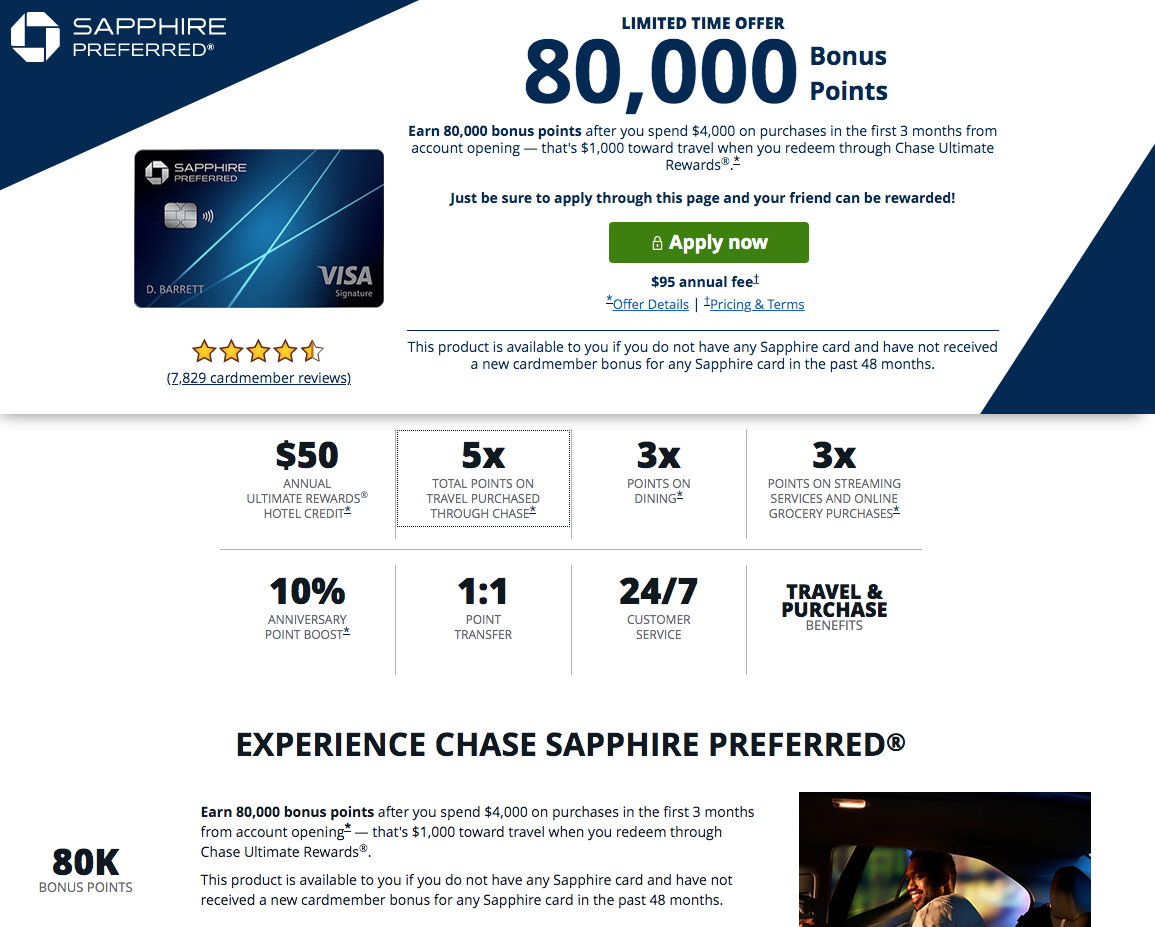
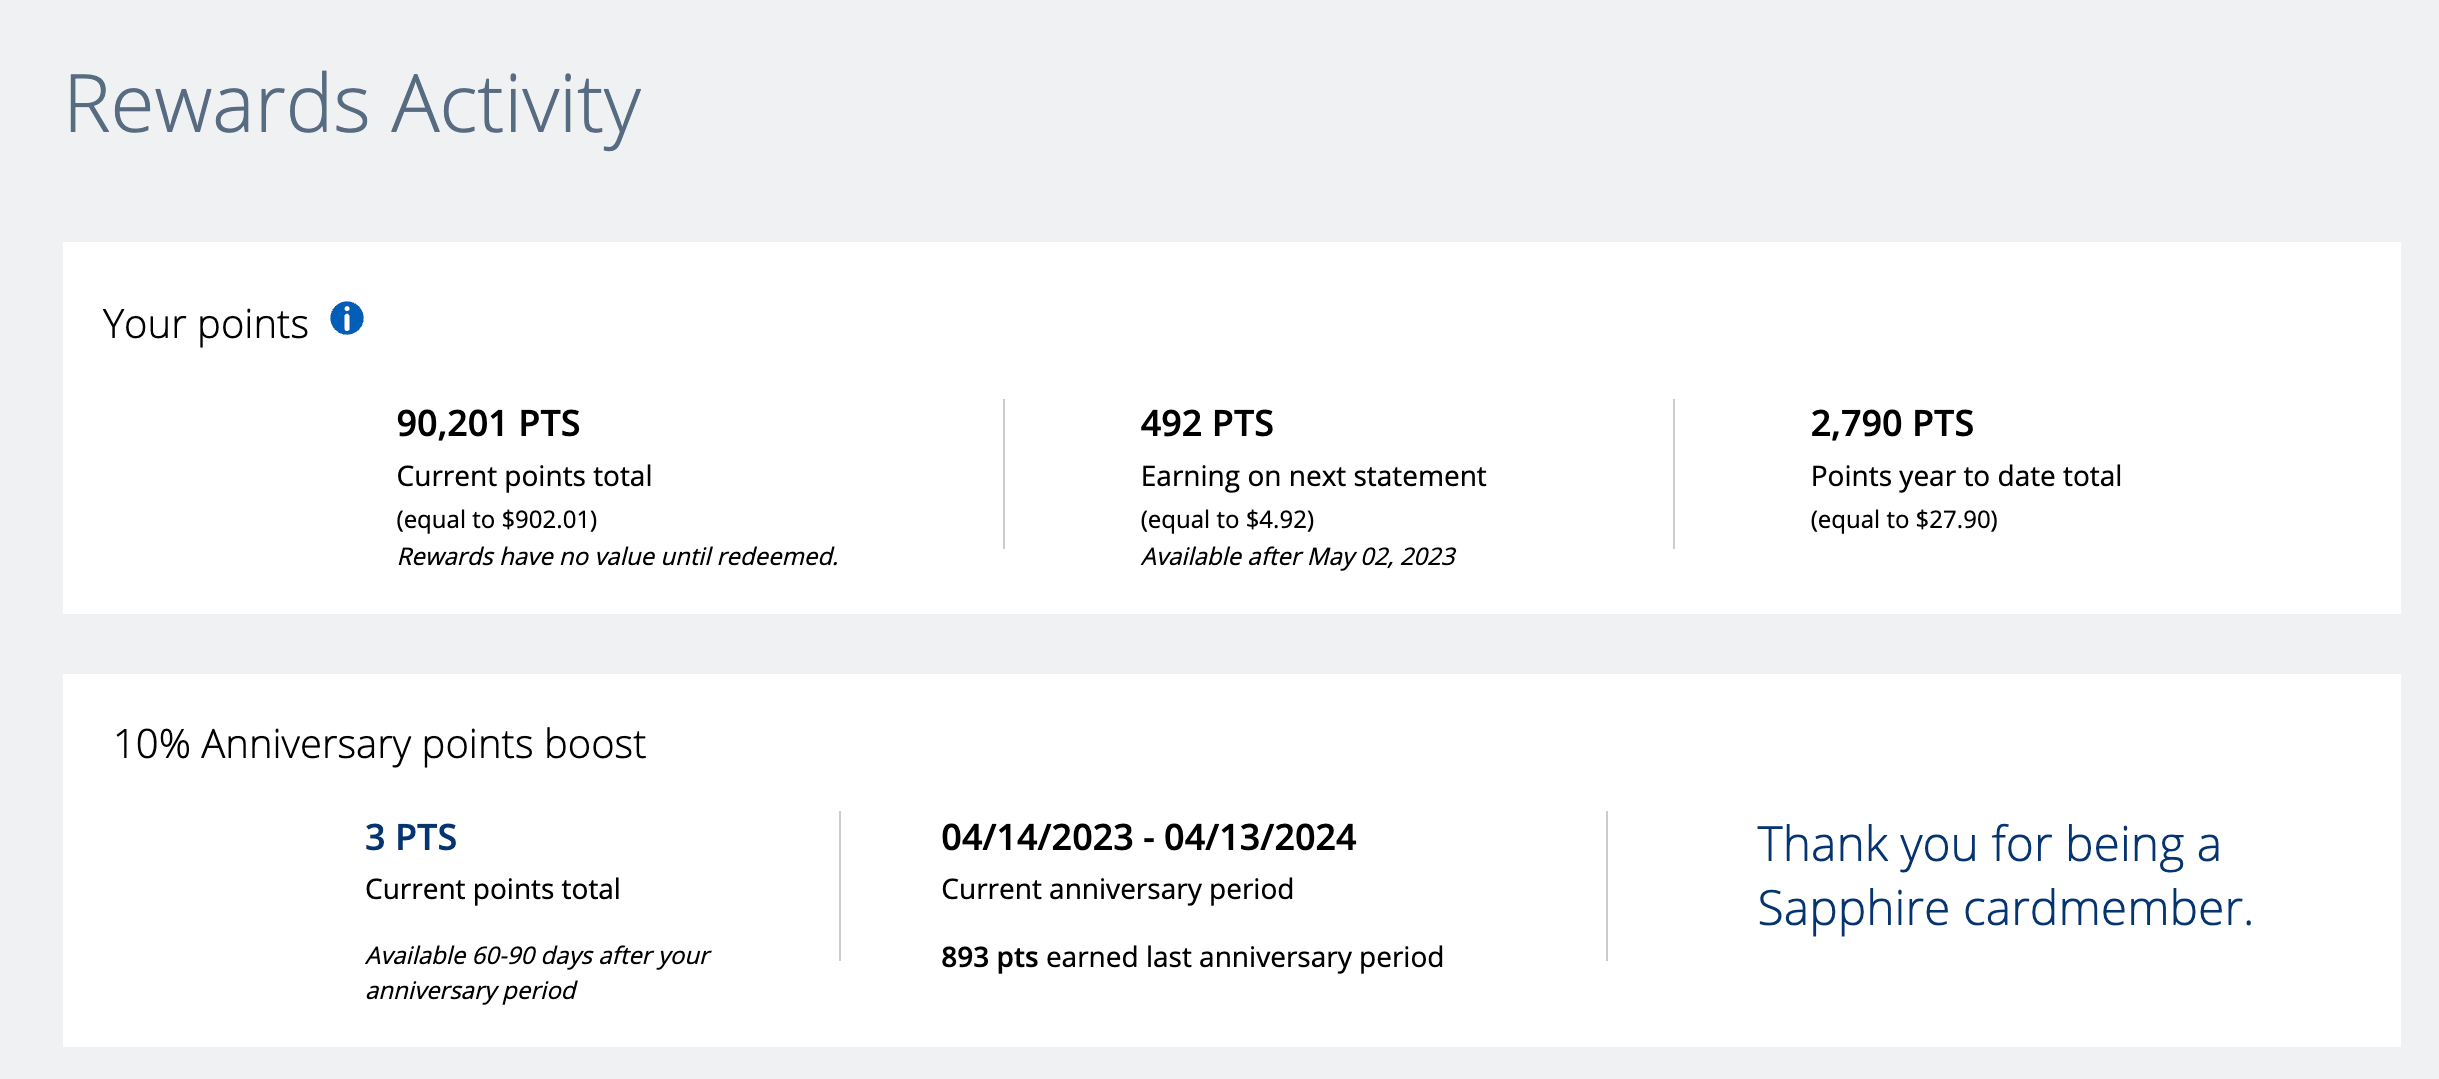
Chase Sapphire Preferred Bonus History matters because the welcome offer changes frequently, and understanding what you actually received versus what was advertised is the only way to properly evaluate whether this card is worth keeping around. The current offer sits at 60,000 bonus points after spending $4,000 in the first three months. That has been in place since sometime in 2023, but it wasn't always that number. It was lower for a long time. Knowing what change landed when helps you gauge whether a new application is going to be good or mediocre.
How to Find Your Chase Sapphire Preferred Bonus History
There are a few ways to pull this information without spending twenty minutes on hold with customer service. The most direct method is using third-party trackers like Milesworth, CreditCardDaddy, or the wiki pages on Reddit. These sites maintain running logs of every Chase sign-up bonus change, usually within a day of the change hitting live. Chase rarely announces anything publicly. The offers shift silently through their portal systems, and trackers catch it by checking the application flow multiple times per day. If you want your personal history, you can pull that from your account statements or by calling the number on the back of your card. They will confirm the exact points deposited and the exact spend requirement attached to your application date. Writing down that date along with the offer number is the practical move here.
The problem with relying solely on official Chase records is timing. If you applied in early 2022 and want to know what the offer looked like today for comparison, Chase has no automated tool that shows historical offer values. You get your application details. That's it. I learned this the hard way. I was trying to verify what offer I originally locked in when I applied back in February 2022. The customer service rep confirmed my points total but couldn't tell me what the required spend was at the time of application versus what it is now. I ended up digging through archived screenshots I'd taken when I first saw the application page, along with checking the Milesworth Chase thread from that month. It took about forty-five minutes to cross-reference everything. The key takeaway is to screenshot your application page before you submit. Chase changes offers constantly, and the page you're looking at right now might not be the one you qualified for six months later.
Get the Full Details
What the Numbers Actually Mean
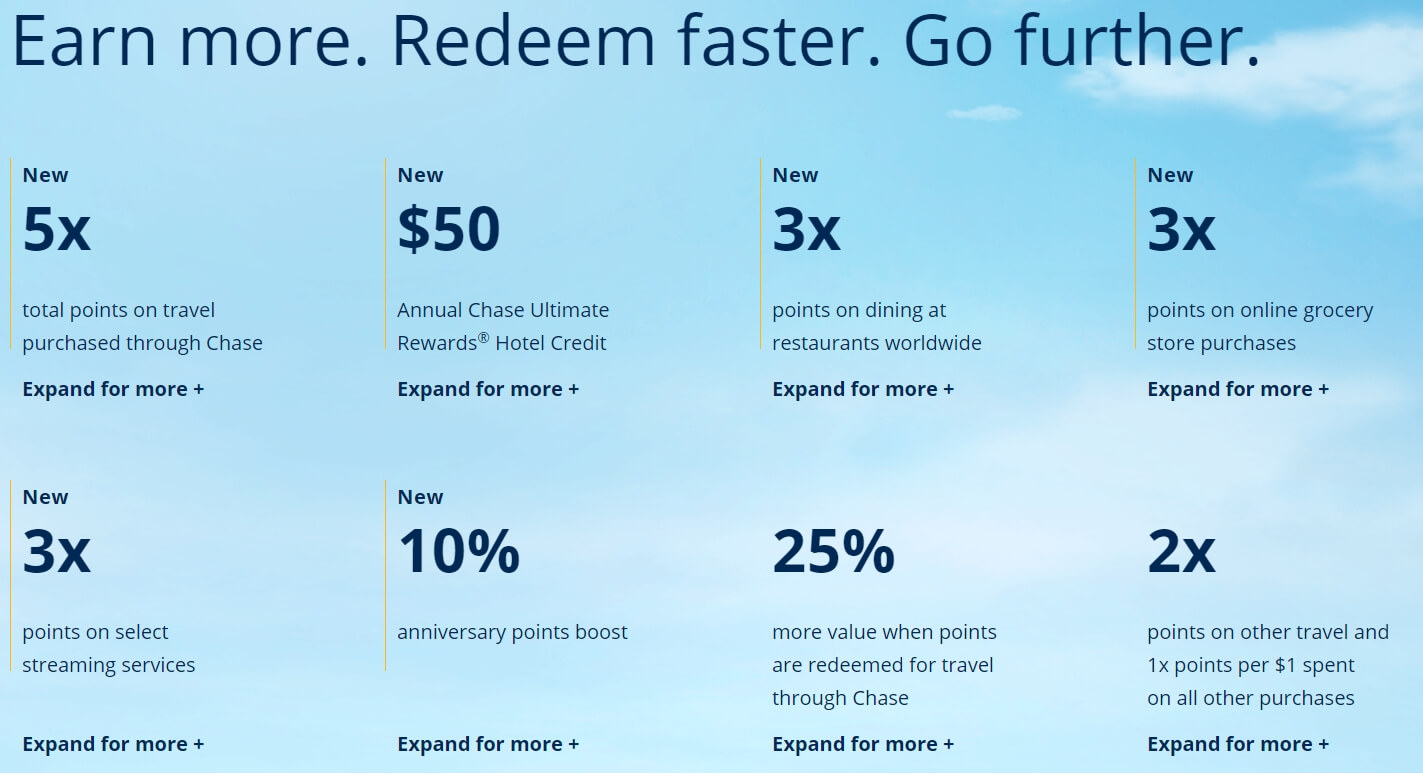
Chase Sapphire Preferred points are worth 1.25 cents each when you book travel through Chase Ultimate Rewards. That makes the current 60,000 point bonus roughly equivalent to $750 in travel spending. If you redeem for cash back or gift cards, you're looking at $600 flat. Most people who use these points properly land somewhere between 1.25 and 1.5 cents per point depending on how they transfer to partners. The spend requirement is where people mess this up. $4,000 in three months sounds aggressive until you remember that the card earns 2x on dining and travel. If you already spend that money on those categories, the bonus becomes almost too easy. I've seen people hit the threshold in six weeks just on normal grocery and gas spending when they were also booking a hotel and paying for flights. Counter-intuitively, the 3x categories on the Preferred are not where the biggest value comes from. The real advantage is the transfer partners. Points transferred to United, Southwest, Hyatt, or IHG can easily push the per-point value above 1.5 cents, sometimes higher. Hyatt transfers alone have landed me at over 2 cents per point on award nights. That part doesn't matter as much if you're just burning points for statement credits.
Common Pitfalls with the Sapphire Preferred Bonus
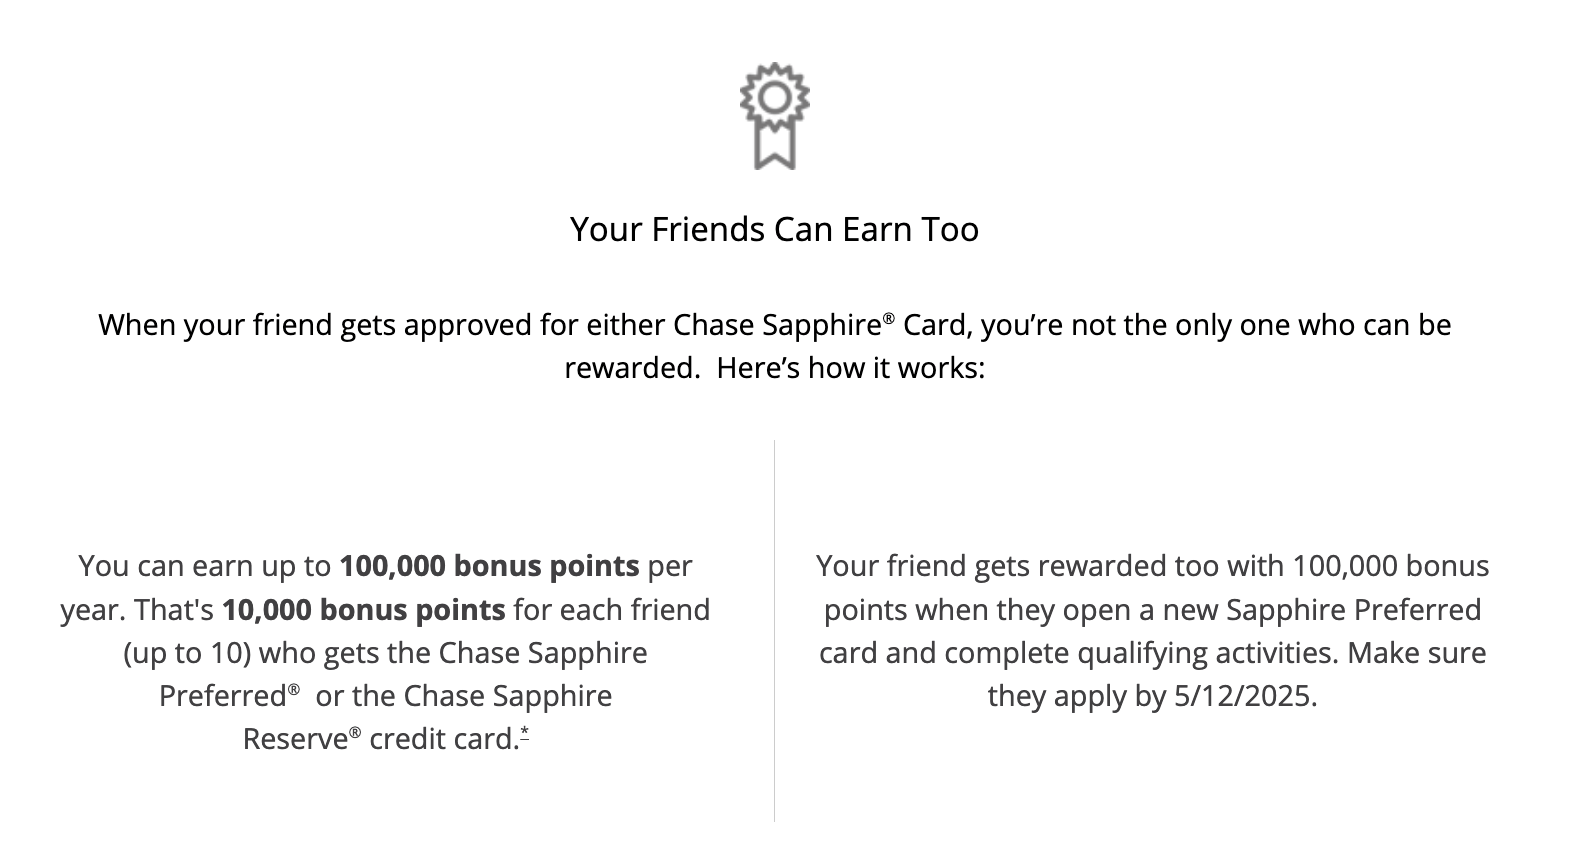
Chase has what they call the 5/24 rule. If you have opened five or more credit cards across any issuer in the past twenty-four months, Chase will automatically deny your Sapphire Preferred application regardless of your credit score or income. This rule applies to the entire Chase family, including business cards. I ran into this directly when I had a Wells Fargo card, a Costco card, a PayPal credit line, a Discover, and a Capital One Venture. When I tried to apply for the Sapphire Preferred four months later, the automated system rejected me instantly. Not a soft decline. A full denial with no appeal option. I had to wait until my oldest card aged out of the twenty-four-month window, which took roughly eight more months. Another trap is applying for the Sapphire Reserve instead of the Preferred when you don't need the annual fee benefits. The Reserve currently offers 60,000 points as well but costs $550 annually. The Preferred is $95. For most people, the Preferred is the better entry point into Chase points. The Reserve only makes sense if you are regularly using the $300 travel credit, the Priority Pass lounge access, and the 10% point boost on hotels booked through Chase. Those benefits sound great on paper. In practice, I found the Priority Pass visits dropped to maybe three times a year after the novelty wore off, and I rarely booked hotels through the Chase portal. The extra annual fee wasn't justified by actual usage. There is also the issue of bonus stacking. Chase occasionally runs promotions where you can earn additional points on top of the sign-up bonus, usually through referral links or limited-time offers posted on their blog. These are not guaranteed. They appear and disappear without notice. I once caught a promotion that offered an extra 10,000 points for a limited window. It lasted about seventy-two hours before vanishing. Tracking these requires actively watching the Chase offers page or joining alert threads on Reddit, not just relying on the main card website.
Limitations and When the Preferred Doesn't Make Sense
Let me be straightforward about where this card falls short. If you do not travel at least twice a year or spend significantly on dining, the Preferred earns less than many no-annual-fee cards in your everyday categories. The 1x base rate on everything else is competitive, not outstanding. Cards like the Citi Double Cash or the,Uneasy Cash Back cards from major issuers pay 2% on everything with no annual fee and no points ecosystem to manage. If you find points systems confusing or boring, the Preferred is actively worse than those cards for your wallet. The annual fee increase is another ongoing issue. Chase raised it from $95 to $95 a while back, but there was a period where it jumped to $150 and then settled. Fee changes happen without warning. If you join primarily for the sign-up bonus and then ignore the card for two years, the annual fee will eat into your initial gains before the next bonus refreshes. The best alternative depending on your situation is either the Chase Freedom Flex for the rotating 5% categories and zero annual fee, or the Chase Sapphire Reserve if you are already maxing out travel credits and lounge access. Neither is a perfect swap. The Flex requires manual activation each quarter. The Reserve requires spending enough to justify the higher fee. The Preferred sits in the middle and works best for people who want a simple points card with a reasonable fee and a genuine sign-up bonus.
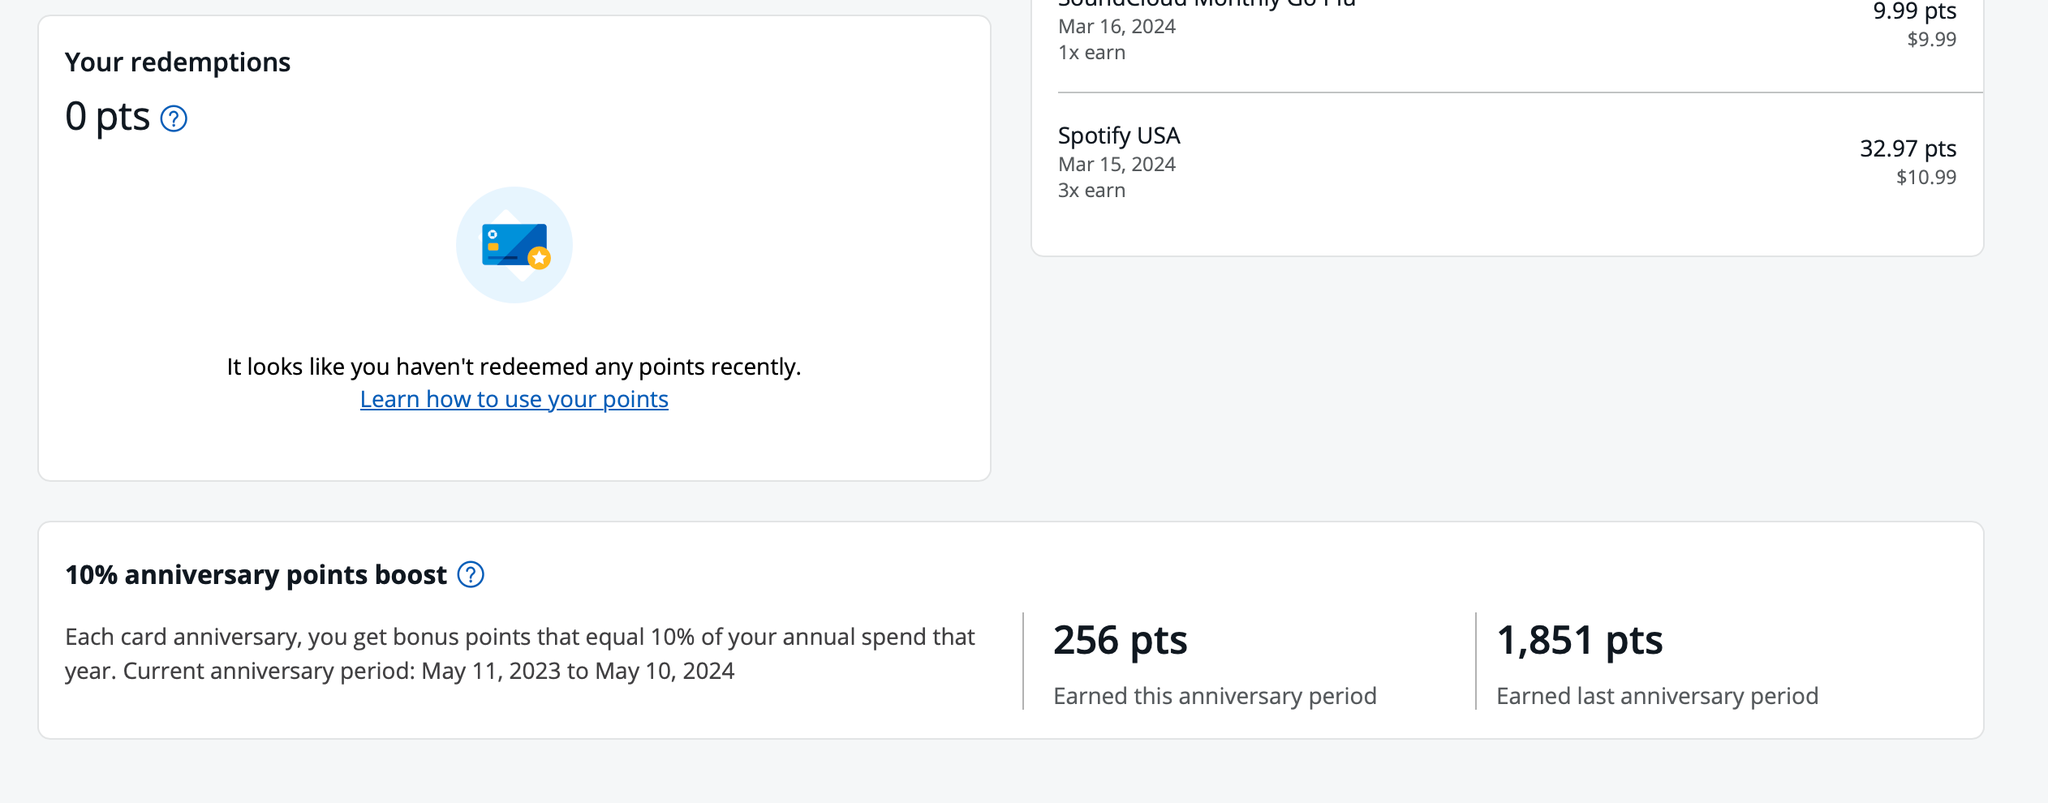
If you do apply, the process itself takes about eight minutes online. Approval is typically instant. The points post within two to five business days after you hit the spend threshold, though Chase sometimes takes up to seven. You'll receive a digital card immediately and a physical card in the mail within five to ten business days. There is no paper application anymore unless you go into a branch, which most people don't bother with. The Chase Sapphire Preferred remains one of the more reliable entry-level travel cards on the market. The bonus history tracks cleanly, the redemption options are solid, and the annual fee is manageable. It is not the highest-earning card in every category, and the point system adds a layer of complexity that some people actively dislike. But for anyone who plans to use points for travel rather than cash back, it is still worth having in the rotation.