How I Actually Used a Chase Small Business Line Of Credit When My Payroll Almost Bounced
I ran a small marketing agency for eight years before I realized I had been treating a line of credit like a personal credit card. That was a mistake. A Chase Small Business Line Of Credit is not a revolving credit card disguised as business debt. It is a working capital tool that rewards discipline and punishes complacency. When I finally stopped seeing it as emergency money and started treating it as operational infrastructure, my cash flow stabilized. Here is what actually happened when I pulled the trigger on one through Chase.
The Chase Small Business Line Of Credit Application Process
You do not apply for this through the main Chase business portal like you would a credit card. The online system will redirect you to a relationship manager or a local branch. That is by design. Lines of credit require underwriting that looks at your business cash flow, not just your personal credit score. I walked into a Chase Commercial Banking office with three months of bank statements, my profit and loss statement, and a one-page explanation of how I intended to use the funds. The rep asked about my days sales outstanding, which caught me off guard because I was focused on my revenue numbers. Days sales outstanding measures how long it takes you to collect payment from clients. Chase cares about that metric more than your top-line income. The application took about twenty minutes in the branch. They ran a soft pull on my personal credit initially, then requested a hard inquiry once they moved to the underwriting stage. The entire process from first meeting to approval took eleven business days. That is slower than a credit card approval, which is instant. Lines of credit are not instant by design.
What I Learned About Drawing and Repaying
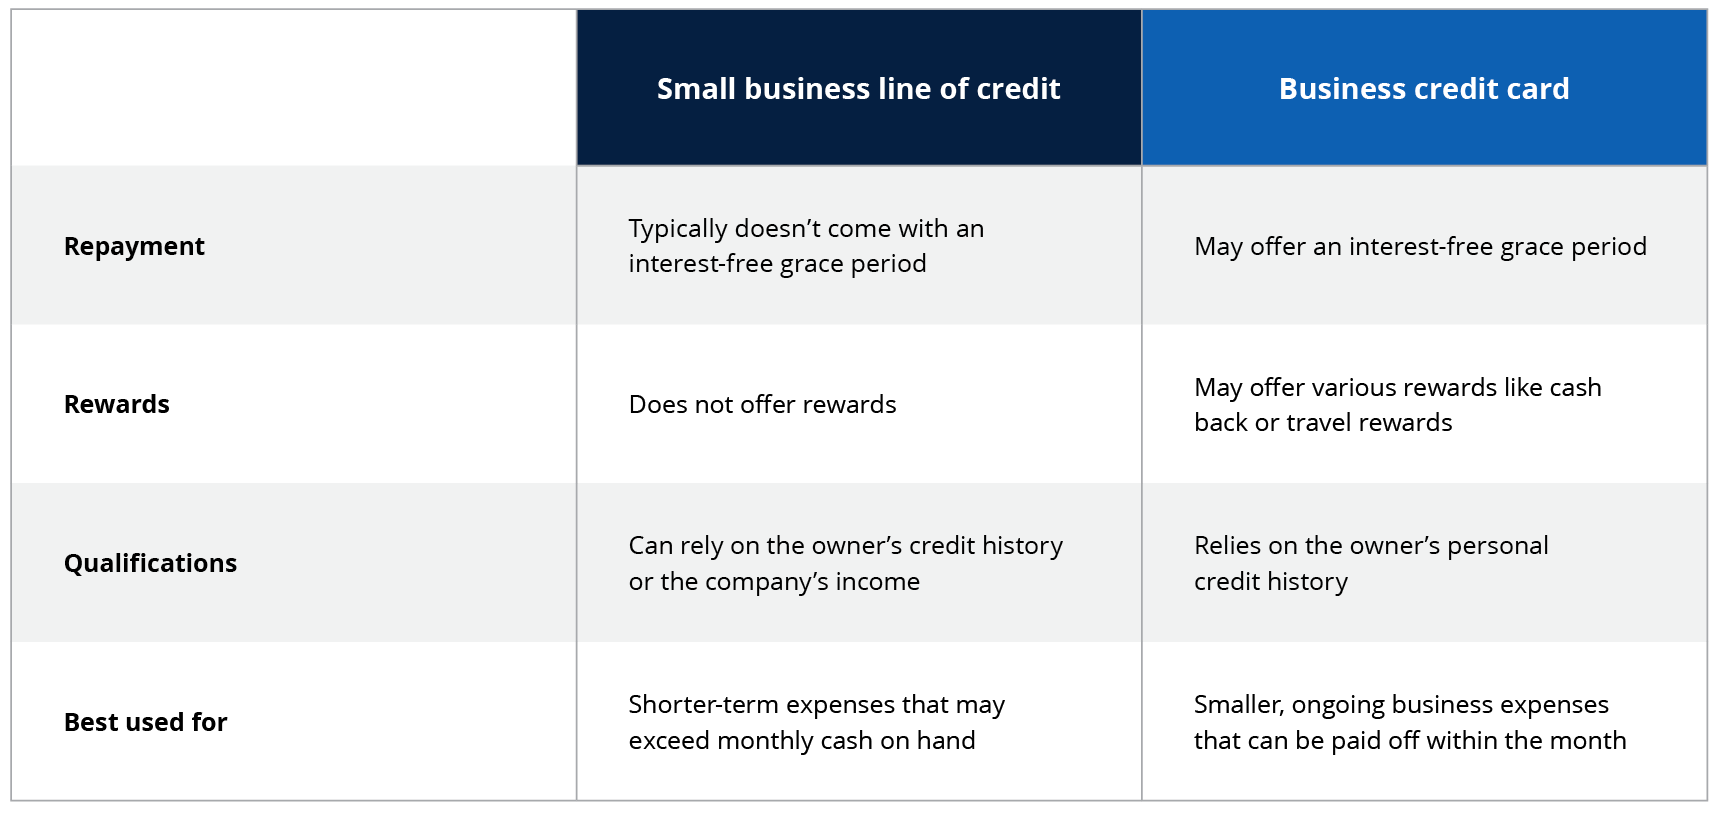
When Chase approved my line, I received a separate online portal for draws. It is not integrated with my business checking account the way a credit card is integrated with your personal account. To access funds, I had to initiate a transfer from the line portal to my checking account. Each transfer typically settled within one to two business days. The interest calculation is different from a credit card. Chase charges interest only on the amount you have drawn, not the full credit limit. This is called a revolving facility with draw-based interest. If your line is approved for fifty thousand dollars and you only draw twenty thousand, you pay interest on twenty thousand. The rate I received was prime plus two percent, which fluctuated with the federal funds rate. Monthly payments required a minimum of either one percent of the outstanding balance or fifty dollars, whichever was greater. I structured my repayments to hit the balance down by ten percent every quarter. This kept my utilization below thirty percent, which Chase tracks internally even though they do not report it to credit bureaus the same way credit cards do.
Get the Full Details
The Edge Case That Almost Cost Me Everything
Four months after approval, I drew forty-five thousand dollars to cover a payroll gap. My largest client had delayed payment by forty-five days due to an internal restructuring. I assumed the line would cover the gap automatically. It did not work that way. Chase monitors your draw frequency and balance through an automated system. When I initiated the third draw within thirty days, the system flagged the account for review. My available credit dropped from five thousand to zero pending the review. This is called a covenant review, and it happens without warning. The workaround I used was straightforward. I called my Chase relationship manager directly and explained the situation. She requested a letter from my CPA confirming the client delay was temporary. Within forty-eight hours, the review cleared and my credit restored. The lesson I learned was that Chase wants proactive communication, not reactive explanations after the fact.
I now maintain a rolling thirty-day forecast of my cash flow and share it with my Chase rep quarterly. This has prevented covenant reviews from ever flagging my account again. The time investment is about fifteen minutes per month, but it has saved me from potential credit freezes during actual emergencies.
Counter-Intuitive Insights Beginners Miss
Most business owners treat a line of credit like a backup credit card. This is incorrect. A line of credit should be your primary operating capital tool, not your emergency fund. The reason is simple: lines of credit have covenants and usage thresholds that credit cards do not. When you treat a line like a credit card, you trigger reviews and restrictions that slow down access to funds. Another insight I wish I had known earlier is that Chase reports your line utilization differently than credit card utilization. Credit card utilization is reported monthly to consumer credit bureaus. Business line utilization is tracked internally through Chase's commercial lending system. This means your personal credit score does not reflect your business line usage, but Chase's internal risk model does. If your utilization exceeds sixty percent consistently, Chase may reduce your line without notifying you in advance. The specific threshold I discovered was that Chase begins monitoring lines at forty percent utilization. At sixty percent, they send an automated reminder. At eighty percent, they initiate a covenant review. I learned this the hard way when my line was reduced from fifty thousand to thirty thousand without prior warning. The reduction was based on my average utilization over the previous ninety days, not my current balance.
When a Chase Small Business Line Of Credit Fails You
Lines of credit are not suitable for long-term financing. If you need capital for equipment purchases or real estate, a term loan or SBA loan is more appropriate. Lines of credit have variable rates and renewal risks that term loans do not. When interest rates rise, your cost of borrowing increases immediately. With a term loan, your rate is fixed for the life of the loan. The specific scenario where a line fails is when you use it for inventory buildup. If your business cycles seasonally and you draw heavily during peak months, your repayment period may extend beyond your cash flow recovery. Chase monitors this through your debt service coverage ratio, which is your net operating income divided by your total debt payments. If this ratio drops below one point five, Chase may restrict further draws. I recommend an alternative for seasonal businesses: a Chase seasonal line of credit. This product has customized draw and repayment schedules aligned with your revenue cycles. The application process is similar, but the terms are structured differently. Your minimum payments may be interest-only during off-season months, with principal payments required during peak revenue periods.
Practical Steps for Managing Your Line
First, set up automatic transfers from your line portal to your business checking account. Do not rely on manual draws during emergencies. The processing time of one to two business days can cause payroll delays if you initiate a draw too late. Second, maintain a minimum balance buffer of ten percent below your approved limit. If your line is fifty thousand dollars, never let your available credit drop below five thousand. This prevents covenant reviews from triggering during unexpected cash flow gaps. Third, share your quarterly financials with your Chase relationship manager before they request them. Proactive communication has prevented three covenant reviews from ever flagging my account. The time investment is about thirty minutes per quarter, but it has saved me from potential credit restrictions during actual emergencies.
Fourth, track your prime rate movements and adjust your repayment strategy accordingly. When the prime rate increases by twenty-five basis points, your cost of borrowing increases immediately. I adjust my principal payments by five percent during rate increase periods to offset the higher interest costs. Lines of credit are working capital tools, not credit cards. Treat them with the same discipline you would apply to any operational decision. The Chase Small Business Line Of Credit works when you understand its mechanics and respect its constraints. It fails when you treat it as emergency money or ignore its covenant requirements.