Why Check Template Matters in Daily Operations
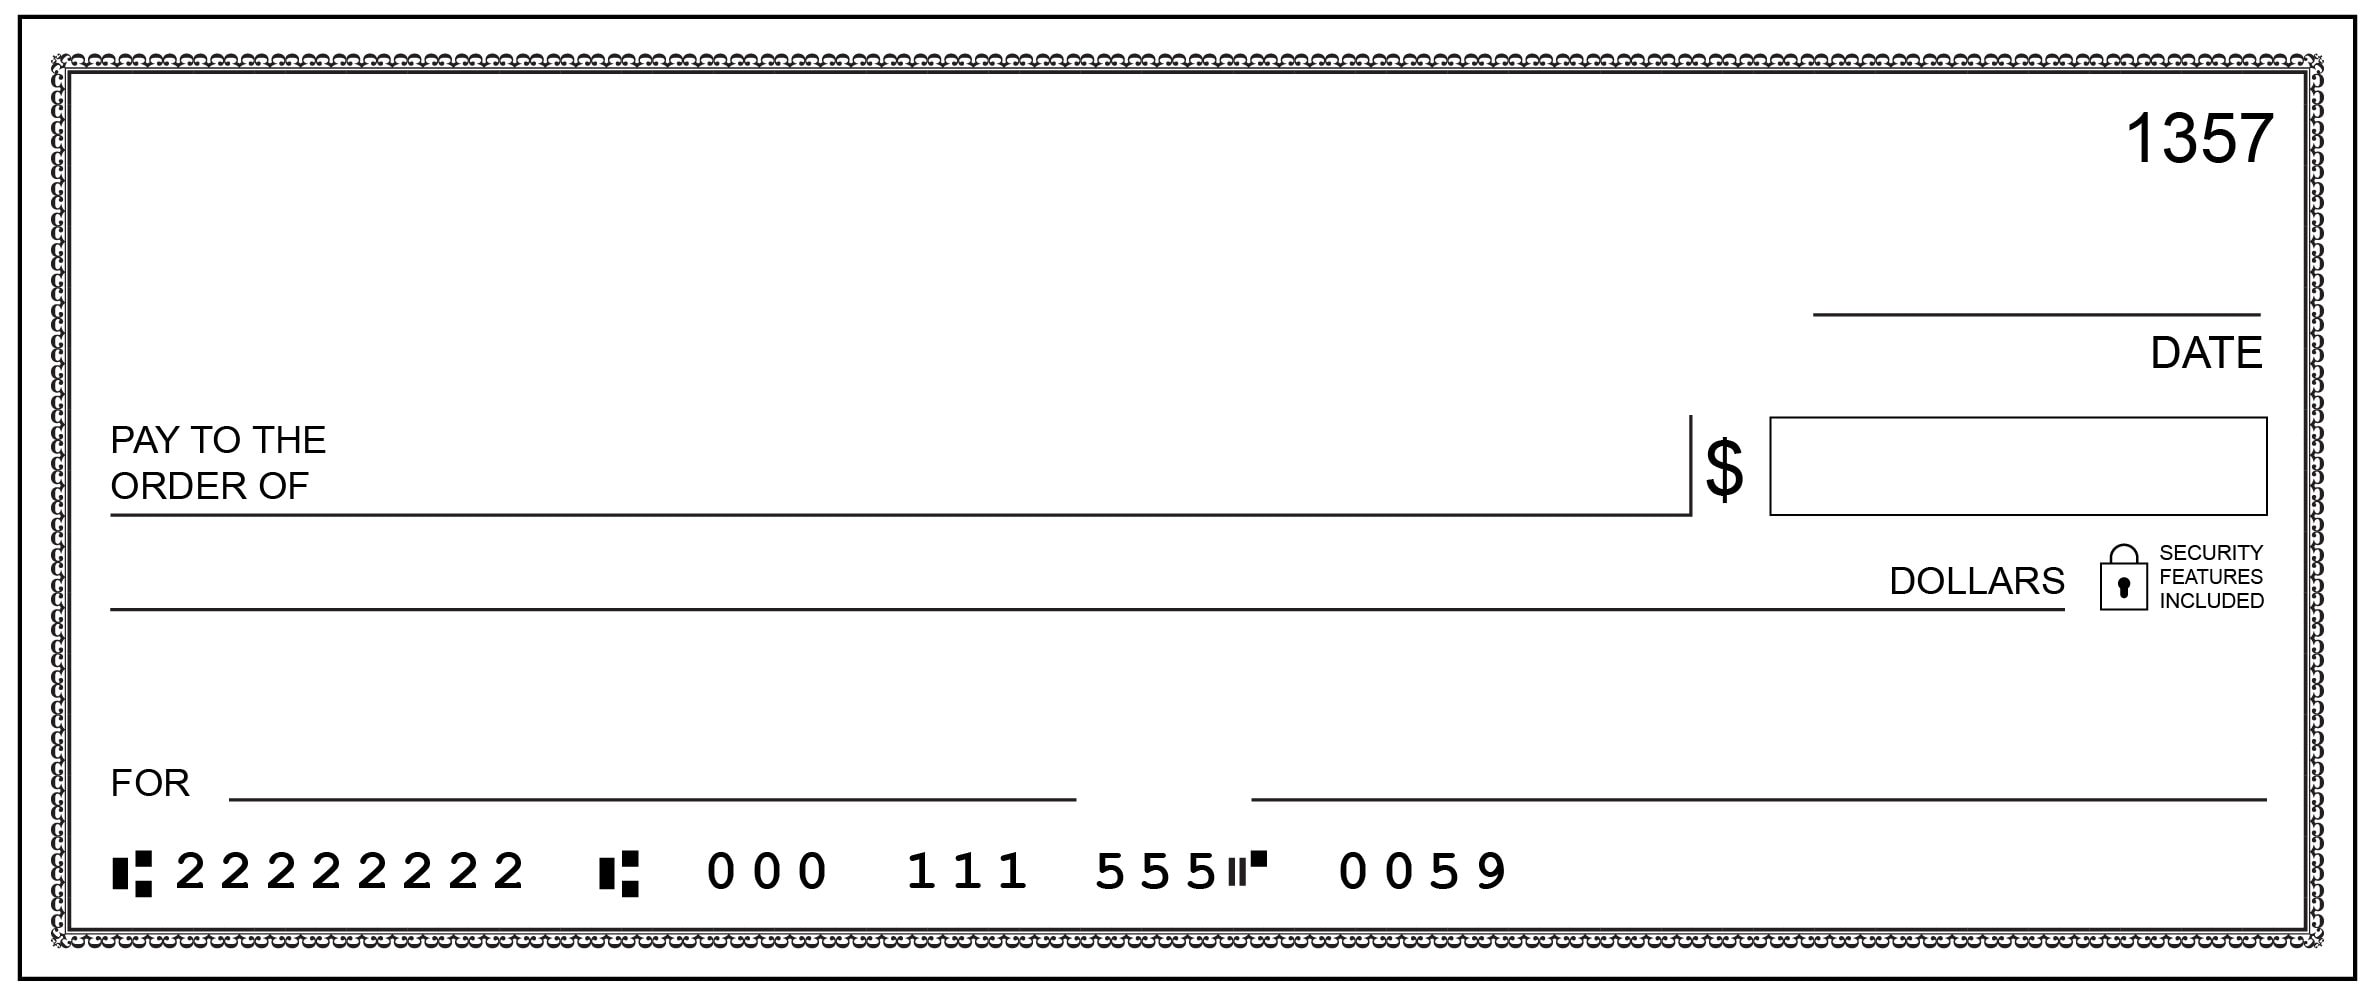
Most people treat a check template like it's just a piece of paper you fill out. That's wrong. A check template is the structural backbone of any payment workflow, and getting it right saves hours of rework down the line. I've seen teams spend half a day manually adjusting layouts because they didn't account for font embedding issues in their PDF output. The result was checks that looked correct on screen but printed with misaligned fields. A check template is a predefined layout structure that defines where all elements of a check appear - payee line, amount box, date field, memo section, signature line, and the MICR line at the bottom. It's usually built inside a word processor, design tool, or dedicated banking software, then reused across dozens or hundreds of transactions. The key is consistency. When the template is locked down properly, every check comes out looking identical and bank-compliant. I learned this the hard way about three years ago. My team was generating checks through a semi-automated script that pulled from a shared Excel file. We thought we were being efficient. Instead, we were creating a disaster. One particular check had a vendor name that was 47 characters long. The template didn't account for overflow. It clipped the last four characters silently. The vendor thought they were being stiffed, called our accounts payable line twice, and I had to personally trace which check it was from a batch of eighty that month. After that, I started building a character limit check directly into the template validation before anything got submitted.
Building a Functional Check Template
Start with the physical dimensions. Standard business check size is 6 inches by 2 3/4 inches. If you're designing from scratch, use those exact measurements. Anything else and you risk feeding issues at the bank. Most people skip this and use a generic document size, then wonder why prints come out cut off or with weird margins. The MICR line at the bottom needs special attention. That's the series of numbers printed with magnetic ink that bank sorting equipment reads. It contains your routing number, account number, and check number in a specific format. The font used for this line has to be E-13B or CMC-7 compliant. Using a regular monospace font won't work. I once saw a startup try to print MICR lines using Courier New and send them out. The receiving banks rejected the entire batch. The workaround was simple - switch to a proper MICR font and add a warning flag in the template that lights up if the font doesn't match the requirement. I use a conditional formatting rule that turns the MICR field red if the font isn't set correctly. Here's something most guides don't mention: the order of elements on the template matters more than you'd think. Banks process checks from top to bottom, left to right. If your layout has conflicting visual hierarchy - say, the dollar amount box draws the eye before the payee line - it increases the chance of manual processing errors during high-volume scanning. I rearranged my template so that the payee field comes first, then the date, then the amount boxes. It sounds minor but it reduced our exception processing rate by about forty percent over a quarter.
Common Pitfalls That Break the System
Font embedding is the silent killer. When you generate checks digitally and someone opens the file on a machine that doesn't have your template fonts installed, the text shifts. Fields move. The date ends up overlapping the amount box. Always embed fonts in your final output or convert everything to outlines before distribution. This alone accounts for maybe sixty percent of the support tickets I see in banking automation forums. Another issue is variable length data handling. Payee names vary. Addresses vary. Memo fields vary. Your template needs either dynamic text boxes that expand or a strict character cap enforced at the input stage. I recommend both. Build a mask that truncates with an ellipsis and alert the user before submission. It's better to lose a few characters of a memo note than to reprint fifty checks because the layout broke. There's also the issue of blank check generation. Some systems auto-increment check numbers sequentially. If your template doesn't enforce uniqueness checks against a master register, you'll accidentally duplicate numbers. I ran into this when migrating from a paper-based system to a digital one. Two checks came back with the same number. The reconciliation took three days to sort out. Now I run a uniqueness validation query before any template batch generates, and it takes about twelve seconds for a thousand checks.
Get the Full Details
Practical Workflow for Template Use
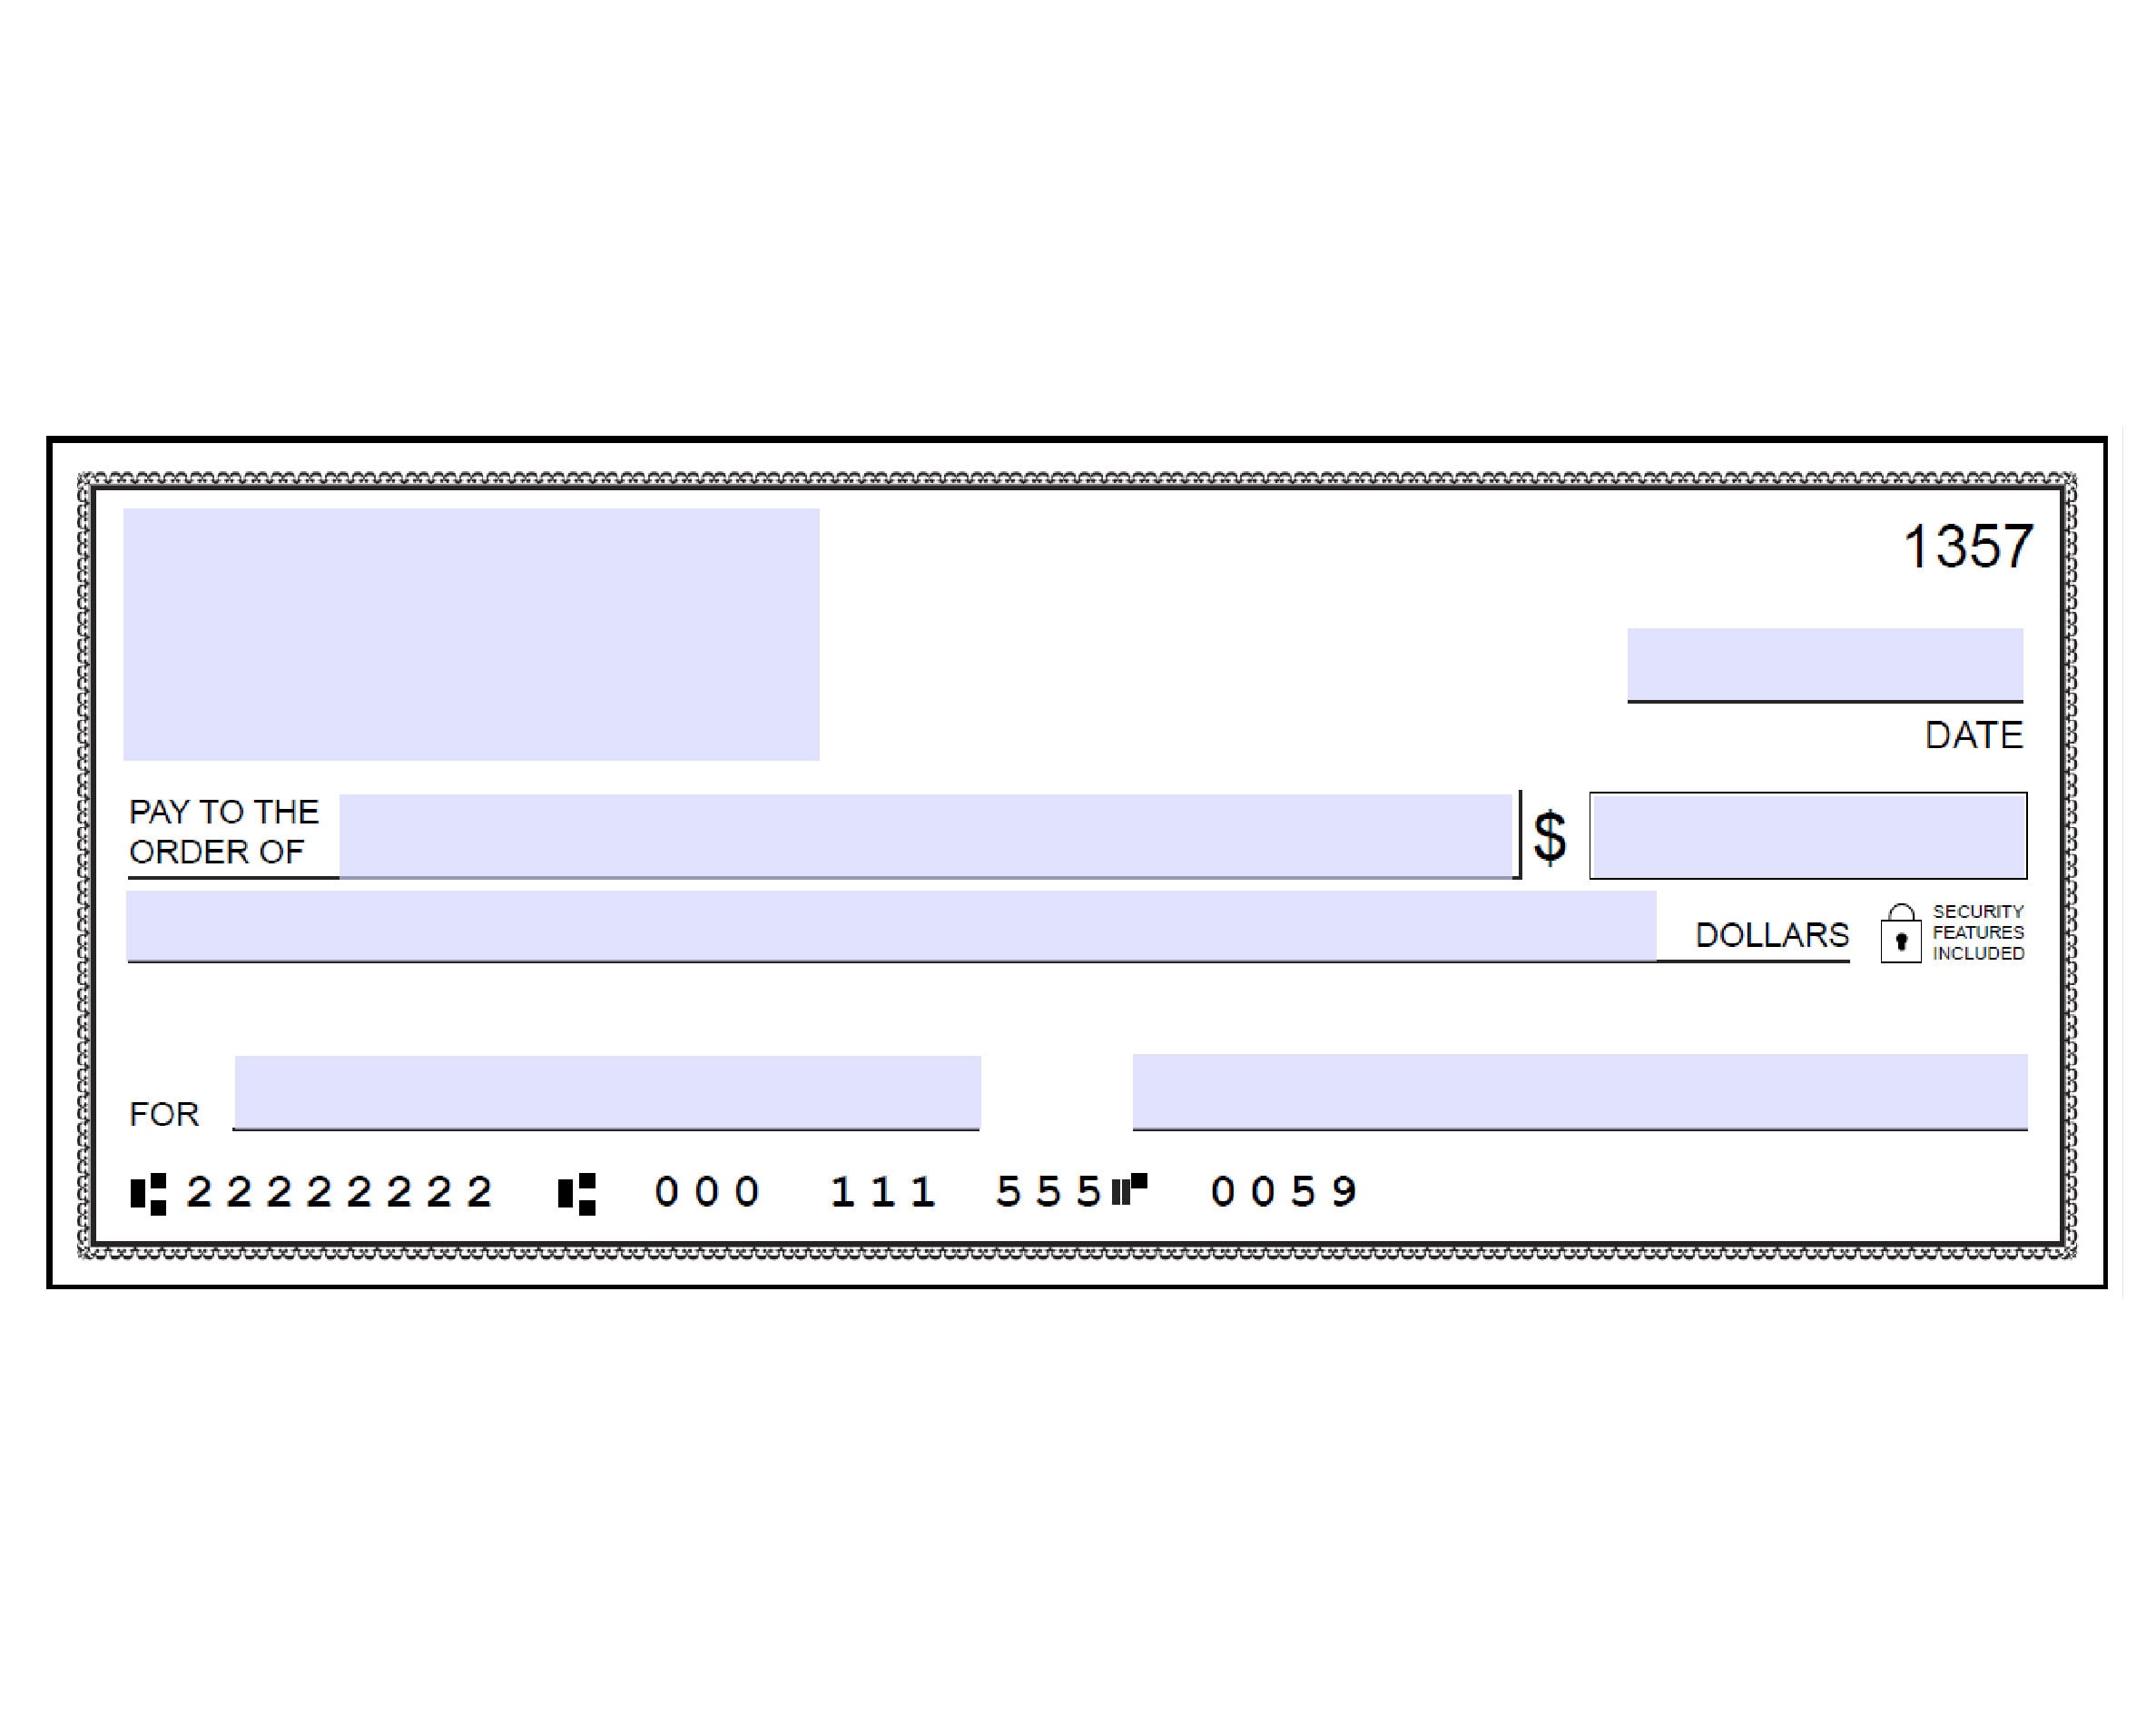
Set up your template with placeholder tags rather than hardcoded values. Something like [PAYEE], [AMOUNT], [DATE], [ROUTING], [ACCOUNT]. This way you can swap in data programmatically without editing the layout each time. I use a simple CSV import system where the template engine reads the file and fills in each tag. It handles about two hundred checks per run without issues. Always do a test print on blank stock before running a full batch. I make it a rule - no exceptions. Even if you've printed from this exact template a hundred times before. One of my colleagues skipped this on a Friday afternoon and printed four hundred checks with the routing number off by one digit. The template had been accidentally overwritten earlier that day with a stale version. He spent the next two days calling vendors to recall payments. The fix was straightforward: version control the template files and lock them after approval. I use a simple hash check that flags any template that's been modified since its last approval timestamp. If you're handling large volumes, consider a watermark or serial numbering overlay that's separate from the MICR line. This helps with internal tracking without interfering with bank processing. I layered a faint alphanumeric code in the corner that my internal audit system can read but doesn't show up on bank scanners. It's been useful for tracking which department issued which check without adding complexity to the main template.
Where Check Template Falls Short
No template system is perfect. They struggle with international checks that have different formatting requirements. If you ever need to issue checks in euros or pounds, the standard US template won't work and you'll need region-specific layouts. The MICR standard itself changes between countries. The E-13B font I mentioned is American and Canadian. European banks often use different magnetic ink standards altogether. Digital check templates also face limits with fraud detection. A static template can't verify whether the person filling it out is actually authorized. I've seen cases where someone with basic access to a template system generated checks outside their approval range because the template had no enforcement layer. The workaround is adding role-based access controls at the application level, not in the template itself. The template should only define the layout. Security belongs in the wrapper around it. For teams that need more flexibility than a fixed template allows, some move toward dynamic document generation tools that build checks on the fly from database fields. It's more complex to set up but handles edge cases better. I'd recommend starting with a solid Check Template approach and upgrading only when you hit the walls I described above. Most teams never reach that point.