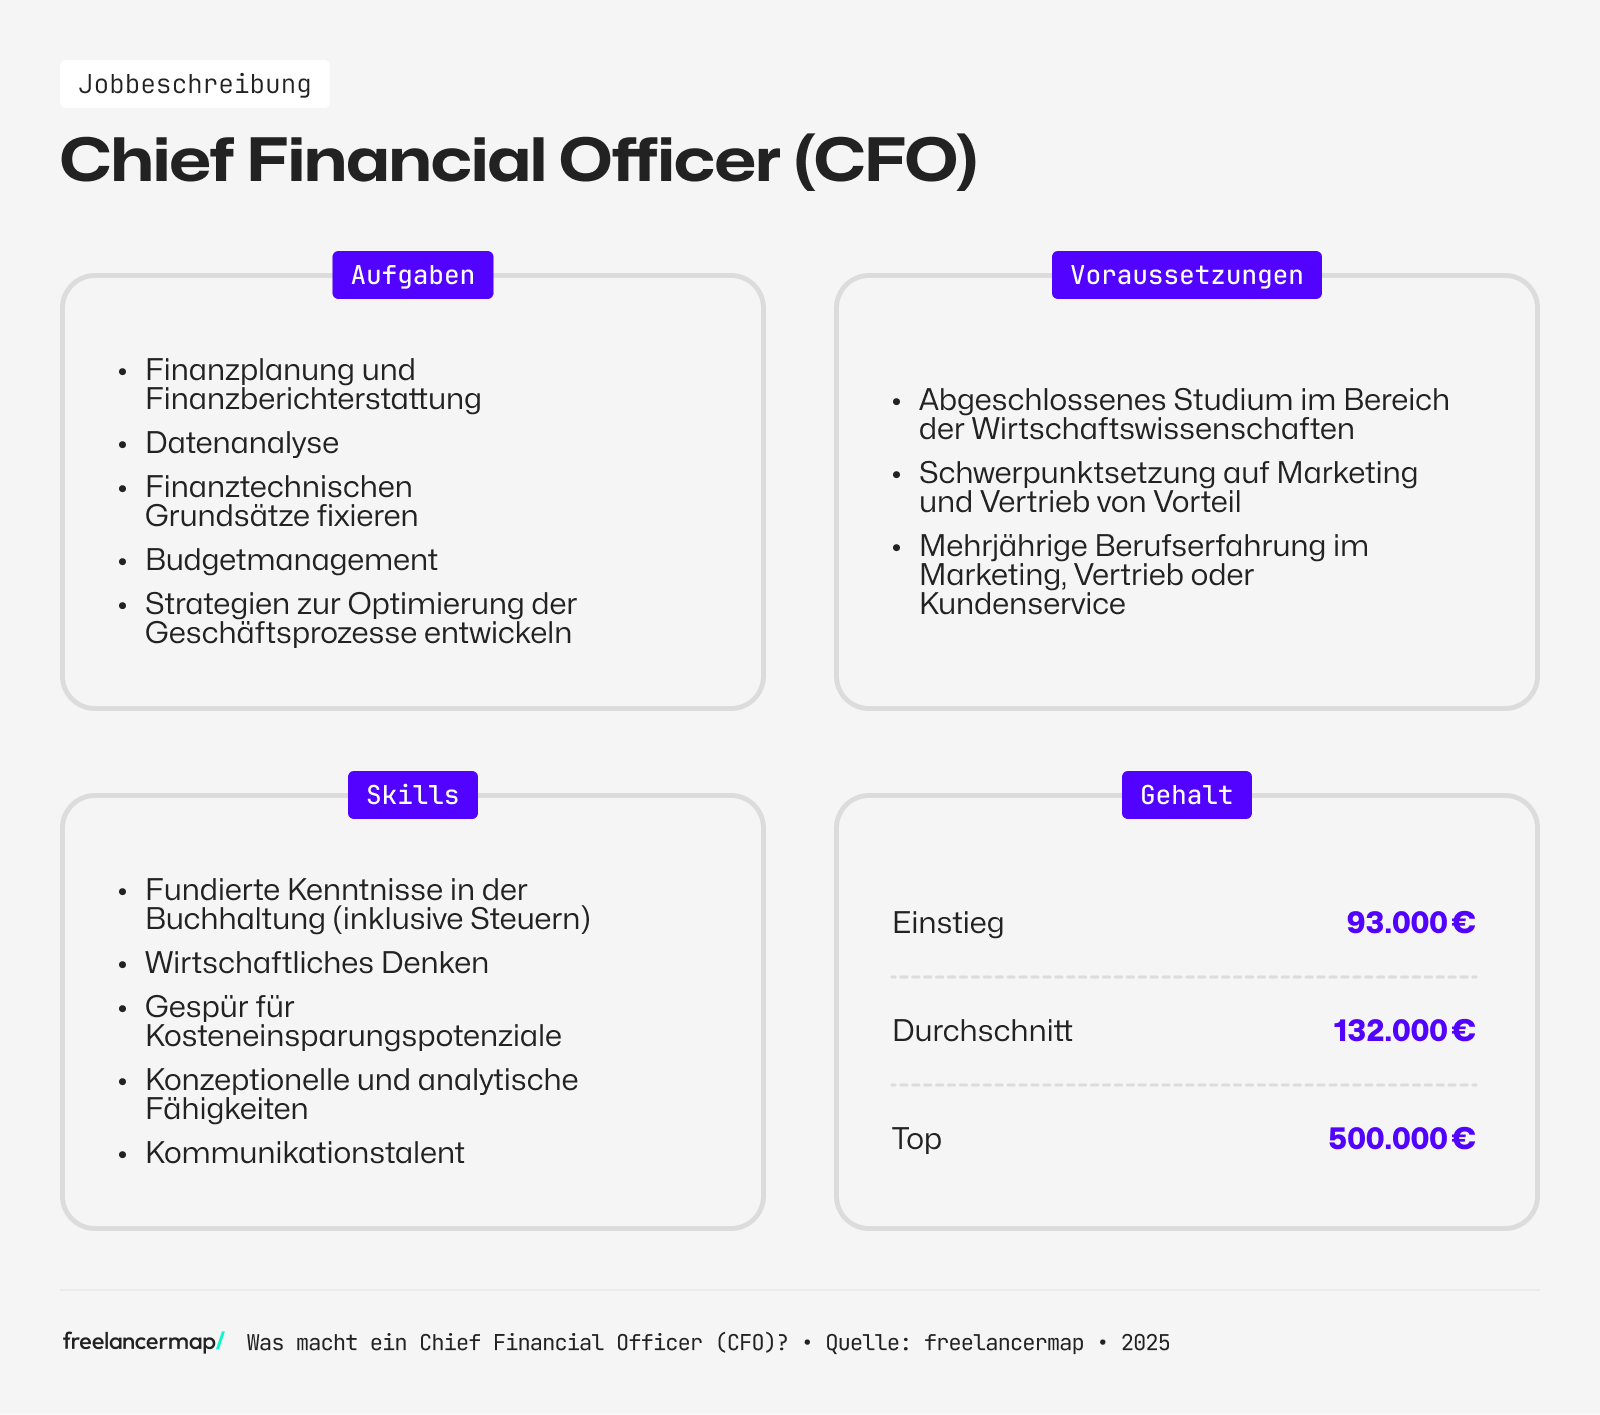
The role of a CFO in Germany isn't dramatically different from anywhere else on paper. You manage cash flow, you oversee reporting, you keep the auditors happy, you deal with taxes. Where it actually gets complicated is in the execution. The German system layers bureaucracy, co-determination rules, and tax code provisions that most English-language guides either ignore entirely or gloss over in three sentences.
I spent about four years managing financial operations for a mid-size manufacturing company based in Bavaria, with a US parent company. That setup meant daily collision between German commercial code (HGB), US GAAP, and whatever the local tax office wanted that month. It wasn't glamorous. Here's what I actually learned.
The dual reporting reality
In Germany, you're typically producing financial statements under HGB for the Handelsregister and tax purposes, and often separately under IFRS or US GAAP for group reporting if you're part of an international structure. These aren't the same numbers. Good examples show differences in revenue recognition timing, provision accounting, and how you treat R&D costs. HGB is conservative by design. IFRS is more economic substance driven.
The practical problem: your German tax advisor wants one set of numbers, your group controller wants another, and the audit firm is scrutinizing the bridge between them. In my experience, the most efficient setup is maintaining a single chart of accounts that maps cleanly to both frameworks, with a reconciliation layer built into your ERP. If you're still doing this manually in Excel spreadsheets that nobody can trace, you're going to have a very long fiscal year end.
Works council involvement you can't ignore
This is the part that catches people off guard. In companies above a certain size, the works council (Betriebsrat) has co-determination rights on matters that include workplace organization, performance evaluation systems, and — critically — decisions about staff reductions or structural changes that affect employees. Financial decisions don't exist in a vacuum. If your CFO role involves restructuring, hiring freezes, or bonus scheme changes, you'll likely need to negotiate with the works council before implementation.
I learned this the hard way in 2019 when we tried to restructure our European operations to reduce headcount by about fifteen percent. We had the board approval, we had the financial model showing break-even within eighteen months, and we moved forward without proper works council consultation. The council filed an injunction that blocked the restructuring for eleven months. Not because they disagreed with the economics. Because the process was wrong.
The workaround was straightforward but costly: we built a two-track communication plan that included the works council from the earliest planning stage, even though we had no legal obligation to involve them until we were ready to announce anything. They couldn't block the decision, but they did extract concessions on severance packages and transition support that cost us roughly two hundred thousand euros. Worth it in hindsight because we actually implemented the restructuring instead of sitting in legal limbo.
Tax-specific complications
German corporate tax is a combination of Körperschaftsteuer at roughly fifteen percent plus Gewerbesteuer, which varies by municipality and can add another fourteen to twenty-three percent on top. The effective rate depends heavily on where your company is registered. Munich and Hamburg will hit you differently than a small town in Saxony-Anhalt.
Then there's the trade tax (Gewerbesteuer) add-backs. Certain interest expenses and external rental payments get added back for trade tax purposes, which can substantially increase your liability compared to what the income tax calculation suggests. The interaction between tax planning and book accounting under HGB means you can't simply optimize one without affecting the other.
For foreign-owned companies, the transfer pricing documentation requirements are strict. You need contemporaneous documentation — meaning you prepare it while the fiscal year is still running, not after the fact. Germany's Finanzausgabenverordnung and the OECD alignment means your intercompany agreements, master file, and local file all need to be coordinated. I've seen deals fall apart because the German entity's pricing didn't match what the parent company's transfer pricing policy said, and the resulting adjustment triggered a double taxation dispute that took two years to resolve.
What the role actually looks like day to day
If you're stepping into a CFO position in a German context, your calendar will be dominated by a few recurring items: monthly closing (Monatsabschluss), which in Germany often includes specific statutory elements like the Anhang notes and Lagebericht, quarterly reviews for the supervisory board (Aufsichtsrat), annual financial statement preparation with the Wirtschaftsprüfer, tax filings on tight deadlines, and ongoing cash management because German banks still operate on procedures that assume you'll need to mail original documents somewhere.
Yes, some of that is digitizing. But if your main bank is still requesting paper payment orders for anything above a threshold, you need a process for it. I kept a standing folder in the office with pre-stamped envelopes for exactly this purpose. It sounds ridiculous until you're thirty minutes away from a payment deadline and the electronic system goes down.
Common pitfalls
The biggest mistake I see people make is treating the German CFO role as purely a financial position. It isn't. It's a compliance-heavy role with significant legal exposure. The Vorstand of an AG (public company) can face personal liability for delayed filing of annual statements. Section 93 of the Aktiengesetz is not theoretical. Even in GmbH structures, the managing director (Geschäftsführer) carries similar obligations.
Another pitfall is underestimating the audit process. German Wirtschaftsprüfer approach audits differently than their American or British counterparts. They tend to be more documentation-focused and less willing to accept management representations without supporting evidence. Budget six to eight weeks for the annual audit in addition to your closing timeline. Don't try to compress it.
A practical tip for smaller companies
If you're running a GmbH with revenues below about ten million euros, you likely don't need a full-time CFO on site. Many German small and mid-market companies outsource the CFO function to a controller service provider (Controllerdienstleister). This is legal, recognized, and used widely. The key is finding someone who understands both the local HGB requirements and whatever group reporting standards your shareholders expect. A generic accounting firm will handle your books but won't give you strategic financial leadership.
I worked with a Controllerdienstleister for eighteen months while we recruited a permanent CFO. They came from a Big Four background, charged about half what we'd budgeted for a full hire, and actually improved our month-end close from twelve days down to seven. The trade-off was they weren't available for ad-hoc board presentations at short notice. You'll need to factor that into your planning.
Gallery Chief Financial Officer Deutsch
Chief Financial Officer (CFO) | Berufsbild & Gehalt 2022 | Karriere
Chief Financial Officer (CFO) | Berufsbild & Gehalt 2022 | Karriere
Chief Financial Officer (CFO) | Berufsbild & Gehalt 2022 | Karriere
Chief Financial Officer (CFO) | Berufsbild & Gehalt 2022 | Karriere
Der Chief Financial Officer (CFO) – Eine Einleitung… | AlleAktien