Working with the Citi Economic Surprise Index in Practice
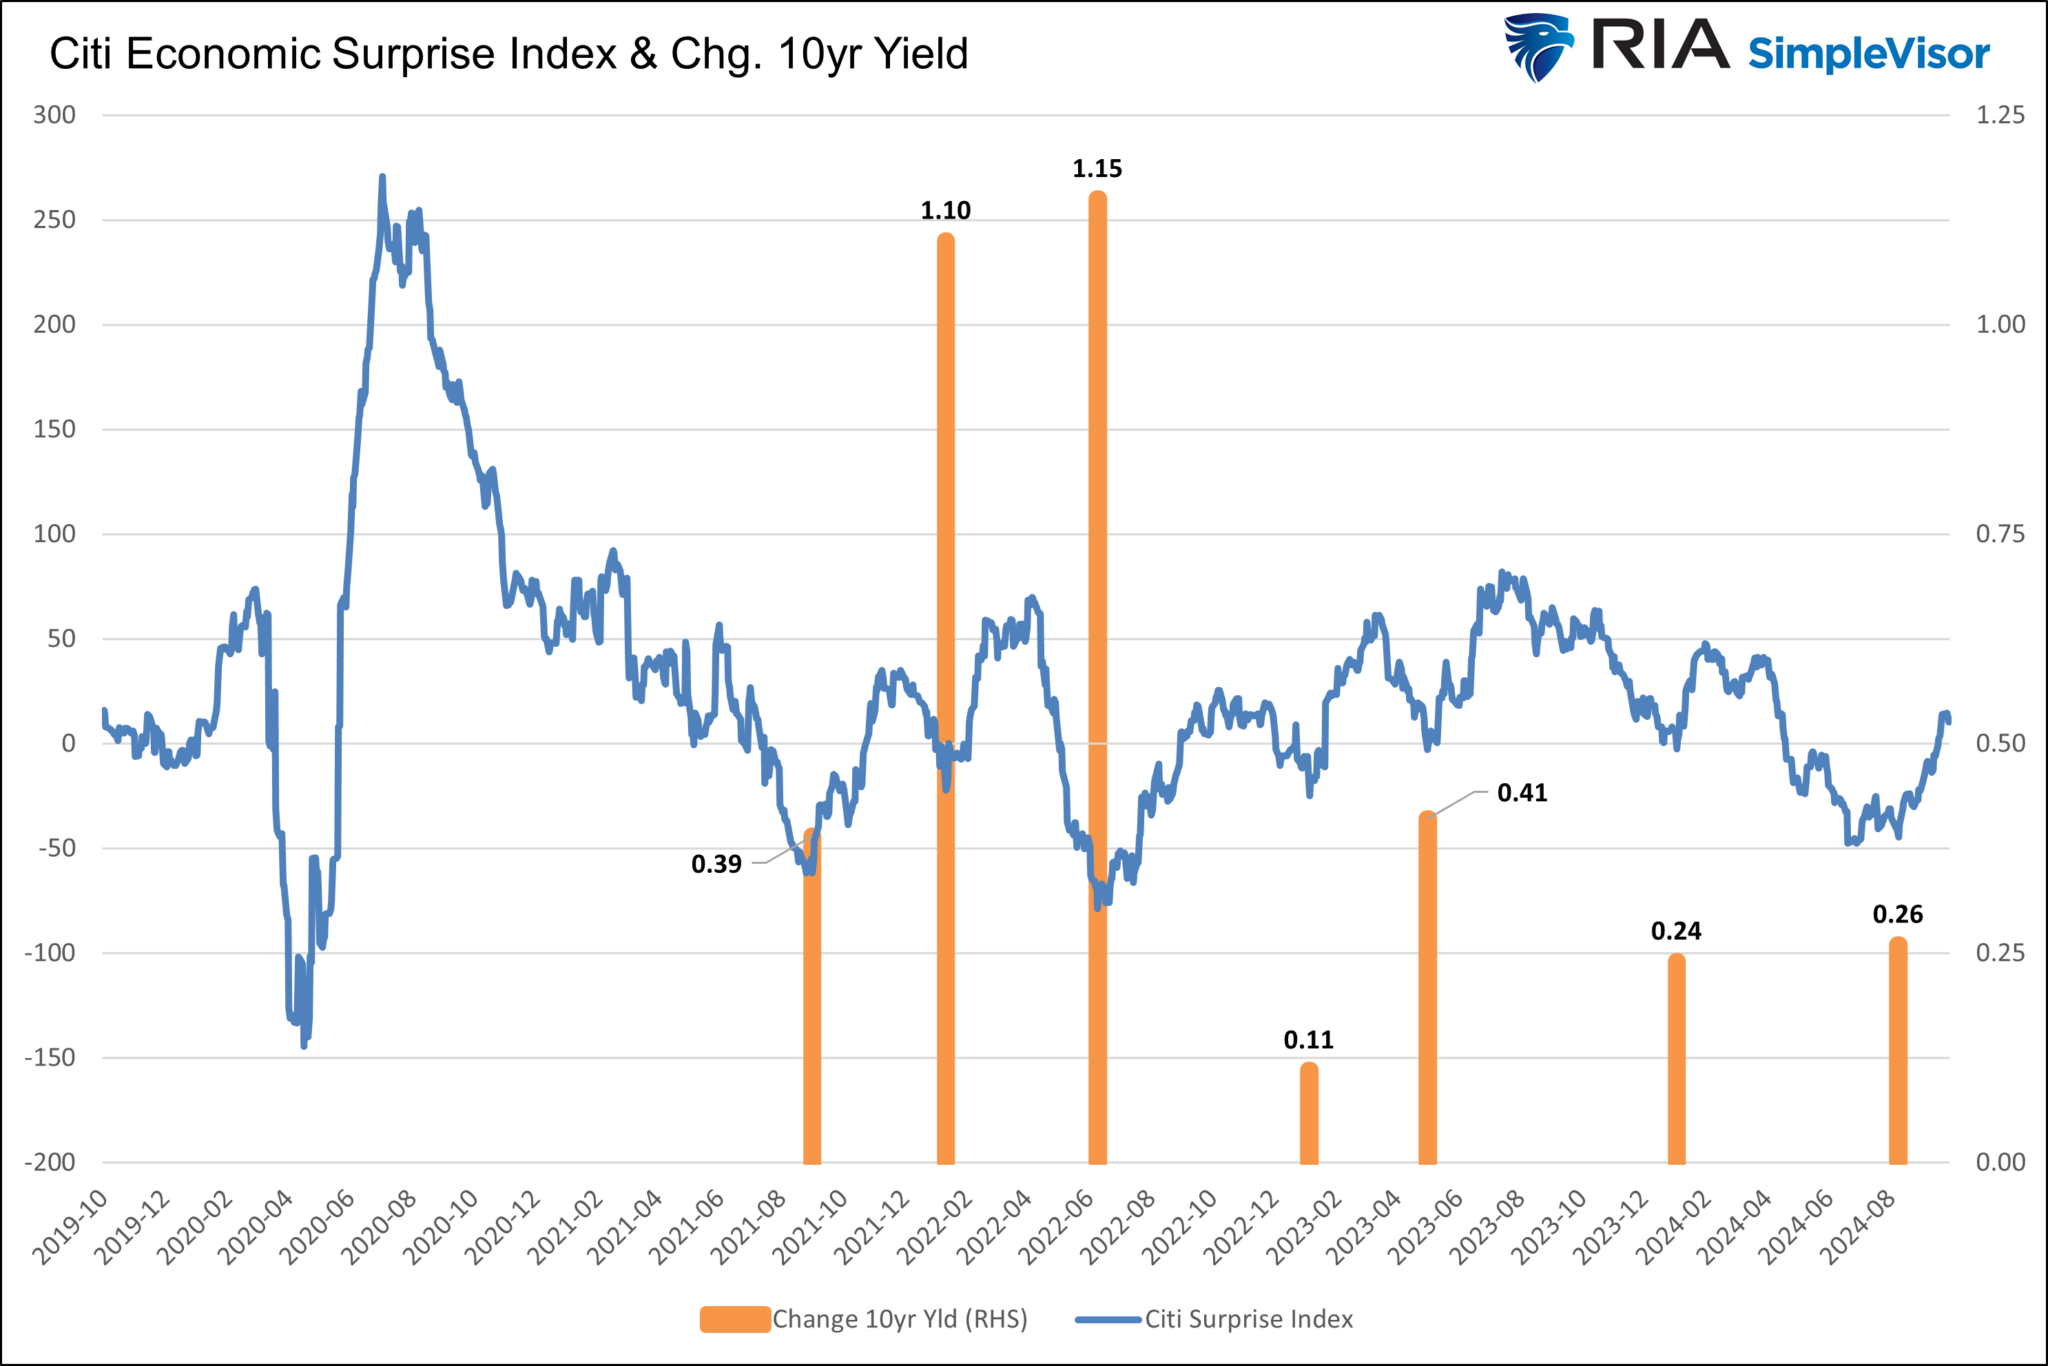
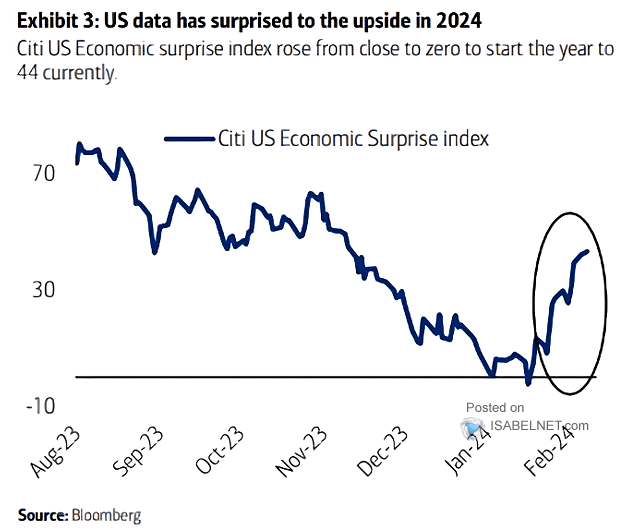
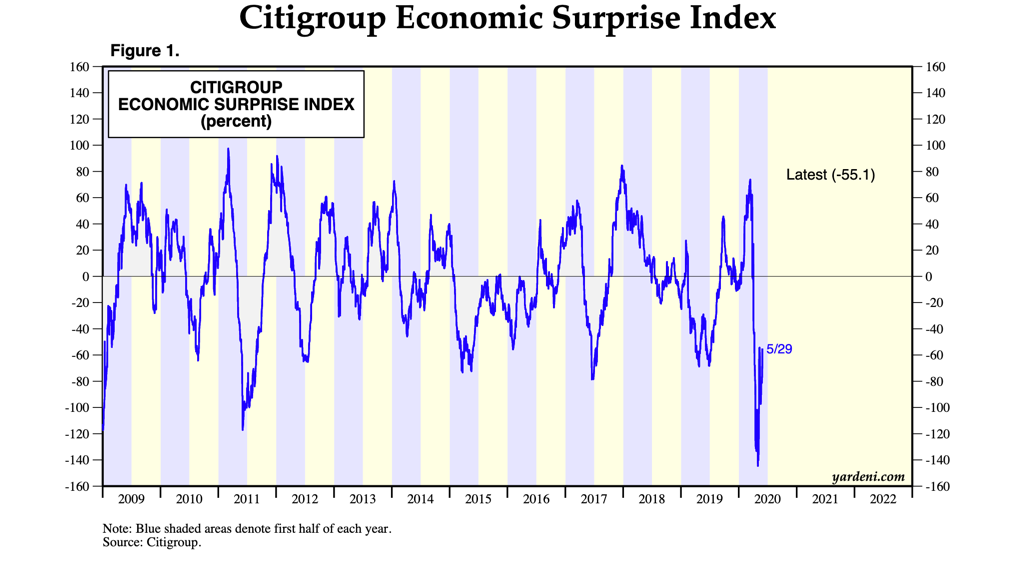
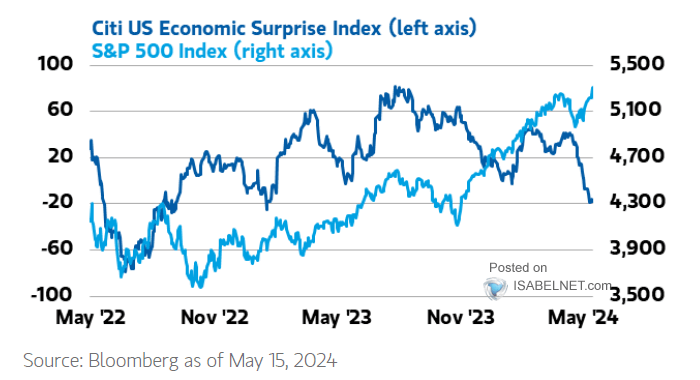
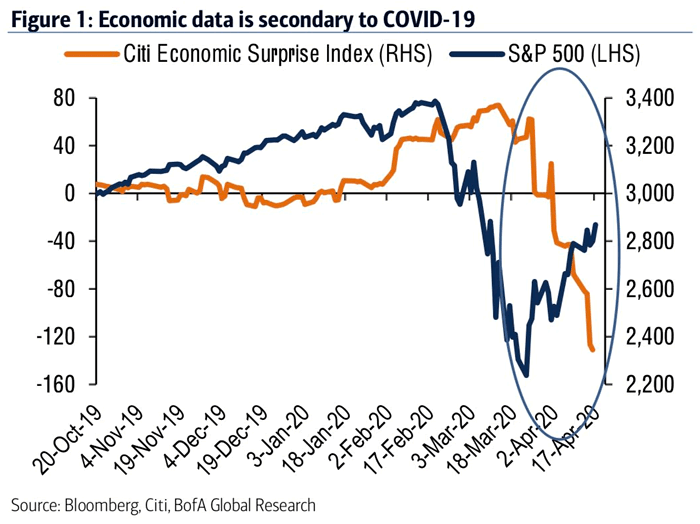
The Citi Economic Surprise Index measures the direction of economic data relative to forecasts, rolling across a basket of key indicators for major economies. A rising index means numbers are coming in hotter than expected. A falling index means the opposite. It is not a predictor in the traditional sense. It is a momentum gauge for macro data, and most people treat it like one when it is better used as a sentiment confirmation tool. I spent years running this index against my own forecasts at a research desk, and the first thing I learned was that the index is heavily dependent on Citi's proprietary forecast consensus. That consensus is built from survey responses, model estimates, and a handful of analyst inputs. When the survey response rate drops — which happens around holidays and in smaller economies — the consensus becomes thin and the surprise reading gets noisy. The US index is stable year-round. The EM variants can go sideways for no good reason during August or late December because the underlying forecast data simply thins out.
Citi Economic Surprise Index Breakdown
The index uses a z-score approach on actual versus expected values, normalized and then aggregated. Each component has a weight based on its historical impact on growth and inflation expectations. The US version pulls from manufacturing PMI, services PMI, ISM employment, retail sales, building permits, jobless claims, consumer confidence, and GDP estimates, among others. The exact weights shift slightly over time because Citi rebalances based on which releases matter most for near-term growth forecasting. I ran into a real issue back in 2022 when the index gave a misleadingly strong read on US data for about three weeks straight. The problem was that housing starts and building permits were the outlier drivers in that snapshot, and those two releases are notoriously volatile and small-sample. The rest of the basket was flat to slightly negative. What looked like a sustained uptick in surprises was really just two noisy data points moving the needle. My workaround was simple. I stopped looking at the headline Citi US Surprise Index as a single number and started pulling apart the component z-scores myself. I built a quick spreadsheet that tracked the rolling 20-day contribution of each indicator to the aggregate. That way I could see when one or two heavy components were distorting the read. It took me about ten minutes to set up and saved me from positioning wrong on two trades that quarter. One thing most people miss is that the index is mean-reverting by construction. Because it is measuring surprises against forecasts, and forecasts themselves adjust to recent data, extreme readings tend to decay quickly. A reading above 1.0 or below minus 1.0 is not a signal to chase. It is usually a signal that the forecast consensus has not caught up to the latest data run rate yet. That gap closes fast, often within a week or two of new releases coming in.
Another nuance that nobody mentions in the summary literature: the index behaves very differently across frequency mixes. The US version blends high-frequency indicators like jobless claims with monthly releases like PMI. That creates a pseudo-daily series from monthly inputs, which means you can get a smooth-looking line that hides the fact that half the components have not actually refreshed in weeks. I learned this the hard way watching the European version in early 2023. The index showed a steady climb over a four-week stretch. But only two of the eight components had printed new data in that window. The rest were just holding their prior values. The trend looked real. It was mostly an artifact of stale inputs. If you want to use this index for anything other than curiosity, you need to know when it is most useful and when it is basically noise. It works best as a confirmation tool alongside other macro signals — yield curve moves, credit spreads, central bank speech analysis. On its own, it tells you direction, not magnitude or duration. It also breaks down during structural regime shifts. When the Fed moved abruptly from QE to QT in 2022, the index showed weak positives on growth data while financial conditions tightened dramatically. The two were sending opposite messages and the index alone would have given you the wrong answer if you used it as your only macro compass. The closest alternative if you need something more granular is building your own surprise index using Federal Reserve Haver Analytics or Bloomberg consensus data directly. You get control over the component selection and you can weight by market impact instead of Citi's internal methodology. The tradeoff is that it takes about two hours of setup and another hour to maintain each quarter when rebalancing happens. For someone who checks this daily, the effort pays off. For anyone who looks at it once a month, Citi's version is probably fine.
Get the Full Details
The data itself is freely available through the Citi website or through most terminal providers. You do not need a subscription to pull the raw index values. What you do need is the patience to understand the construction, because once you know how the sausage is made, you will stop trusting the headline number the way most retail traders do.