Navigating the Cochrane Asset Pricing Solutions Manual: A Practical Guide
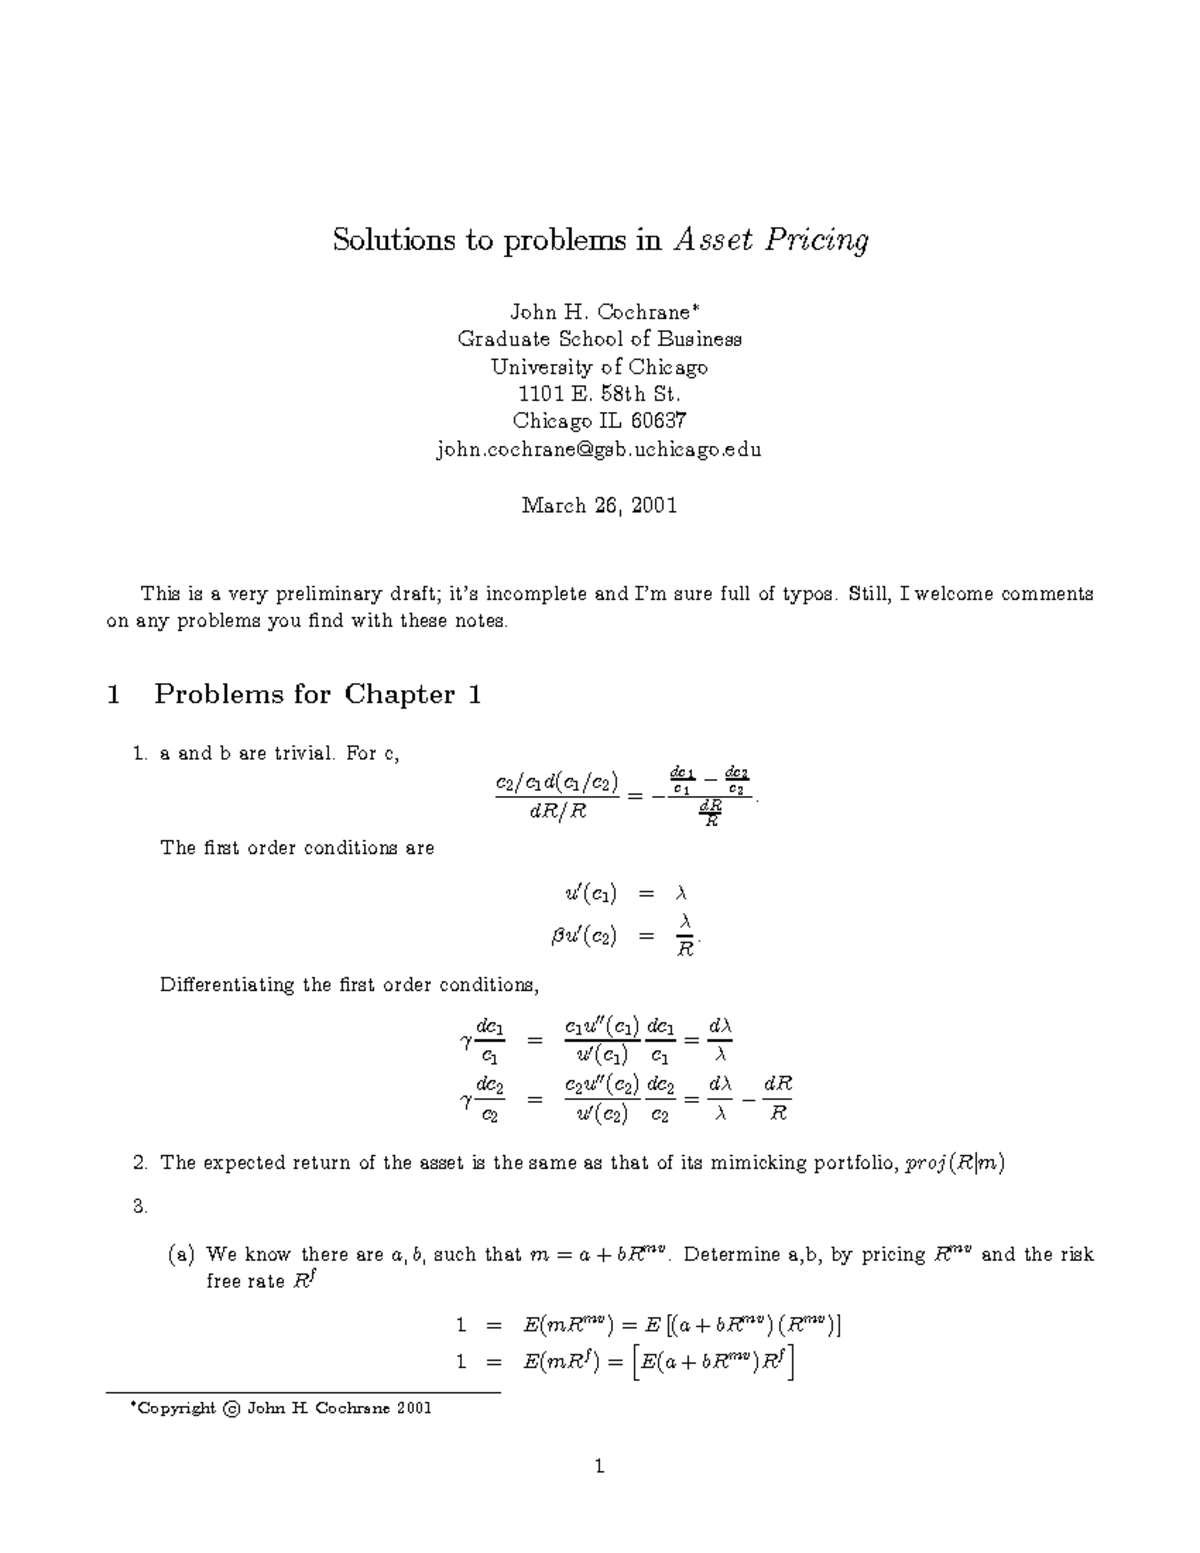
The Cochrane Asset Pricing Solutions Manual sits somewhere between indispensable and frustratingly incomplete, depending on how you use it. John Cochrane's textbook is the standard graduate-level treatment of asset pricing theory, and the solutions manual walks through many of the chapter exercises. It's not exhaustive, though, and it's written in a style that assumes you've already done the work and just need to check your logic. That assumption costs students time if you rely on it blindly. I spent several semesters working through these problems with graduate students, and the manual became useful only after we stopped treating it as a crutch and started using it as a debugging tool. The exercises build on each other in non-obvious ways. Getting stuck on Chapter 3's factor model derivations usually means you missed a subtlety in Chapter 2's stochastic discount factor setup, but the manual doesn't flag that connection explicitly.
Where to Find the Cochrane Asset Pricing Solutions Manual
The legitimate source is through the University of Chicago Press or directly from John Cochrane's website at the University of Chicago Booth School of Business. He maintains a page with lecture notes and selected solutions. The full manual typically comes bundled with course adoption materials rather than sold individually, which is why you'll see partial PDFs circulating on academic file-sharing sites. Be cautious with those copies. Some are scanned from older printings and contain known errata that were corrected in later editions. The differences usually show up in the consumption-based asset pricing chapter where the Euler equation derivations got revised after the initial publication. If you're a student without institutional access, check whether your program has a license. Several finance PhD programs purchase the complete supplementary materials for their candidates. A quick email to your program coordinator can resolve this in about ten minutes.
How the Manual Actually Works in Practice
The solutions follow a specific format that takes getting used to. Cochrane writes in what he calls a "skeleton key" style, meaning the proofs skip steps that he considers trivial. For someone reading through the manual for the first time, trivial is not a stable category. A two-line derivation in the manual might require three pages of working to unpack if you're not already comfortable with matrix algebra and measure-theoretic probability basics. I encountered a particularly ugly edge case while grading Problem 5.4 from the factor model chapter. The solution in the manual assumes the covariance matrix is strictly positive definite, which fails when you have more factors than return instruments and some factors are perfectly collinear in the sample. Students who plugged the formula straight from the manual into a dataset with near-perfect multicollinearity got garbage eigenvalues and spent hours wondering what went wrong. The workaround was straightforward: add a small ridge penalty to the covariance matrix before inversion, or switch to a SVD-based approach. This isn't mentioned in the manual, and it's the kind of practical detail that separates someone who understands the material from someone who can actually implement it. The consumption CAPM section in particular requires careful attention to timing conventions. The manual uses the same notation throughout, but different textbooks handle the timing of consumption and returns differently. If you're cross-referencing with another source, you need to track whether the Euler equation is written with today's marginal utility priced against tomorrow's payoff or vice versa. A sign error here cascades through every subsequent derivation.
Get the Full Details

Common Pitfalls and What the Manual Doesn't Tell You
One counter-intuitive point that trips up even advanced students is the relationship between the stochastic discount factor and mean-variance efficiency. The manual presents the Hansen-Jagannathan bound as a clean theoretical result, but in practice, estimating it from data produces wildly unstable bounds unless you impose strong restrictions. I've seen students interpret a broad HJ bound as meaning "the model is weak" when the real issue was simply that their sample covariance matrix was poorly conditioned. The bound itself is not the problem; the data is. Another frequent mistake involves the perpetual bond pricing exercise. The manual's solution assumes an infinite horizon with constant parameters, but when you work through the algebra, the closed-form solution only holds under very specific parameter restrictions on the discount factor and consumption growth. I once had a student submit a numerical solution that diverged because they'd picked parameter values outside the convergence region without checking. The manual never states the convergence condition explicitly. It's derivable from the geometric series formula, but finding it requires going back to first principles rather than trusting the presented answer. The intertemporal CAPM chapter contains exercises on the ICAPM hedging demands that assume frictionless markets. If you're applying these results to actual portfolio construction, you need to account for transaction costs and short-sale constraints, which the manual does not address. The theoretical results are correct within their assumptions, but the assumptions are the kind that vanish immediately upon contact with real data.
Using the Manual Effectively
The most efficient approach is to attempt the problem yourself first, get stuck, then consult the relevant section of the manual. The manual is better suited for unblocking a specific step than for learning the material from scratch. Reading through solutions without doing the work produces the illusion of comprehension that collapses under examination conditions. I recommend keeping a separate notebook where you re-derive the skipped steps. This takes longer initially but pays off quickly when you need to extend the model to a non-standard setting, which is exactly what happens in thesis work and research. The manual won't help you with those extensions because they're, by definition, outside the scope of the standard exercises. For computational exercises, consider implementing the solutions in Python or R and comparing your output against the manual's numerical answers. This catches both algebra errors and implementation mistakes. The manual's numerical results are generally accurate but are rounded, so slight discrepancies in the third or fourth decimal place are normal and not a sign of error.
Limitations and When to Look Elsewhere
The Cochrane Asset Pricing Solutions Manual has real limitations. It covers a narrow set of problems, mostly from the core chapters. If your course emphasizes empirical methods or calibration exercises, the manual provides limited support. For that, you're better served by supplemental resources like the exercises from Bernard Dumas and Jean-Luc Gaspar's work on empirical asset pricing or the computational notebooks available from various university course pages that complement Cochrane's text. The manual also reflects the state of the field as of the first edition. Some areas, particularly around long-run risk models and heterogeneous agent frameworks, have evolved significantly since publication. The solutions won't address newer developments, and that's not a criticism of the manual itself but a recognition that no single resource can keep pace with active research areas. For students working on dissertation chapters involving asset pricing, the manual is a starting point, not a destination. The real learning happens when you take a result from the book, modify an assumption, and see what breaks. That's where the manual becomes genuinely useful because you can verify your base case before introducing changes.