Most amortization calculators online are built for residential mortgages. They assume fixed rates, level payments, and straightforward compounding. Commercial loans don't work like that. You need something more flexible. A Commercial Amortization Calculator has to handle balloon payments, varying interest periods, different payment frequencies, and the occasional weird structure that comes out of a broker's office.
Here's how to build one that actually works for commercial real estate lending.
Core Inputs and Output Structure
You need these fields at minimum:
- Loan amount (principal)
- Annual interest rate
- Amortization period (in years or months)
- Payment frequency (monthly, quarterly, annual)
- Term length (how long the loan actually runs before balloon or refinance)
- Compounding frequency (monthly, semi-annually, annually)
- Whether payments are fixed or variable
- Start date and end date
- Optional: prepayment penalties, fee structures, escalation clauses
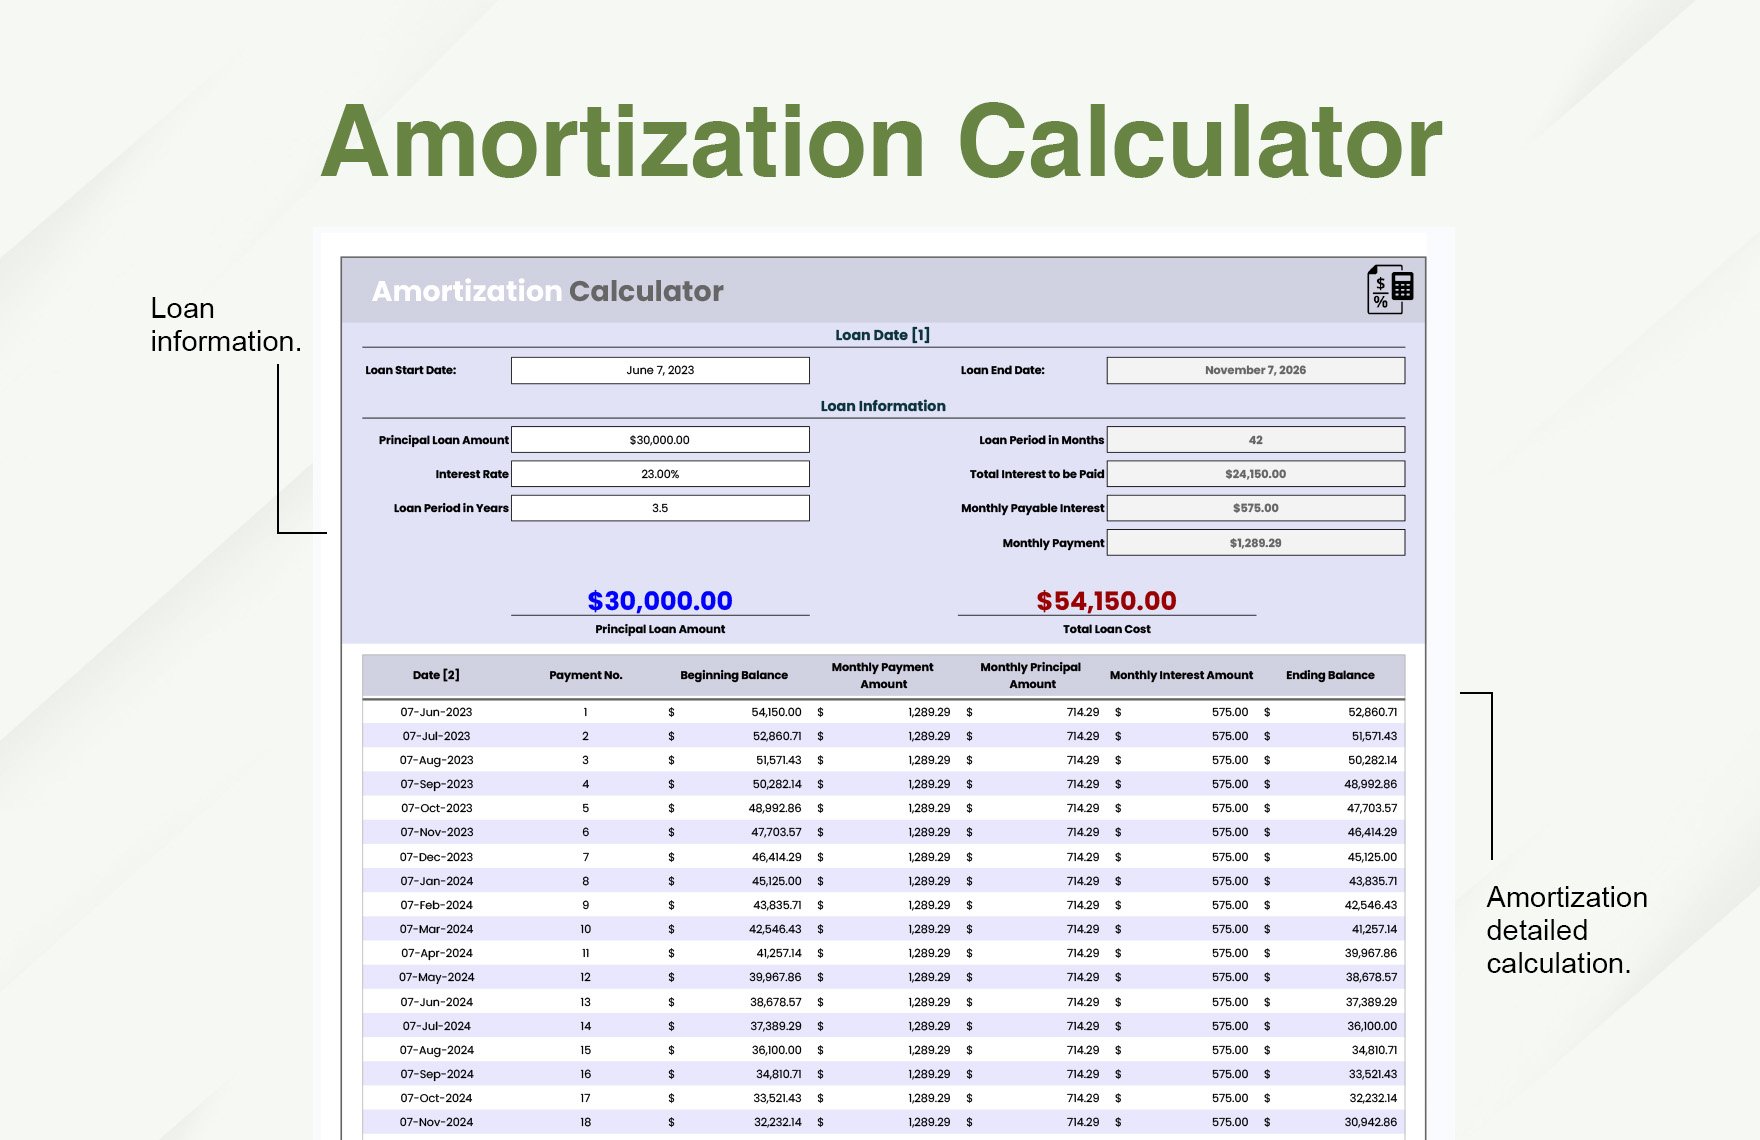
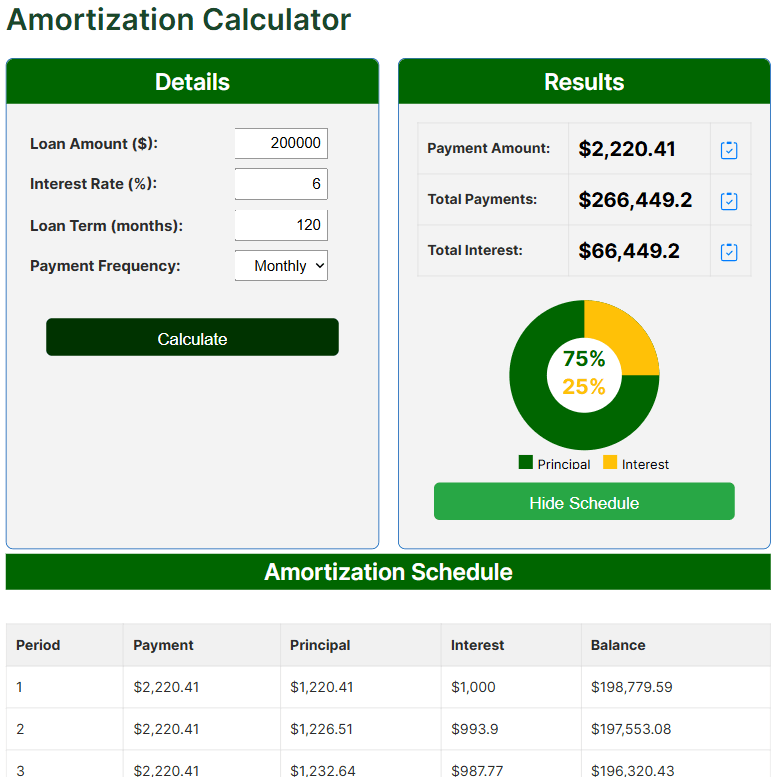
The output should show a full payment schedule table with columns for: payment number, payment date, beginning balance, principal portion, interest portion, ending balance, and cumulative interest paid. Include a summary sheet with total interest, total payments, and effective annual rate.
The formula you're working with is the standard annuity equation rearranged for payment amount:
PMT = P × [r(1+r)^n] / [(1+r)^n - 1]
Where P is principal, r is the periodic rate, and n is the total number of periods. That gives you the payment amount. Then you iterate through each period, recalculating the interest portion as the remaining balance times the periodic rate, and the principal portion as the payment minus that interest. Subtract the principal portion from the balance and repeat.
This is where most people mess up. They calculate one payment and stop there. A commercial amortization calculator needs to show the full schedule, especially because the balloon payment at the end is often larger than the entire amortized balance people expect.
The Balloon Problem Nobody Talks About
I spent three weeks last year debugging a calculator that kept returning impossible results for a CRE bridge loan. The loan had a 25-year amortization but a 5-year term with a balloon payment at the end. The issue was that the tool wasn't correctly computing the remaining balance at month 60, which is just the present value of all remaining payments from month 61 onward.
The workaround: after calculating the regular payment based on the full amortization schedule, you compute the outstanding balance at the balloon date by treating the remaining payments as an annuity and discounting them back. The formula is:
Remaining Balance = PMT × [(1 - (1+r)^-(n-k)) / r]
Where k is the number of payments already made and n is the total amortization periods. Plug that remaining balance into the payoff column and you get the correct balloon figure. Without this step, your calculator will show the loan being fully paid off at the end of the term, which is wrong and misleading.
Why Commercial Is Different From Residential
Residential calculators assume the borrower pays down the entire balance over the amortization period. Commercial loans often have a much shorter term than the amortization period. The difference shows up as a balloon payment. This changes the risk profile entirely.
You also need to account for different compounding conventions. In the US, commercial mortgages commonly compound monthly. In Canada, they compound semi-annually even though payments are monthly. If you don't convert between these correctly, your payment numbers will be off by a measurable amount on large loans. A $5 million loan at 7% with semi-annual compounding instead of monthly can result in a payment difference of roughly $400 per month. That adds up to over $24,000 per year in interest variance.
Variable rate structures are another gap in most tools. A Commercial Amortization Calculator should allow the rate to change at specified intervals during the term. You handle this by recalculating the payment at each reset date based on the new rate and the remaining balance and remaining amortization period.
Implementation Notes
If you're building this in Excel, use a dedicated input section at the top with clear labels and color-coded cells. Put the amortization schedule below. Use Excel's PMT function for the base payment calculation and NPV or PV functions for the balloon balance verification. Circular references will appear if you link the payment back to the amortization schedule incorrectly. Break those loops by separating the calculation layer from the display layer.
If you're building this as a web app, use JavaScript for the schedule generation. Store each period as an object with all the relevant fields. Render the table with pagination if the amortization period exceeds 60 months. Include a download button for CSV export because commercial lenders always need to send schedules to underwriters or investors.
The effective annual rate calculation is important for commercial loans because the stated rate and the actual cost of borrowing can diverge significantly when fees are involved. Add an option to include origination points and other lender fees in the APR calculation. The method is straightforward: treat the fees as a reduction in proceeds and solve for the internal rate of return that equates the net proceeds to the payment stream.
Common Mistakes to Avoid
Don't round intermediate values. Round only the final payment and balance figures. Rounding at each period introduces drift that becomes obvious in the final payment, which often ends up being noticeably different from the others.
Don't assume all payments are equal. Some commercial loans have graduated payments, interest-only periods, or demand features. Your calculator should allow for payment changes at specific periods.
Don't ignore the day-count convention. Commercial loans typically use 30/360 or actual/365. The difference matters for partial periods at the start or end of the loan.
Don't forget that some commercial mortgages are structured as lines of credit with revolving balances. A standard amortization schedule won't work for those. You need a separate module that tracks draw periods, repayment periods, and available credit.
When This Approach Breaks Down
A basic Commercial Amortization Calculator handles standard fully amortizing loans and balloon structures well. It struggles with complex lease-dependent financing, shared appreciation loans, or structures where payments are tied to occupancy revenue. For those, you need a custom model built around the specific cash flow mechanics rather than a generic amortization engine.
Also, tax implications and depreciation schedules are outside the scope of any amortization calculator. Lenders sometimes confuse the two. Make sure your tool clearly states what it does and doesn't calculate so users don't mistake it for a financial advisory product.
The tool I ended up building took about four days of development after the initial bug fix. The final version handles monthly and quarterly payments, variable rates with configurable reset dates, balloon calculations with remaining balance verification, fee-inclusive APR, and CSV export. It runs in a browser with no backend requirements. Most people who need this just want something that gets the numbers right quickly and lets them share the schedule with their team.
Gallery Commercial Amortization Calculator
Amortization Calculator Template in Excel, Google Sheets - Download | Template.net
Amortization Calculator – Loan Payment & Schedule
Free Amortization Calculator - UScalculator.com
Amortization Calculator Calculate Your Annual Payment With Ease Excel | Template Free Download ...
Commercial Equipment Loan Calculator at Melody Hanks blog