The actual mechanics of getting decent at commercial claims adjusting
Most people think commercial claims adjusting is just reviewing papers and writing reports. It is not. The job is mostly figuring out who paid for what, whether the policy actually covers the loss, and then negotiating with people who want as much money as possible while you need to pay as little as possible. The training programs sold to beginners mostly gloss over that tension. I spent about nine years on commercial property and casualty claims before moving into a technical role. The people who actually survived this work learned specific habits early. The ones who burned out usually did it within eighteen months because they were still treating every claim like a math problem instead of a negotiation.
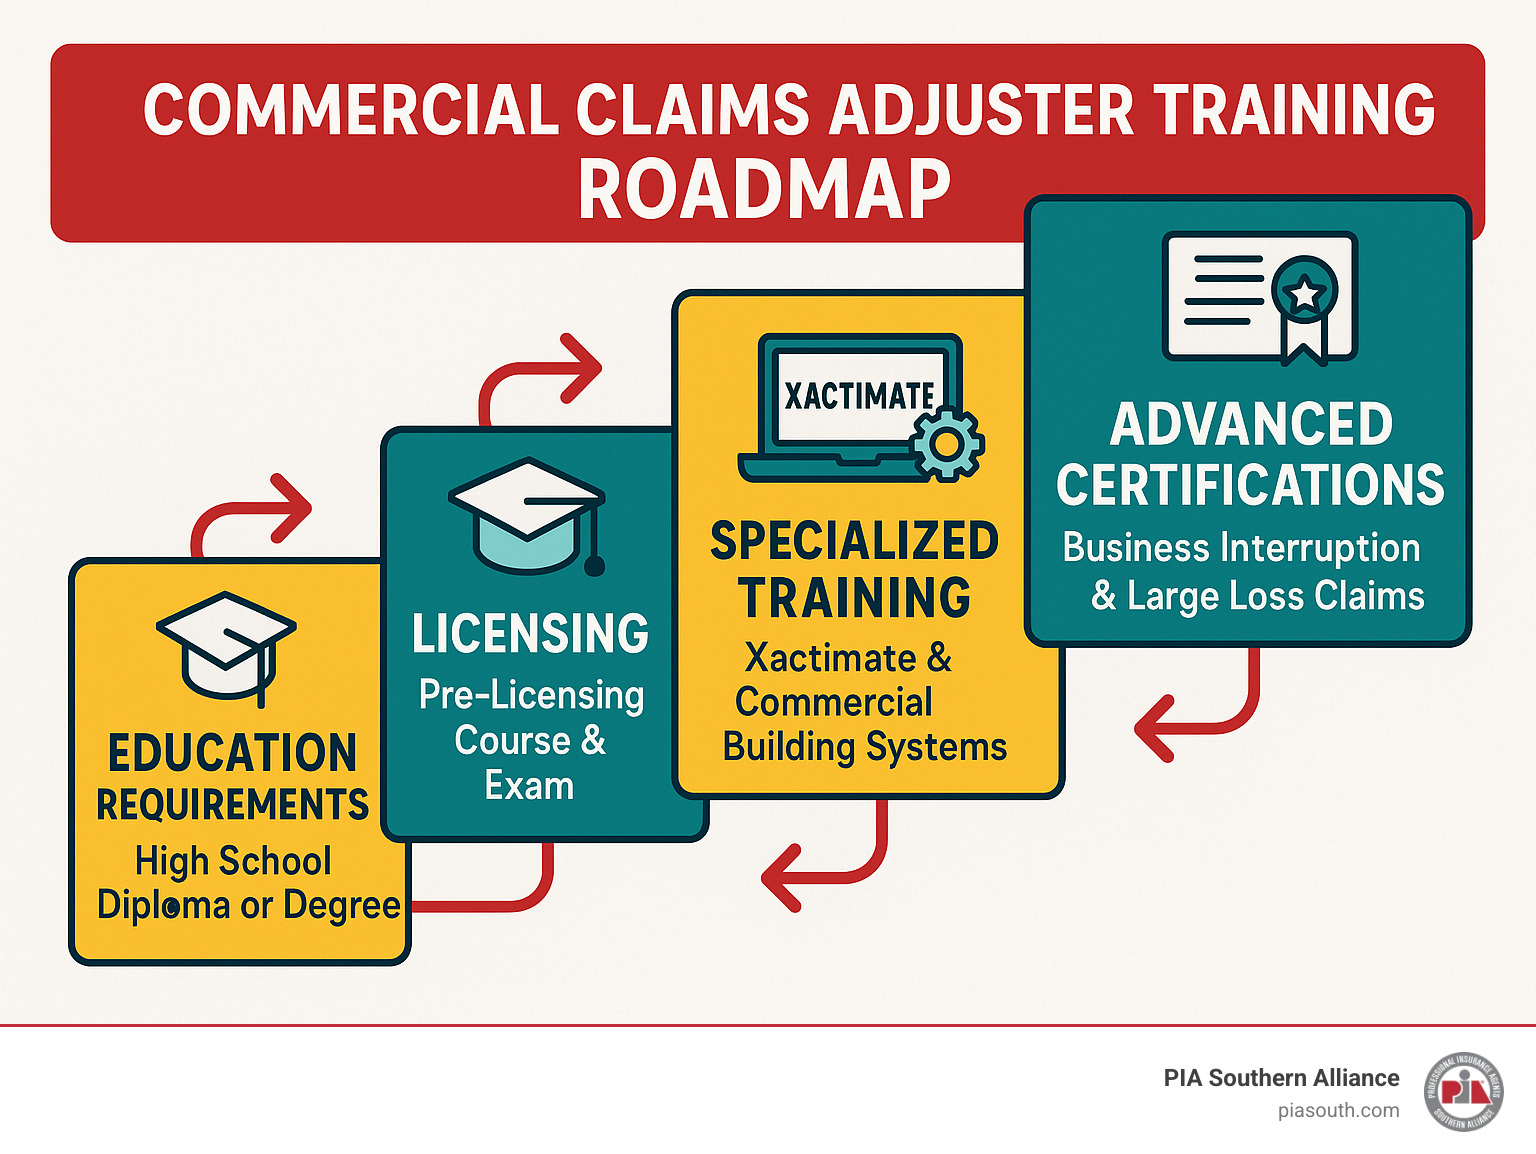
What Commercial Claims Adjuster Training Actually Covers
The legitimate programs teach three things in roughly equal measure: policy interpretation, investigative methodology, and settlement dynamics. Anything that focuses heavily on one of those to the exclusion of the others is incomplete. You can know every ISO form by heart and still get walked over by a plaintiff attorney who knows how to frame a demand. You can be a smooth negotiator and still miss a crucial endorsement that voids coverage entirely. Policy interpretation is where most training falls apart. Insurers use standard forms like the Business Auto Coverage Form (CA 00 01), the Commercial General Liability form (CG 00 01), and a hundred contractual modifications called endorsements. The endorsements are where the real work lives. A standard CGL policy might seem straightforward until you encounter an endorsement that adds contractual liability coverage with a $25,000 per contract limit and a requirement that the insured assume liability in writing before the insurer has any obligation. I once sat on a claim for six weeks because I kept reading the base form and missing an endorsement filed on page forty-seven of the binder that completely restructured the limits. Investigative methodology means knowing when to deploy independent adjusters, when to request recorded statements, and when to hire forensic accountants or engineers. The textbook answer is always a flowchart. The real answer depends on the dollar amount, the insureds cooperation, and whether you think fraud is in play. If a $2 million machinery breakdown claim shows up with perfectly organized financial records from day one, that is usually a sign someone is trying to make you believe a story too quickly.
Settlement dynamics gets the shortest shrift in most programs, which is strange because it is the part that determines your reserves and your loss ratios. The people you deal with on the other side have different incentives. Plaintiffs want maximum recovery. Defense attorneys want to minimize payout and billable hours. Your carriers want to close files and manage reserve volatility. Understanding that nobody has your interests at heart is the baseline.
Get the Full Details
How to structure your own training if the formal programs are lacking
Most employer-sponsored training is designed to get you producive fast, not to make you technically excellent. That is not a criticism. It is just how it works. You will learn more by reading actual claim files than by sitting through another webinar on soft skills. Start with the ISO forms. Not the summaries. The actual forms. Read a Commercial Package Policy from beginning to end while keeping a highlighting pen nearby. Mark every limitation, every exclusion, every definition that changes the ordinary meaning of a word. Do this for six policies and you will start seeing patterns. The pollution exclusion has been rewritten at least twelve times since 1986. The completed operations hazard exclusion does not mean what most junior adjusters think it means. Next, get access to closed claim files from your company. I know this sounds obvious but a lot of adjusters skip straight to the active work. Reading closed files teaches you how claims actually resolve. You will see reserve releases, you will see subrogation recoveries, you will see offers that were rejected and why. Pay attention to the files that went to bad loss ratio. Those are the ones that tell you where people made mistakes.
Learn to read financial statements. Commercial claims routinely involve business income exposure, extra expense calculations, and contingent business interruption. If you cannot read a profit and loss statement or a balance sheet at a basic level, you will miss significant damages or accept inflated ones. A lot of adjusters treat financial documents as black boxes and hand them to a forensic accountant. That is fine for large files. It is expensive and slow for small ones. I learned to do basic business income analysis myself so I could at least spot when a consultant was padding an estimate. Here is a specific edge case that nearly cost me a file once. I had a restaurant claiming business income after a roof fire. The insured provided a year of tax returns and a simple revenue projection. Everything looked clean. The numbers were internally consistent. I approved the estimate based on what I was given. Six months later, during a subrogation review, I found a secondary set of books that showed significantly higher cash revenue than what was reported to the IRS. The original estimate was off by roughly forty percent. The lesson was not that the insured was lying, which he might have been. The lesson was that I never asked to see the point-of-sale system reports or the bank deposits. I accepted the tax returns as definitive proof of income without verifying them against operational data. Since then, I require POS reports, bank statements, and supplier invoices for every business income claim over fifty thousand dollars. It adds about two days to the initial investigation but saves you from looking incompetent later.
Common pitfalls that ruin adjusters early
The first mistake is treating every claim the same. A $15,000 windscreen claim and a $750,000 commercial general liability claim should receive different levels of investigative effort. They are not the same problem at different scales. Some adjusters try to apply a uniform process to everything. They waste time on small files and undershoot their effort on large ones. The right approach is to triage by risk, not just by dollar amount. A $50,000 claim involving a dangerous condition on someone else's property with a plaintiff who has a lawyer might be riskier than a $200,000 claim where coverage is clear and the insured is cooperative. The second mistake is over-relying on the insured's version of events. The insured has an interest in the outcome. That interest is not always malicious. Sometimes it is just human. The insured wants their business to be recognized as viable after a loss. They will remember the good equipment and forget the obsolete stuff. They will emphasize the revenue that would have been made and downplay the expenses that would have been saved. I have seen insureds submit expense reports that included items unrelated to the loss, like a kitchen remodel that started two weeks before the fire and was already in progress. A third mistake is poor reserve management. Reserves are not estimates you set and forget. They are living numbers that should change as new information arrives. Junior adjusters tend to set a reserve and leave it alone until the file closes. That creates volatility in quarterly reports and makes you look careless. Review your reserves at every significant contact. Increase them when new exposures appear. Decrease them when you confirm coverage is narrower than expected.
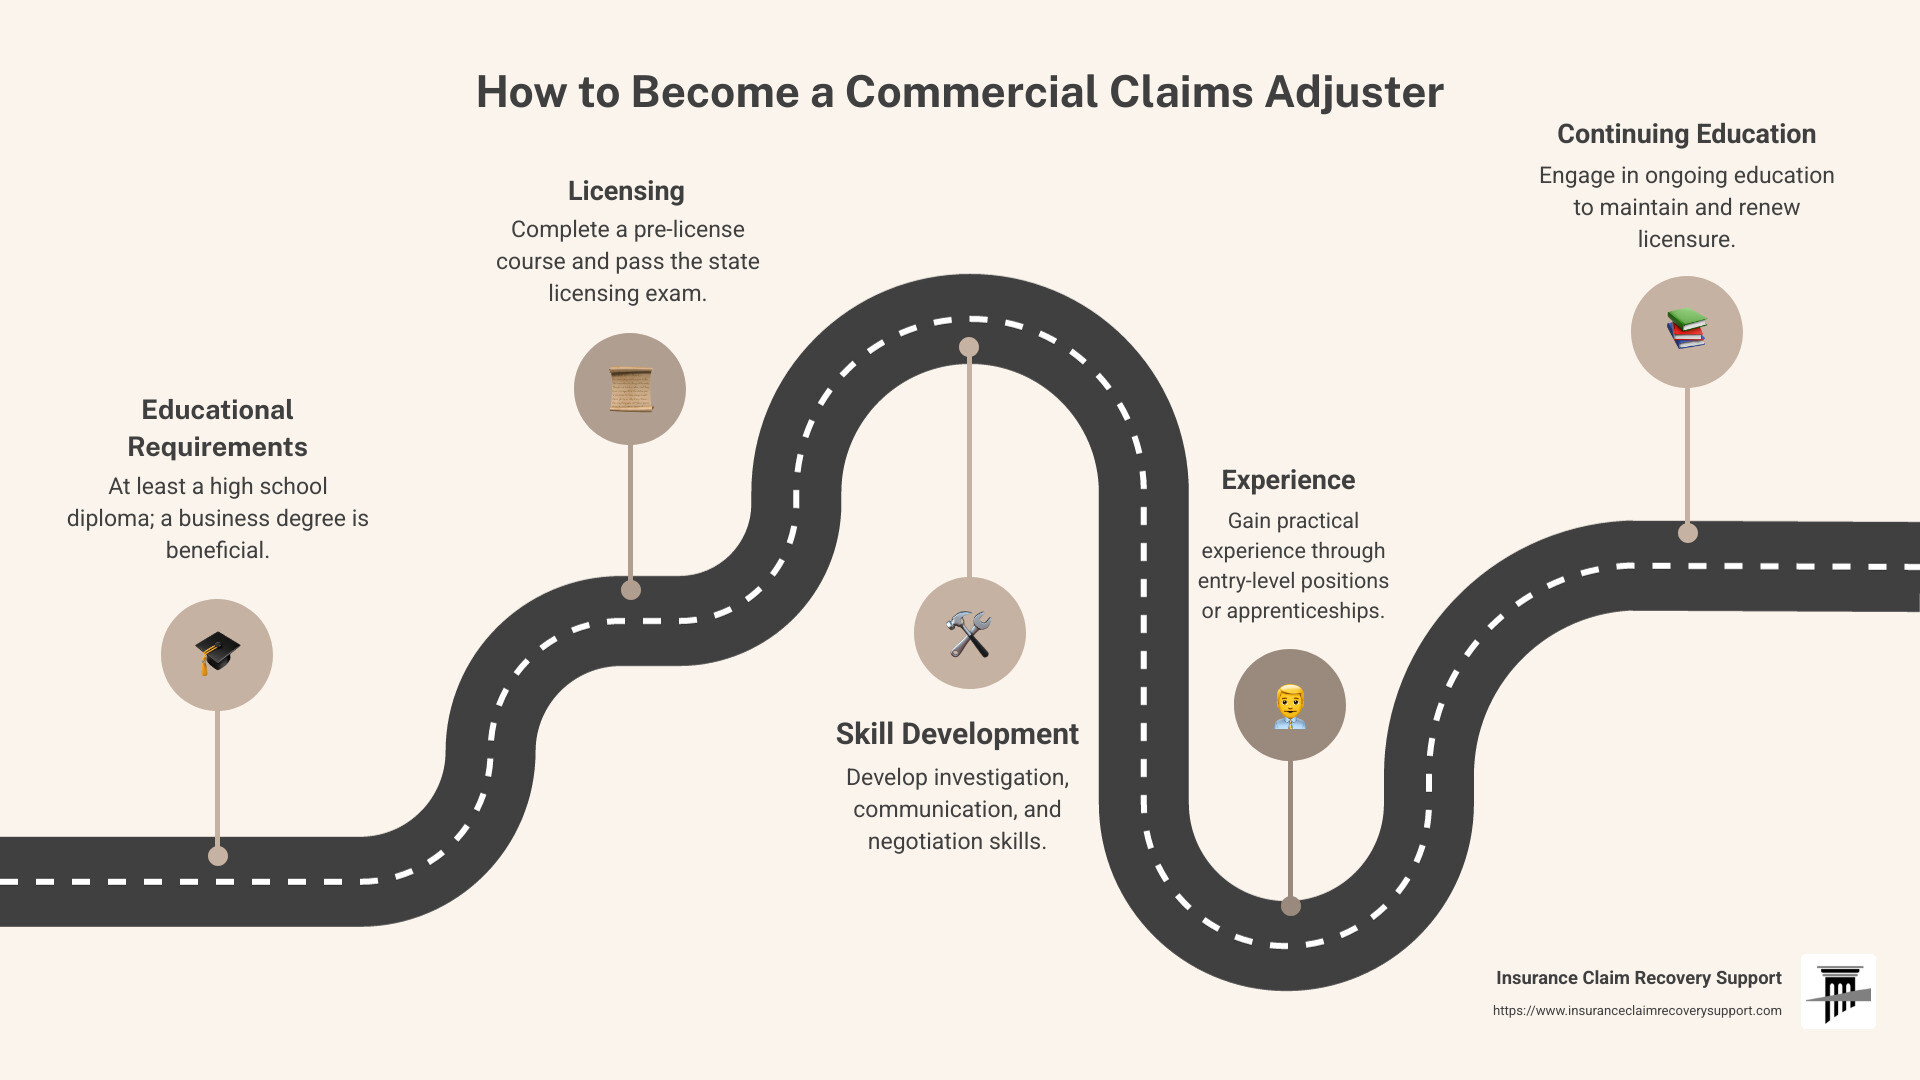
There is a trade-off in certification programs worth noting. The American Institute for Chartered Property Casualty Underwriters designation, or CPCU, is respected and covers risk management, insurance operations, and law. It takes about three to four years of study if you are working full time. The designation itself does not make you a better adjuster overnight. What it does is give you a framework for understanding how insurance works as a system. That framework helps you spot when a claim fits or does not fit the model. Without it, you tend to treat each claim as an isolated problem instead of a variation on a recurring theme.
Tools that actually move the needle
Claim management software like ACORD forms, xactimate for property estimates, and CDS for liability research are standard. Learning to use them efficiently matters more than learning every button. I have seen adjusters spend twenty minutes searching for a function that takes thirty seconds if they know the keyboard shortcut. Your speed on routine tasks compounds over a year. Microsoft Excel deserves more respect than it gets in this field. A solid grasp of pivot tables, vlookups, and basic statistical functions lets you analyze loss runs, compare settlement patterns, and build your own exposure models. You do not need to be a programmer. You need to be able to take a spreadsheet of historical claim data and produce a summary in under ten minutes without asking for help. Recorded statement software and transcription services are useful but not essential. What is essential is listening with intent. Most people recording statements focus on getting the words down. The useful information is often in what the witness hesitates on, what they volunteer without being asked, and what they avoid. I once caught a discrepancy in a recorded statement where the witness described seeing a wet floor sign near the entrance but never mentioned it during the initial interview. The sign had been there temporarily and was moved. That detail changed the comparative negligence analysis entirely.
Where these programs break down
Online courses are convenient but they cannot teach you the judgment calls. You can watch a video on how to evaluate a coverage position, but you cannot learn from it how to tell when an insured is deliberately being opaque. That comes from sitting across the table from someone and watching them talk their way around a question for forty-five minutes. Simulated claims exercises in training programs are usually too clean. Real claims are messy. Documents are incomplete. Witnesses contradict each other. Policies have ambiguous language. The training environments rarely replicate the pressure of a deadline combined with incomplete information. That gap is unavoidable. No simulation can replace the experience of having a file due and not having the evidence you need. Some training providers push specific platforms or methodologies that benefit from vendor relationships. Be aware of that. When a program tells you their proprietary system is essential, verify whether the system actually offers something that standard tools do not. Sometimes it does. Sometimes it is just a branded interface around the same underlying data.

Building a practical Commercial Claims Adjuster Training routine
Dedicate two hours a week to reading actual policy language. Pick one form per week and annotate it thoroughly. The time investment is modest and the return is high because you will start recognizing standard clauses across different carriers. Spend one hour a week reviewing closed files from your department. Focus on files that closed with a variance between the initial reserve and the final settlement. That variance is where the learning lives. Find a senior adjuster who is willing to let you sit in on a complex claim review. You do not need to lead anything. Just observe how they structure their analysis and where they spend their time. Most seniors will talk you through their thinking if you ask specific questions instead of asking for general advice.
The work does not get easier. It gets more efficient. The first two years feel like you are constantly translating between different languages, where one language is insurance policy and the other is human behavior. After that, the translation becomes automatic. The hard part is staying precise enough to catch the details that matter while moving fast enough to keep your file count manageable.