Getting Your Mortgage Quotes Right Without Losing Your Mind
I spent about six months helping a client navigate multiple loan offers last year. She had three different quotes sitting on her desk and honestly, they were confusing the hell out of her. The difference between them wasn't what she expected either. Most people think the rate is the only thing that matters. It is not. When you look at mortgage offers side by side, you are not just comparing numbers on a page. You are comparing how different lenders value risk, how they structure fees, and what they might bury in the fine print. I learned this the hard way when I helped someone find out their "cheaper" loan actually cost them an extra eight thousand dollars over the life of the mortgage because of hidden broker fees and rate lock expiration clauses. The actual process of comparing loan mortgage quote documents involves pulling three to five different offers and laying them out in a spreadsheet. Not the marketing brochures. The official good faith estimates or loan estimates they are required to give you within three business days of applying. These are standardized forms now, which helps. But even standardized forms can hide surprises if you do not know where to look.
What to Actually Look At Beyond the Interest Rate
The interest rate gets all the attention. It should get some attention. But the annual percentage rate tells you more because it includes certain costs. APR combines the rate plus points, some closing costs, and other lender fees into one yearly percentage. That is your real cost of borrowing, not just the sticker rate. Here is what most people miss when they compare loan mortgage quote paperwork. The discount points. One point equals one percent of your loan amount and typically drops your rate by about a quarter point. But whether points make sense depends on how long you plan to stay in the house. If you are going to move in three years, paying points is usually a bad deal. The math does not work out in your favor. You would need to stay in the property for roughly seven to nine years on average for the monthly savings to catch up with what you paid upfront. Another thing nobody talks about enough is the rate lock period. Lenders will offer to lock your rate for thirty days, forty-five days, or sixty days. Longer locks cost more. I once saw a borrower who got caught because her closing got delayed and her lock expired. She had to pay a fee and re-lock at a higher rate. Something like two hundred fifty dollars plus potentially a quarter point increase. That happened because nobody explained the expiration consequences clearly to her.
How I Organize My Comparisons
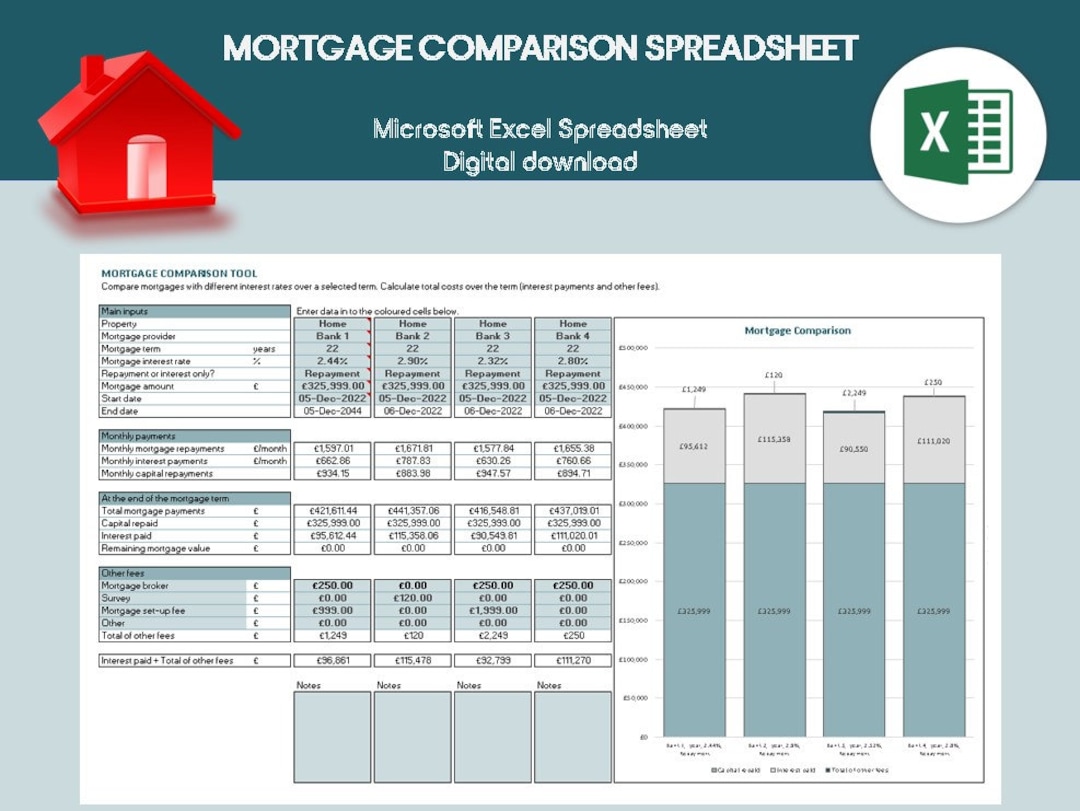
I use a simple table. Columns for each lender with rows for rate, APR, monthly principal and interest, escrow amount, total closing costs, discount points, and any lender credits. Then I calculate the total cost of the loan over different time frames. Thirty years is standard but so is selling in five years. Running both scenarios reveals which deal is actually cheapest for your situation. One specific edge case I run into often involves portfolio loans versus conforming loans. Some smaller banks and credit unions offer portfolio loans they keep on their own books instead of selling to Fannie Mae or Freddie Mac. These can have different qualification standards and sometimes better rates for people with non-standard income situations. But they also tend to have less transparent fee structures. I had a client whose portfolio loan quote looked cheaper initially but carried a prepayment penalty of two percent if she sold within the first five years. That clause was buried in section eight of the term sheet. The workaround for that is straightforward. Ask directly about prepayment penalties before you sign anything. Any legitimate lender should tell you. If they hesitate or deflect, take that as a warning sign. Write down whatever they say and move on.
Get the Full Details
Common Mistakes That Cost People Money
Mistake number one is only shopping two or three lenders. The variation across the market is huge. I have seen differences of over a half percent between the best and worst offers on the same loan profile. On a four hundred thousand dollar loan, that is roughly two hundred dollars a month or twenty-four thousand dollars over thirty years. Shop at least five lenders minimum if you want reasonable coverage of the market. Mistake number two is not verifying that all quotes are for the same loan terms. I see this constantly. Someone compares a thirty-year fixed against a fifteen-year fixed and assumes the thirty-year is better because the rate is lower. Of course the thirty-year rate is lower. The loan terms are completely different. You have to normalize everything to the same product type and down payment amount before making any comparisons meaningful. Mistake number three is ignoring the lender's reputation and processing timeline. A cheap quote means nothing if the lender takes ninety days to close or has a reputation for disappearing after closing. I dealt with a situation where a client picked the lowest quoted rate and the lender stalled for six weeks on document requests. They missed their rate lock deadline twice. The borrower ended up paying more in delays and stress than she would have with a slightly higher rate from a more reliable lender.
When Comparison Shopping Falls Short
There are situations where online comparison tools and even professional advice will not save you. If you have self-employment income that is harder to document, or if your credit score sits right at a pricing tier threshold like six hundred eighty or seven hundred, small adjustments to your documentation can swing your rate by a point or more. In those cases, talking to a single experienced loan officer who understands your specific financial picture beats blindly comparing generic quotes. Also, adjustable-rate mortgages complicate comparison shopping considerably. The initial rate might look attractive but the adjustment caps, margin, and index matter enormously. Two ARM quotes with the same starting rate can have wildly different long-term risk profiles. I once helped a client realize that one lender's ARM had a five percent lifetime cap while another only had two percent. That second option was significantly safer even though the starting numbers looked identical on the surface.
Practical Steps to Actually Execute the Comparison
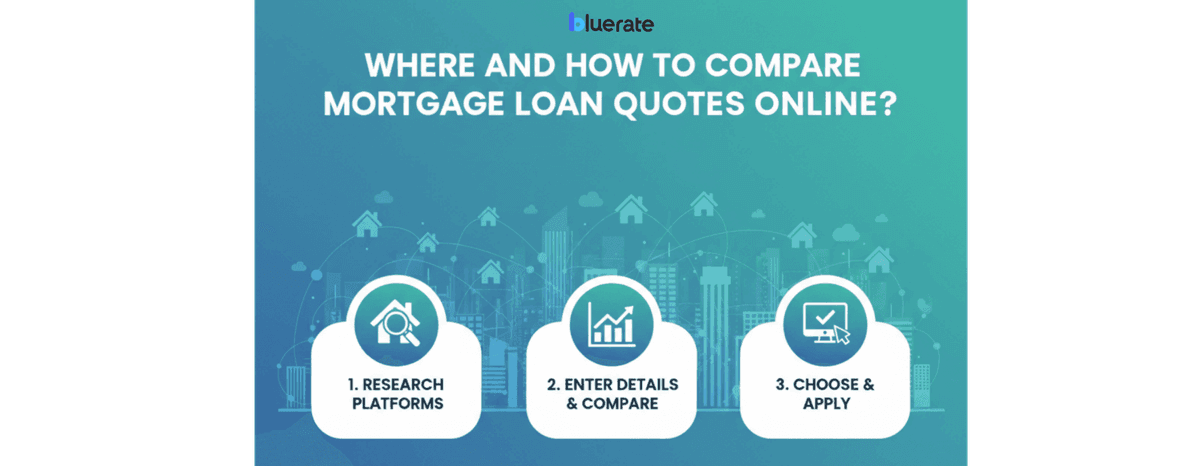
First, gather your financial documents. W-2s, tax returns from the last two years, recent pay stubs, bank statements, and a list of your debts. You need these before you apply anywhere because every lender will ask for them. Second, contact at least five lenders. Mix of national banks, regional banks, and credit unions. Credit unions sometimes offer better terms to members and you would be surprised how many people ignore that option entirely. Third, submit identical information to each lender. Do not change your debt-to-income ratio or credit profile between applications. The quotes need to be apples to apples. If you let one application sit for two weeks and your credit score drops by twenty points during that time, the later quotes will reflect the worse score and your comparison becomes useless.

Fourth, request the loan estimate form within three business days. By law, lenders must provide this standardized disclosure. It should arrive in writing within seventy-two hours of your application. Compare the rate, APR, monthly payment, and closing cost breakdown line by line. Fifth, do not accept the first quote you receive as your final answer. Once you identify the two or three most competitive offers, call those lenders back and ask if they can beat the competing terms. Some lenders will match or improve their offer when they know you are shopping around. I have seen this work repeatedly, though you should not expect miracles. Lenders are not obligated to compete but many will when it is straightforward to do so. The entire process of evaluating multiple offers usually takes about two to three hours spread over a week. That is assuming you have all your documents ready and respond quickly to lender requests. Without that preparation, it can drag on for weeks and you risk rate lock expiration penalties along the way.
What Happens After You Pick a Quote
Picking the quote is only the beginning. Once you accept an offer, the underwriting process starts. This is where things can get messy. Lenders will re-verify your employment, pull your credit a second time, and appraise the property. If your credit drops significantly between quote acceptance and closing, the lender can change the terms or even walk away from the loan. I have seen borrowers lose thousands because they charged a new vehicle to a credit card after locking their rate. The inquiry dropped their score below the lock threshold and the lender revised the terms upward. The bottom line is that a mortgage quote is a conditional offer, not a guarantee. Treat it with the seriousness it deserves. Read every page of the loan estimate, ask questions about anything you do not understand, and do not make any large financial changes during the underwriting period. Keep your accounts stable, avoid new debt, and respond to lender requests within twenty-four hours if possible. Most people only get a mortgage once every seven to ten years. The learning curve is steep and the stakes are high. Taking the time to properly compare loan mortgage quote documents now will pay for itself many times over during the life of the loan. Do not rush it. Do not accept the first thing you see. And do not forget that the cheapest monthly payment is not always the cheapest loan overall.