Passing the Virginia Property and Casualty License Exam Without Losing Your Mind
I've helped a dozen people study for this exam over the years, and the pattern is always the same. They buy a $30 prep book, flip through it once, take a practice test, score 55%, and panic. The reality is that the Va Property And Casualty Practice Exam isn't particularly brutal, but it punishes people who treat it like a multiple-choice trivia game. It's not. Let me walk you through how to actually pass it without wasting three weeks. The Virginia P&C exam is roughly 100 questions split across four main content areas: property insurance, crime and surety, personal and commercial liability, and commercial property. Virginia adds its own state-specific section that's about 10 to 15 questions, covering the Virginia Insurance Code, the Department of Insurance regulations, and the unfair trade practices act as adopted by the Commonwealth. That state section is where most people lose points. They cruise through the general insurance concepts because they already know them from auto or life lines, then get blindsided by something like the exact requirements for the Virginia Insurance Guaranty Association or the timing rules for policy cancellation notices under Virginia law. I had a client once who was a certified public accountant switching into insurance. He nailed every quantifiable question—premium calculations, Coinsurance formula applications, replacement cost versus actual cash value math—and still failed because he couldn't distinguish between Virginia's 10-day advance notice requirement for nonpayment cancellations versus the 20-day requirement for material misrepresentation. He'd memorized the formulas but skipped the regulatory tables. I told him to stop doing practice questions for two days and go read the Virginia insurance regulations cover to cover. He passed on his second try.
How to Structure Your Study Time
Plan on about 40 hours total. Not 10. Not 20. Forty. Most people grossly underestimate the volume of material, especially the property coverage forms. The ISO forms alone—the HO-3, the DP-1, DP-2, DP-3, the BC 00 10 commercial property form—are dense. You need to know the differences between them cold, not just what they cover but what they explicitly exclude. Here's the schedule I give people. Week one: property insurance. All forms, all perils, all exclusions. Week two: liability. CGL, commercial general liability, umbrella/excess liability, BOP basics. Week three: surety and crime. Bonds, fidelity, fraud, ERISA exclusions. Week four: Virginia state law and full practice exams. By the time you hit your fourth or fifth practice test, you should be scoring consistently above 78%. If you're below 70% after three practice tests, something is wrong with your study approach, not the exam.
The Coinsurance Clause Trap
This is the single most asked-about topic and the single most misunderstood. The formula itself is simple: Recovery = (Amount of Insurance Carried / Amount of Insurance Required) × Loss, subject to the policy limit. People memorize that and move on. But the trap is in the definitions. The "amount required" isn't always 80% of the replacement cost. It depends on the specific form. The DP-1 form uses a different coinsurance percentage than the DP-3. The HO-3 doesn't use coinsurance at all for the dwelling portion—that's a dwelling form concept. When a question asks you to calculate a recovery under an HO-2, there is no coinsurance penalty to apply. I've seen candidates divide by a nonexistent coinsurance percentage and then mark the wrong answer because they didn't catch that detail. Another thing that trips people up: the coinsurance clause only applies when the loss is partial, not total. If the building is a total loss and you're underinsured, you get the policy limit, period. No coinsurance calculation. The penalty only kicks in for partial losses. Write that down. Seriously, write it on a piece of paper and put it on your monitor.
Get the Full Details
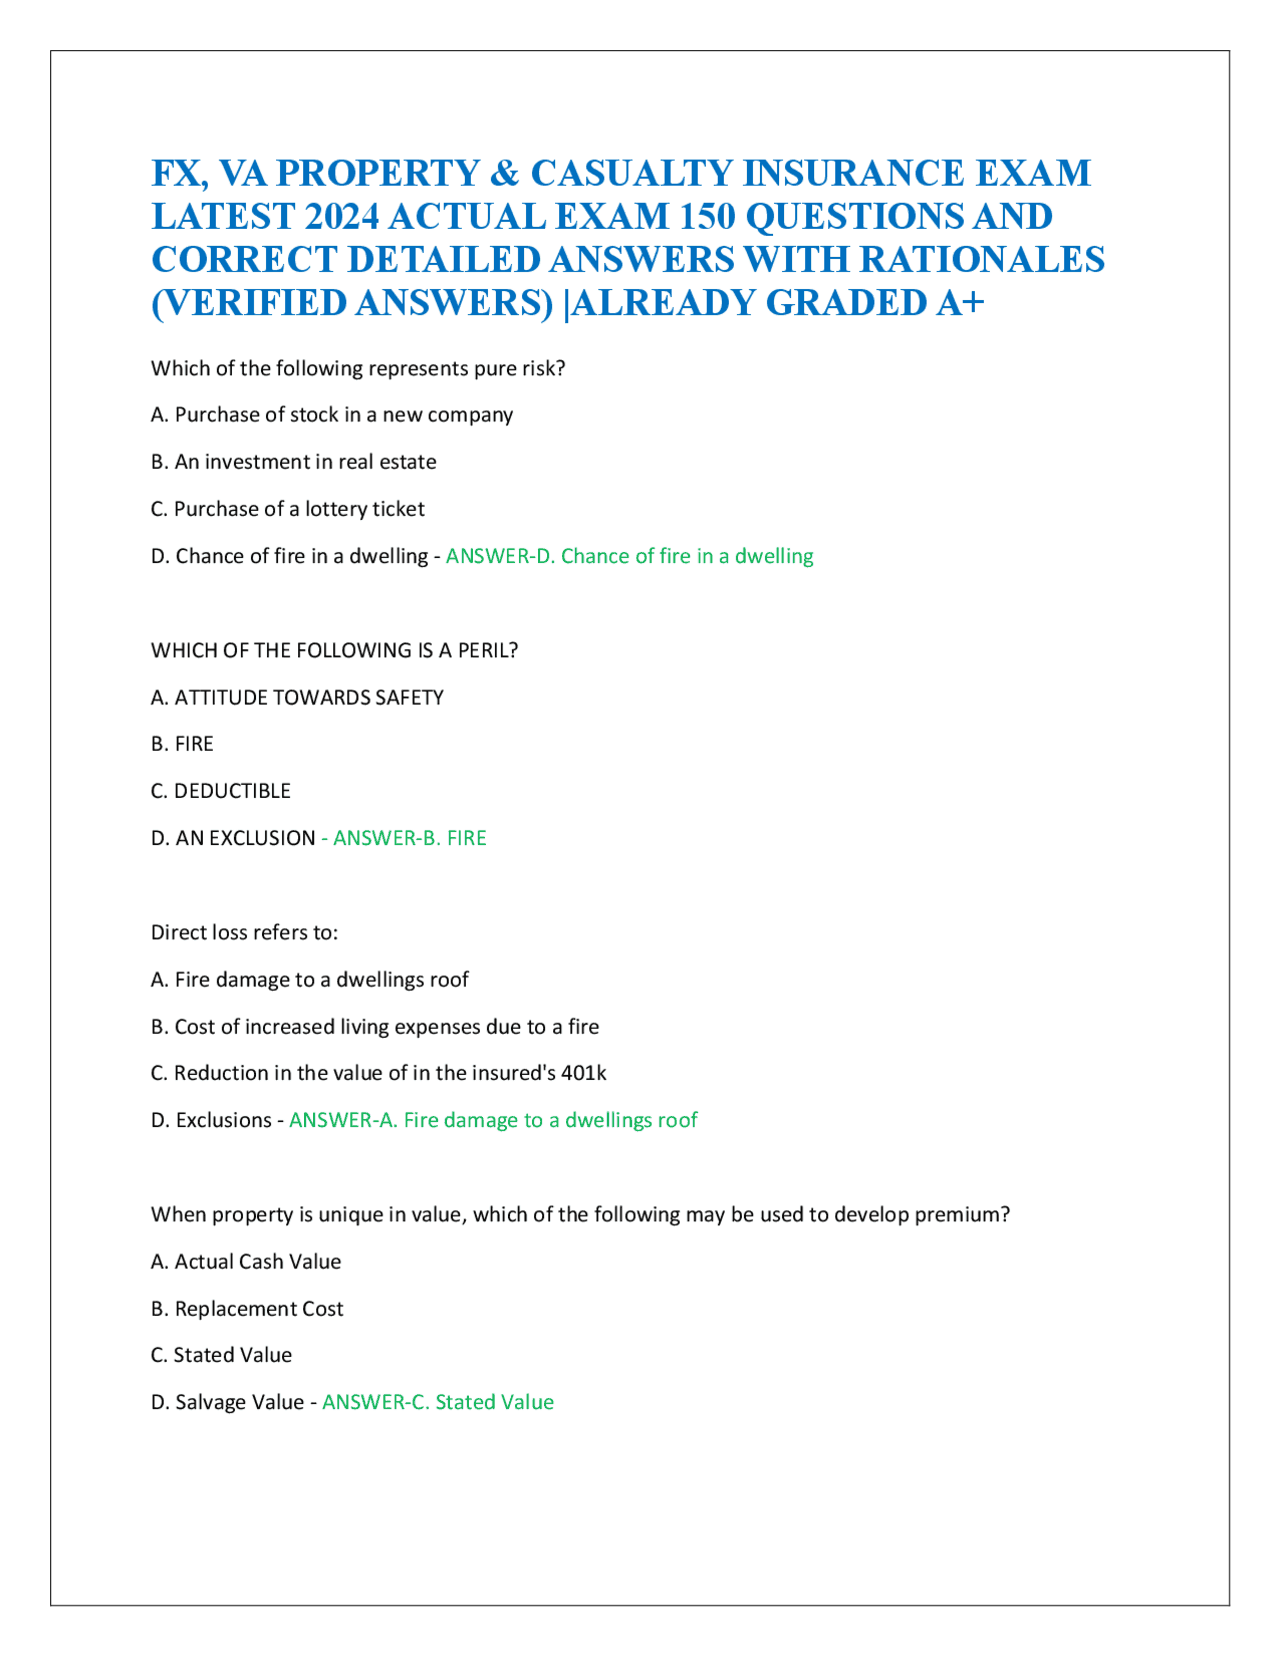
Virginia State-Specific Stuff You Actually Need to Know
Here's what shows up repeatedly on the Virginia section. The Virginia Property and Casualty Insurance Guaranty Association covers insolvent insurers, but there are caps on protected claims—$300,000 per claim for life and health, and I need to be careful here because the P&C caps are different. For property and casualty, the guaranty association protects up to $500,000 per claim, with a sub-cap on certain types of policies. Know those numbers. The state also requires a minimum of 10 days written notice before cancelling a policy for nonpayment of premium. If you cancel for cause other than nonpayment, that's 20 days. These distinctions show up verbatim on the exam. The Virginia Insurance Department's URL for consumer complaints is sometimes a answer choice. It's dos.virginia.gov. Not always tested, but if they ask where a consumer files a complaint about an insurer licensed in Virginia, that's the answer. Also know that Virginia operates under a modified comparative fault system for liability claims—plaintiffs can recover as long as their fault is 50% or less, not 51%. That's a tort concept but it comes up in the liability section of the exam.
Practical Exam Strategy
Take the exam at a Pearson VUE center. Don't take it online proctored unless you have a legitimate reason. The test center environment is controlled, the break between sections is real, and you won't lose focus because your dog walked into frame. Schedule the exam after you've taken at least five practice tests and scored above 75% on four of them. That's your readiness threshold. Below that, you're gambling. When you're in the seat, flag questions you're unsure about and move on. The exam doesn't penalize for guessing, so never leave a blank. Answer every single question. If you're down to the last five and your stomach is doing flips, go back and pick the longest answer for any remaining flagged questions. Not a rule of law, just something that's worked for people I know over the years.
Where to Find Study Materials
The official exam outline is available on the Virginia Department of Insurance website. Download it and use it as your checklist. Everything not on that outline you can safely skip. Kaplan and Prepscholar both offer solid study bundles. Kaplan's book is thicker but more comprehensive. Prepscholar's practice exams are closer to the actual question style. Use both. The free practice questions on the DFS website are outdated but give you a sense of the format. The real value is in the paid prep courses because their question banks are updated annually. If you're studying on a budget, the Virginia Insurance Code is publicly available and free. Print the relevant sections—Sections 38.2-2000 through 38.2-2200—and read them. That alone covers the state-specific portion adequately. Pair that with one good commercial prep course and you'll clear the passing score without spending more than $150. The exam costs $60 to the state plus whatever your prep provider charges. Register through Pearson VUE once your exam prep is done. You get a confirmation email with your appointment details. Show up 15 minutes early with two forms of ID. One has to be photo ID. Driver's license works fine. If you're taking it as a high school senior through the eligible training program, the fee is waived and you register differently—check with the Virginia Department of Insurance if that applies to you.