What this calculator actually does
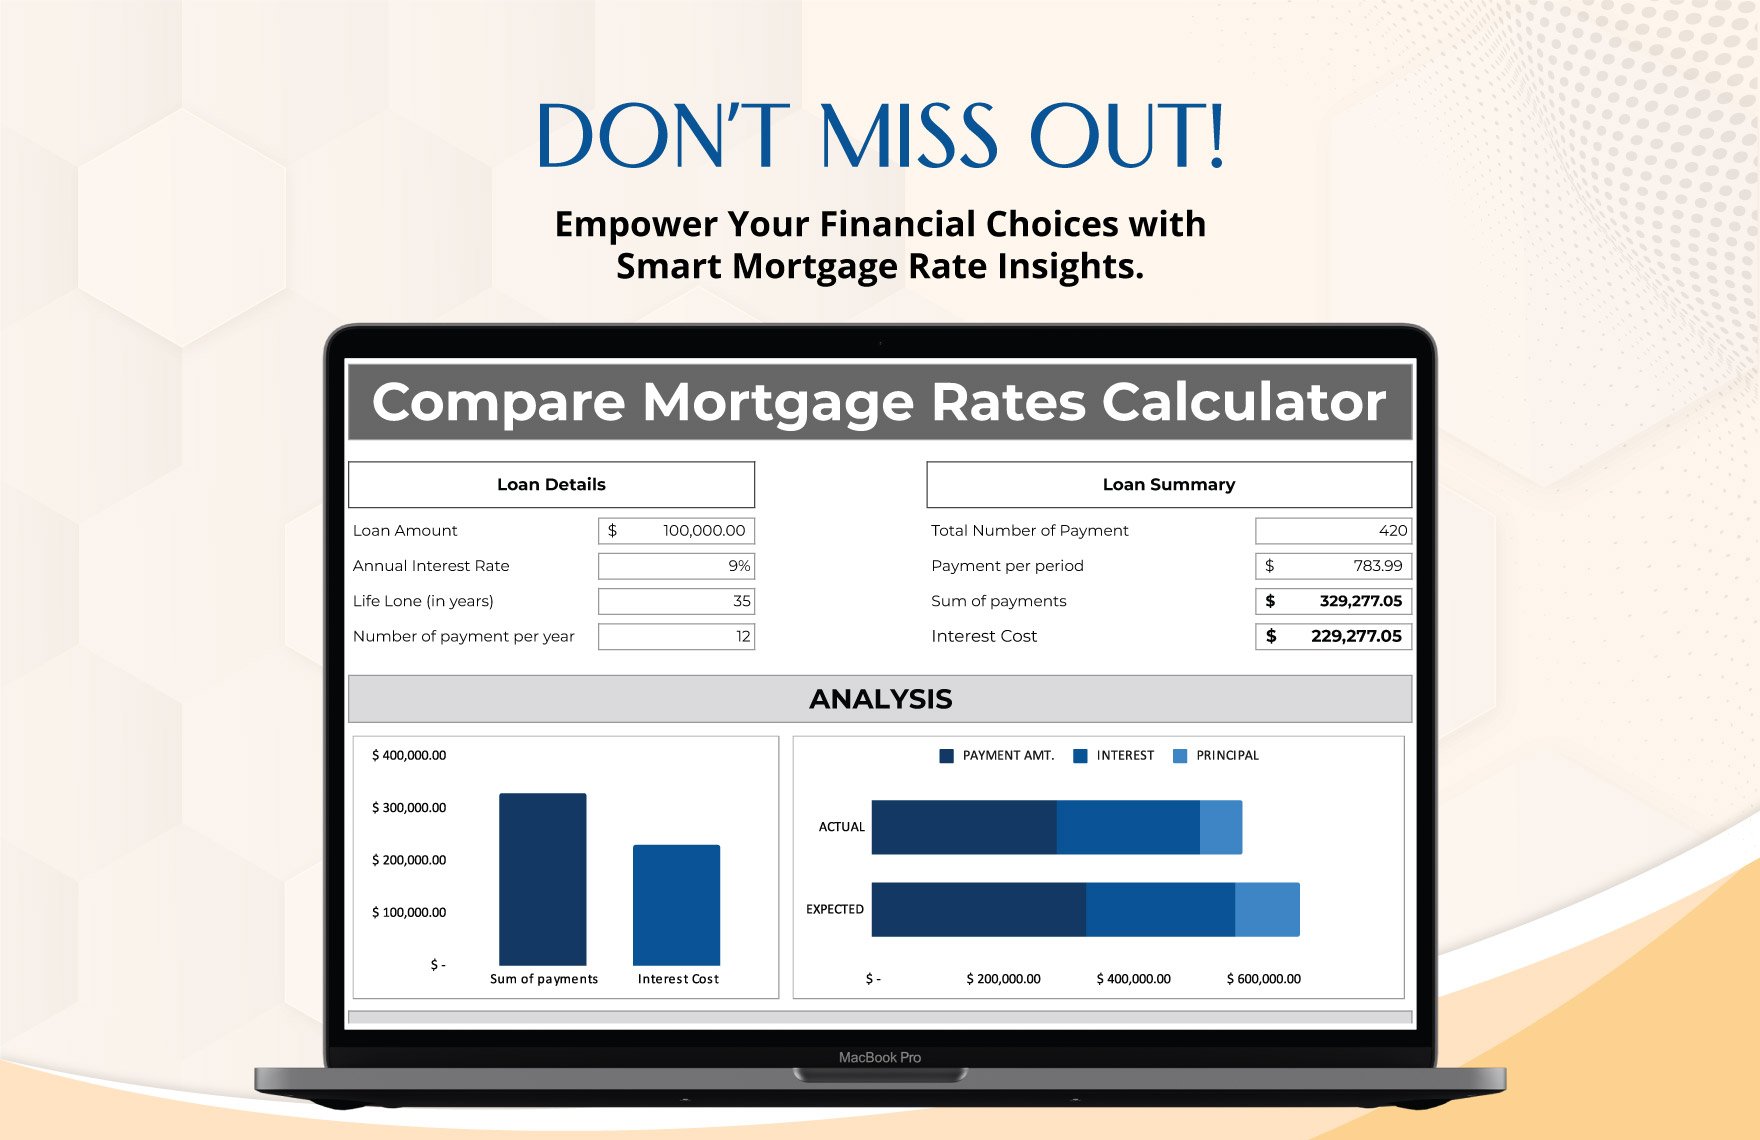
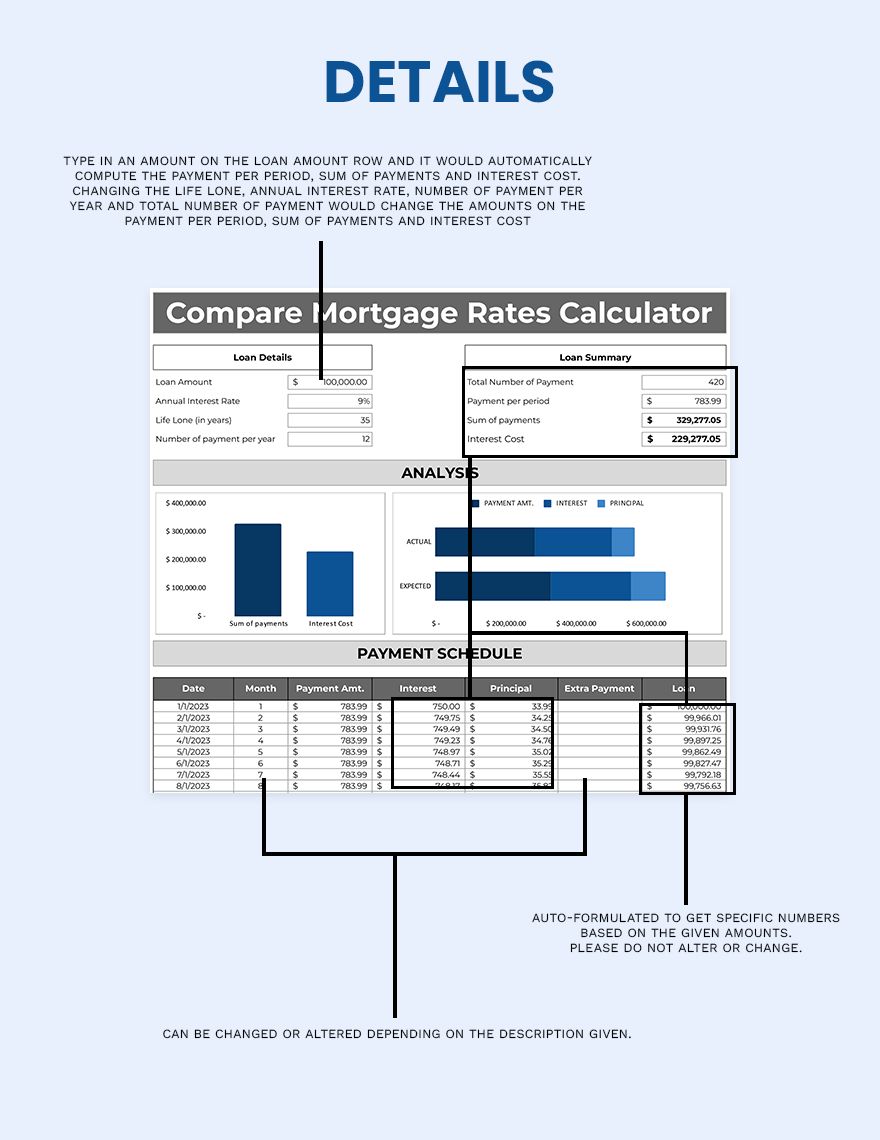
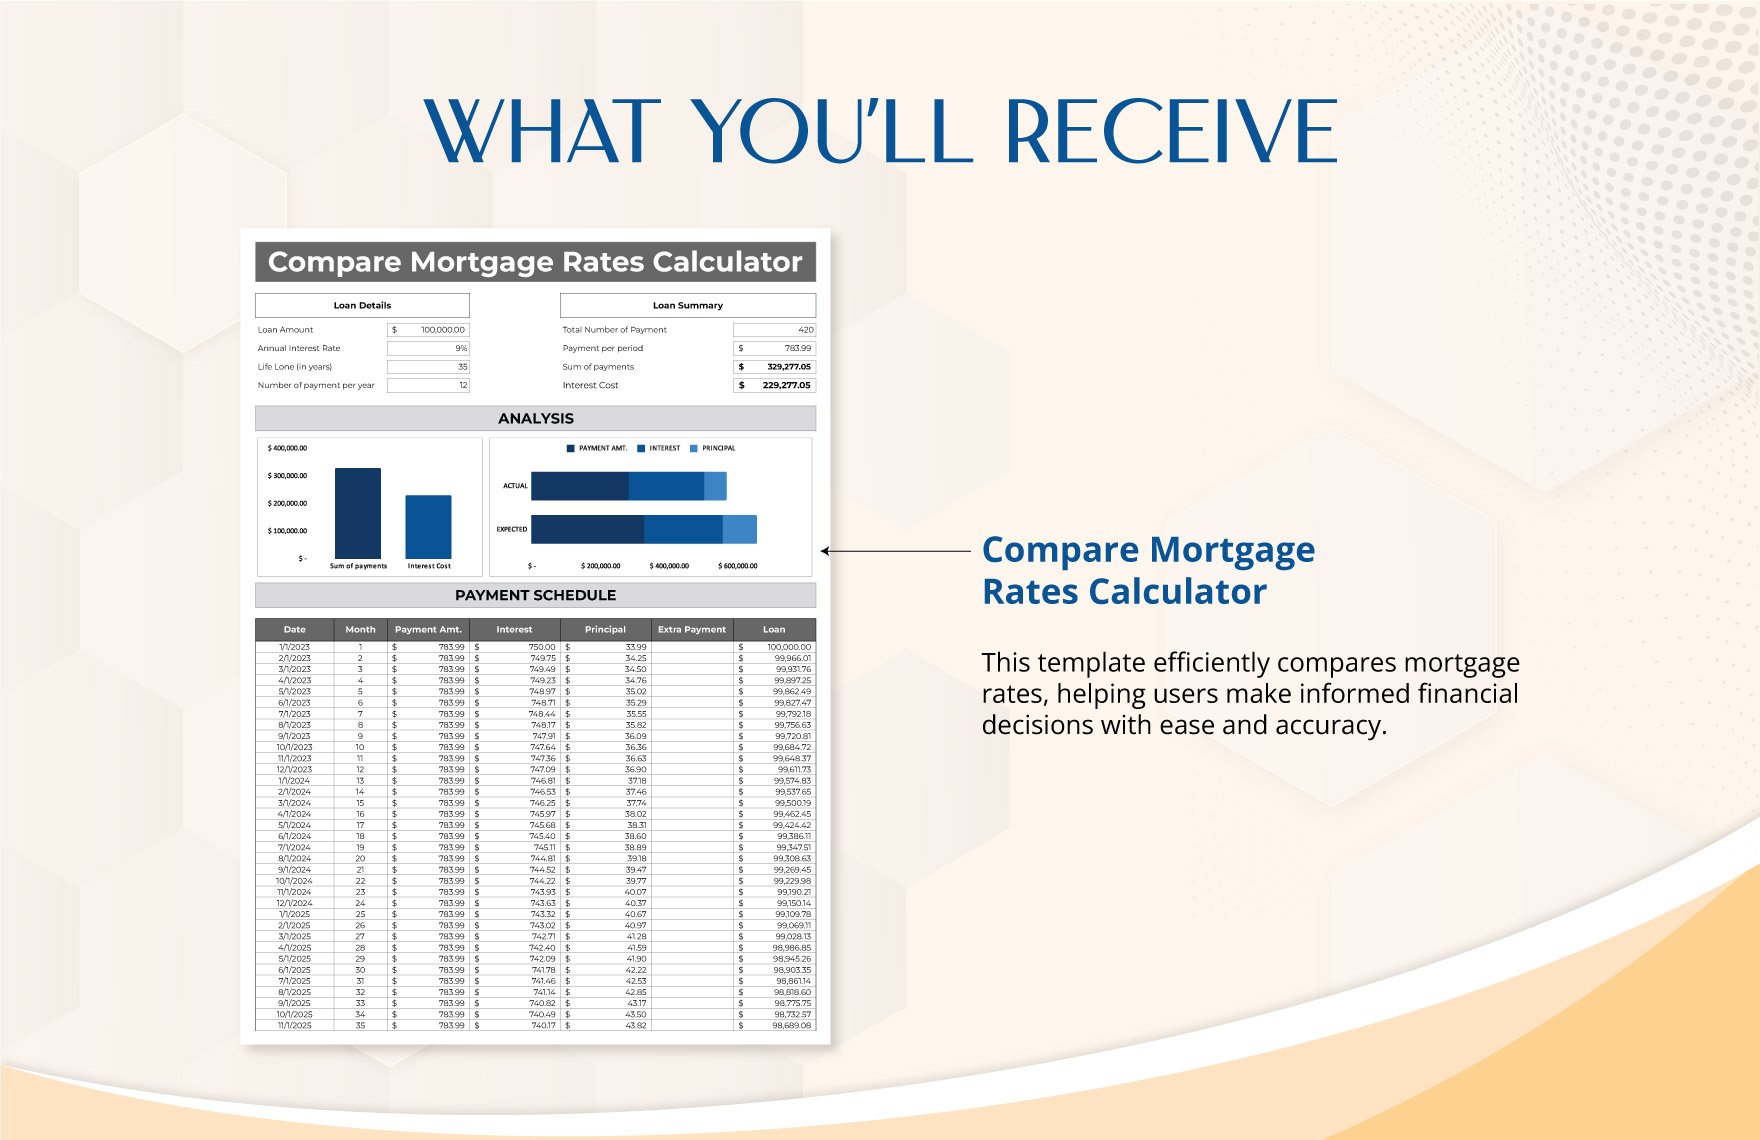
A Comparing Interest Rates Calculator is just a tool that takes multiple loan offers and puts them side by side so you can see which one costs less over time. Most people think lower rate always wins. It doesn't always. Fees, compounding frequency, and loan term can flip the result entirely. I built a simple one after watching too many clients pick the cheapest-looking rate and end up paying thousands more because of hidden points. You start by entering the loan amount for each option. Then plug in the annual percentage rate and the loan term. After that, add in any origination fees or closing costs. The calculator compounds the interest based on how often it's applied—monthly, daily, or annually—and spits out the total cost and monthly payment for each scenario. You compare those numbers directly. The one with the lower total cost is usually the better deal, unless you're cash-constrained and need the smaller monthly payment even if it costs more long-term. I learned the hard way that most free calculators skip the fee comparison. They'll show you rates but ignore origination charges, prepayment penalties, or balloon payments. One client came to me with two refinances: one at 5.2% with zero fees, another at 4.8% with a 2% origination fee on a $300K loan. The raw rate comparison favored the second. After I ran the numbers including the $6,000 fee amortized across the term, the first loan was cheaper by about $1,200 over five years. She almost took the wrong one.
Why rate alone misleads people
APR exists for this exact reason. It folds fees into the effective rate so you get a single number to compare. But here's the thing most people miss—APR assumes you keep the loan for its full term. If you plan to refinance or sell within three years, the APR becomes misleading. Upfront fees don't get spread out, and the math breaks. I've seen borrowers lock into a "lower APR" loan that was actually worse for their timeline because the calculator didn't account for early payoff. Another gotcha is compounding frequency. Two loans can have the same nominal rate but different compounding periods. Daily compounding costs more than monthly compounding at the same stated rate. It sounds counterintuitive but the math checks out. The extra compounding periods add interest on interest more frequently. A 6% loan compounded daily will cost slightly more than a 6% loan compounded monthly over the same term. There's also the debt avalanche versus debt avalanche confusion. People often calculate savings by just subtracting monthly payments. That ignores the total interest paid across the life of the loan. A shorter term with a higher rate might actually cost less total interest than a longer term with a lower rate because you're paying principal faster. Run both scenarios through the calculator and look at total interest, not just the monthly number.
What the tool can't handle
This calculator works fine for straight fixed-rate loans. It falls apart with adjustable rates, interest-only periods, or hybrid structures. If a loan has a teaser rate that resets after two years, the basic comparison breaks. You'd need to model the reset scenario separately. Same thing with balloon mortgages where a large payment sits at the end. The monthly comparison looks attractive until the balloon hits. It also can't factor in tax implications. Mortgage interest deductions vary by country and situation. In the US, for instance, property tax and mortgage interest may be deductible up to certain limits. A higher-rate loan with a larger interest portion in early years might actually save you more after taxes depending on your bracket. The calculator shows gross costs, not net costs after tax adjustments. If you're comparing investment returns rather than loan costs, this tool isn't built for that either. The logic assumes you're paying interest, not earning it. Positive scenarios like savings account comparisons or bond yield analysis need a different approach entirely. I usually switch to a separate compound interest calculator for those cases.
Get the Full Details
Practical tips that matter
Always enter the exact loan amount including any financed fees. Some lenders roll closing costs into the principal. If you do that, your loan balance is higher than the purchase price or refinance amount, and your interest compounds on more money. Entering just the base amount gives you a falsely optimistic comparison. Run the numbers for at least three scenarios: your intended stay duration, a medium-term scenario, and the full loan term. That way you can see how sensitive the comparison is to payoff timing. If the cheaper option only wins at full term but costs more if you move in three years, you have a real decision to make instead of just picking the lowest rate. I've found that saving your calculations as a spreadsheet rather than relying solely on an online tool gives you more control. You can tweak assumptions, adjust for your specific situation, and go back later if rates change. Online calculators reset or disappear. A spreadsheet stays yours.
The tool itself is available through most financial calculator websites, but I'd recommend building your own version or using an open-source spreadsheet template. That way you understand exactly what's being calculated and nothing gets hidden behind a button click. The formula is straightforward: total cost equals monthly payment times number of payments minus principal, adjusted for when fees are paid and how interest compounds. Once you see that structure, you stop trusting opaque results blindly.