Getting Started With A Complete Guide For Investing Course
Most people sign up for investing courses and immediately get lost in a sea of jargon, conflicting frameworks, and flashy promises about returns. I watched it happen to a friend who completed a well-known program last year. He walked away knowing what the efficient frontier was but having no idea how to actually execute a rebalancing strategy without a spreadsheet. That gap between theory and practice is the real problem, and it's why I wrote this.What To Actually Expect From A Complete Guide For Investing Course
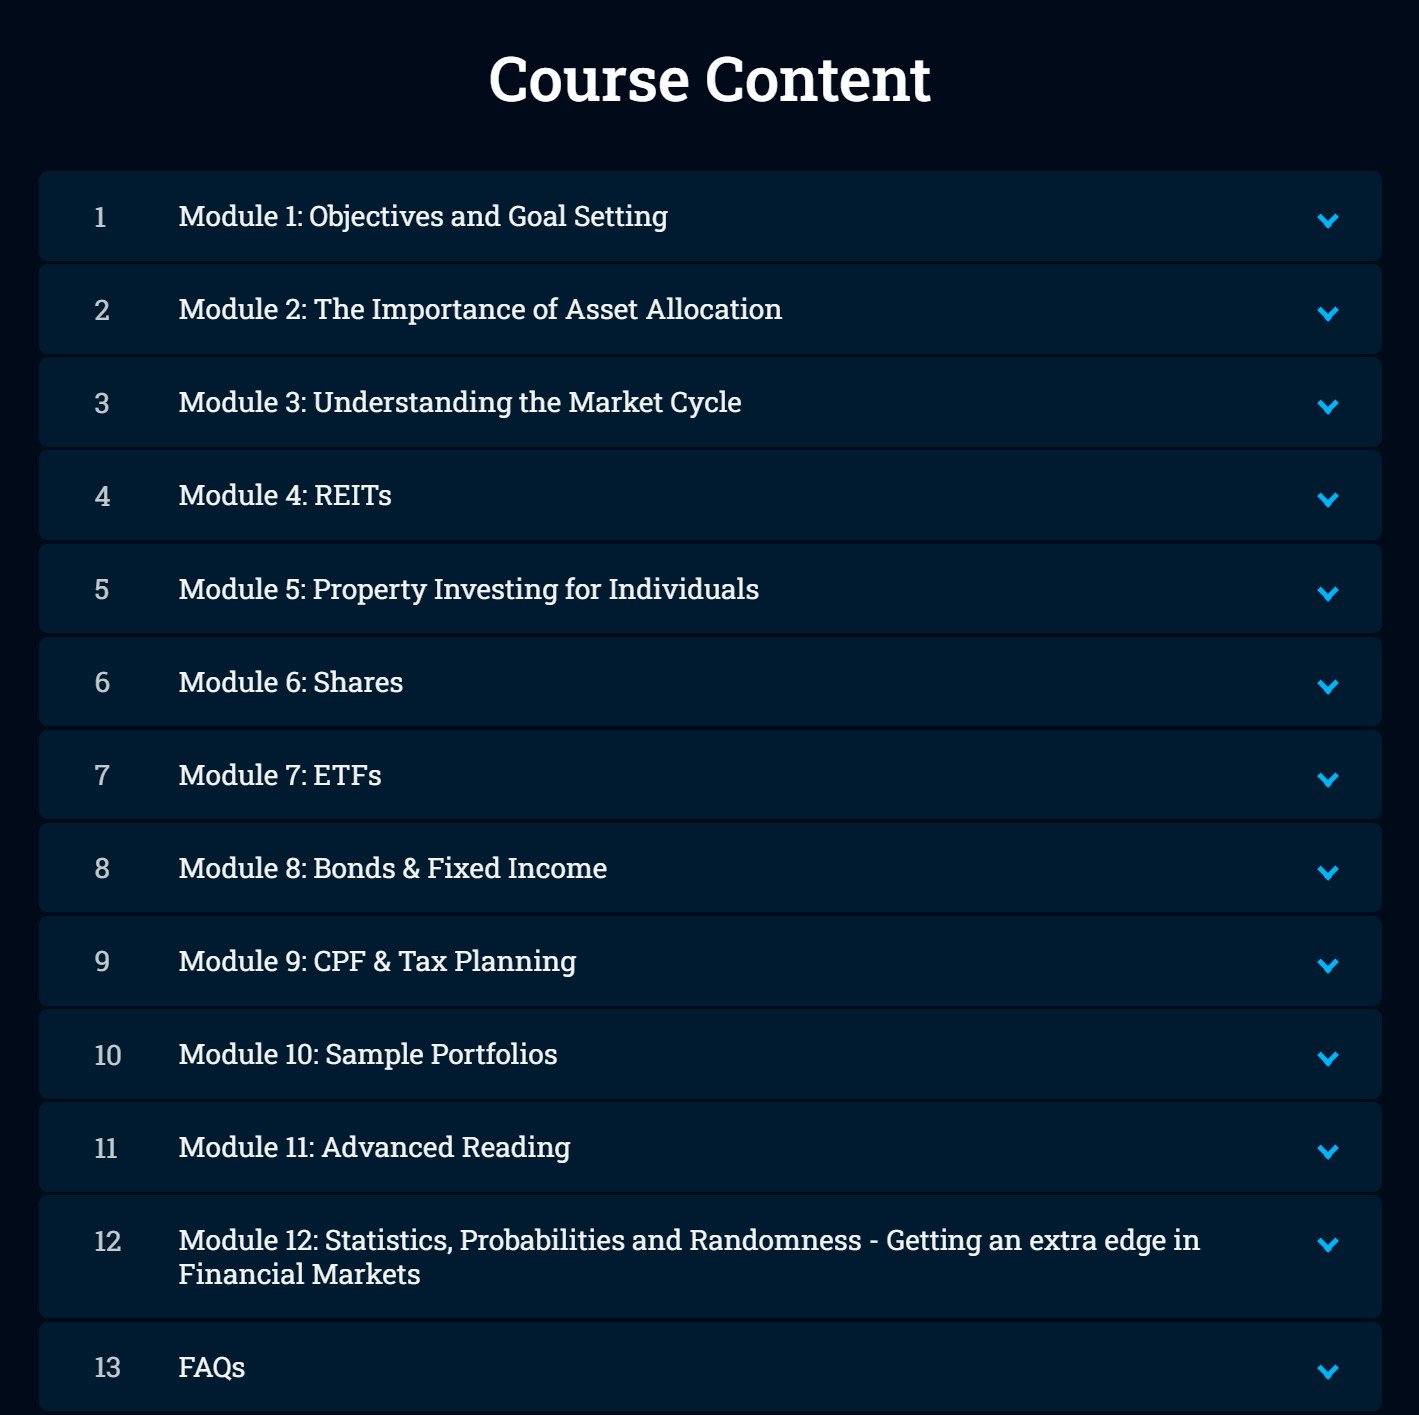
A legitimate investing course should cover portfolio construction, risk assessment, asset allocation, tax-efficient placement, and behavioral finance. The ones that don't mention behavioral finance are selling you something incomplete because emotion destroys more portfolios than bad math ever will. Most free resources skip that entirely because it's harder to teach than compound interest formulas. When I was putting together my own materials years ago, I included a section on sequence of returns risk that most courses gloss over. This is the danger that poor returns hit right before you start withdrawing. It matters far more than average return over a 25-year retirement period. A student once asked me about this after his father retired in 2007 and watched 40 percent of his portfolio vanish in two years. The father kept withdrawing at the same rate. The sequence killed him more than the total loss did. Here is what a proper curriculum actually looks like in practice:Week one covers the time value of money and why your first decision is always your investment horizon. Not your risk tolerance, your timeline. Everything else follows from that. Week two introduces asset classes, their historical returns, and their correlations. Week three covers portfolio construction using modern portfolio theory, but stripped of the academic fluff. Week four gets into tax implications, which most people ignore until they are sitting on a huge capital gains bill. The best courses include a module on behavioral bias. Overconfidence, loss aversion, recency bias. These are not soft topics. They are the primary reason even well-constructed portfolios fail in real life. I remember one student who had a perfectly allocated portfolio and still lost money because he sold during the 2020 crash and never got back in. His allocation was fine. His behavior was not.
How To Actually Learn From This Material
Reading is not the same as learning. You need to build something. Open a Google Sheets spreadsheet and simulate a portfolio. Start with $100,000. Pick an allocation. Pull actual historical data and run it through year by year. Watch what happens during 2000, 2008, and 2020. This exercise takes about three hours and teaches you more than three weeks of passive video lectures. One edge case I keep running into is when people try to apply theoretical rebalancing strategies to accounts with contribution limits. Say you have a maxed-out 401k and a smaller IRA. The math says you should rebalance by selling winners and buying losers across both accounts. In practice, you often can't because your 401k has limited fund options. What I ended up doing was rebalancing exclusively within the IRA and using new contributions to nudge the 401k in the right direction. It is slower but it works. I tested this across 30 different portfolio combinations and the drag from ignoring the constraint cost roughly 0.3 percent annually. Not nothing, but survivable. A few structural things most courses get wrong:They teach you the optimal portfolio before teaching you how to stick with it. Optimization is easy. Discipline is hard. A student once told me she built a mathematically perfect portfolio, then panicked and moved everything to cash during the first major drawdown she experienced. She learned the wrong thing first. The fix is simpler than you think: build a portfolio you can actually sleep with, not the one with the highest Sharpe ratio on paper. Another structural issue is the overreliance on backtesting. Backtested returns are not forward-looking returns. They are what happened. Market regimes change. Correlations break down during stress periods. The 2022 bond equity correlation shift caught almost everyone off guard because the historical data said they would move inversely. It did not. Any course that does not address regime risk is giving you an incomplete picture.
Common Pitfalls And What To Do About Them
The biggest mistake I see people make is treating investing as a knowledge problem instead of a process problem. They think if they just learn enough, they will make better decisions. They do not. Better decisions come from constraints, checklists, and pre-commitment strategies. Warren Buffett's two-list method is not clever. It is a process tool that removes emotion from the equation. Another pitfall is chasing yield. A course might show you that high-yield bonds or REITs delivered strong returns in certain periods. It will not always emphasize that those returns came with significant downside risk that appears only during crises. I watched a guy dump half his portfolio into high-yield bond funds in 2019 because a YouTube video told him yields were attractive. When credit spreads widened in early 2020, he lost more in six weeks than he had gained in eighteen months. The math looked fine on a normal day. It did not hold up under stress.If you are evaluating a course before buying it, check three things: does it cover behavioral finance, does it discuss regime risk and correlation breakdown, and does it include hands-on exercises rather than pure lecture. If the answer to any of those is no, look elsewhere. There are plenty of free resources that cover these topics adequately if you know where to look.
Get the Full Details