How Construction Loan Cost Breakdown Worksheet Actually Works
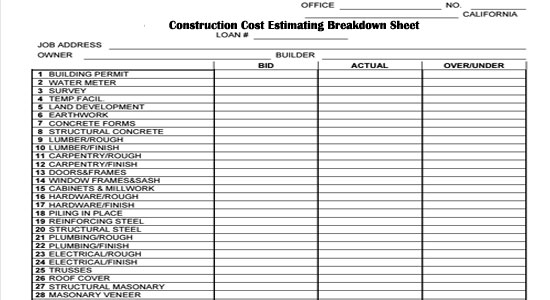
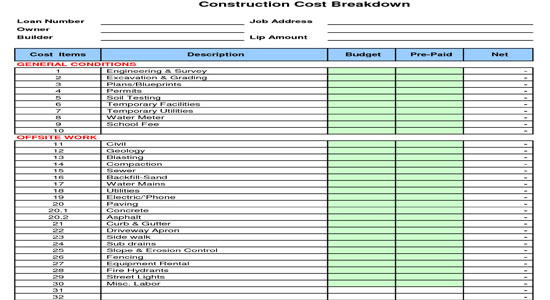
I spend most of my day reconciling construction loan draws, and the moment someone sends me a spreadsheet that doesn't line up with the line items in their commitment letter, it's already a long evening. A Construction Loan Cost Breakdown Worksheet is simply the document that maps every cost in your project budget to the corresponding line item the lender has approved. Without it, you're guessing at draw requests. With it, you're not. The basic structure is straightforward enough. You take the approved construction budget, break it down by trade or phase, assign a dollar amount to each line, and then layer on the lender-specific requirements like retainage, contingency allocations, and draw schedules. The worksheet becomes your single source of truth for what gets paid when. That's it. Nothing fancy. Here's what most people miss. Lenders don't fund line items. They fund percentages of completion. So your worksheet needs to track both the hard cost allocation AND the percentage complete for each category. If you only track dollar amounts, your draw requests will look arbitrary when the underwriter asks why you're requesting 40% of framing costs when the inspection report says framing is 55% complete. I've seen deals slow down for weeks because of that mismatch alone.
Building Your Construction Loan Cost Breakdown Worksheet
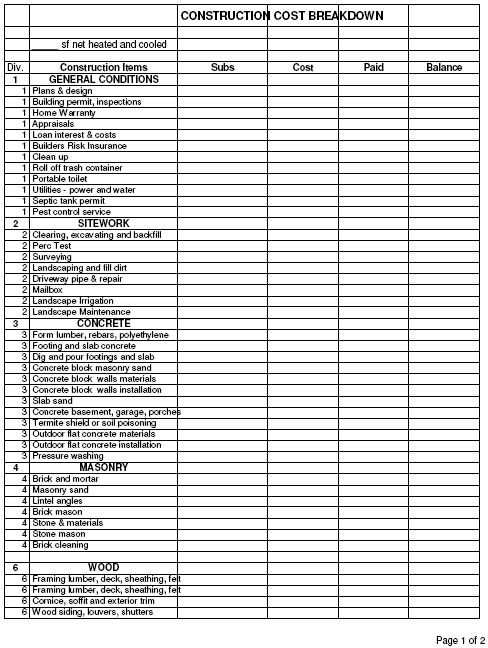
Start with the finalized construction budget from your general contractor. Don't estimate. Don't round. Take the exact line items they provided, preferably in a format that matches or closely mirrors what your lender expects. Some lenders provide a template. Most don't, which means you're building from scratch based on HUD-1 or 1004 standards, depending on the loan program. I use a version that breaks costs into five columns: line item description, approved budget amount, percent complete at each draw, current draw request, and cumulative payments to date. The percent complete column is where most people make mistakes. They estimate visually or by invoice receipts. Neither method works well. Instead, cross-reference the percent complete against the actual inspection reports from each draw. If the inspector signed off on foundation at 100% and framing at 60%, those numbers go in the worksheet before you even calculate the dollar amounts. Retainage is another place where things get messy. Most lenders hold 10% on labor and materials until final completion. Your worksheet needs a separate row or column tracking retainage released versus retainage held. I keep it as a running column at the end that subtracts from the total approved amount per line item. This makes the draw request calculation automatic rather than something you have to explain manually to the lender.
Contingency allocations are where I lost about six months of goodwill on a project in Tulsa back in 2022. The budget had a blanket 5% contingency baked into the general conditions line. The lender required contingency to be itemized separately with its own draw schedule. I'd already submitted three draws without it, and the lender flagged every request for review because the numbers didn't match their expectations. The workaround was simple but painful: I went back and restructured the entire worksheet, pulling contingency out as its own line item with a 25% draw limit per phase. It took me about four hours to rebuild, and the lender accepted the revised version without further questions. The lesson was that contingency isn't a bucket. It's a scheduled draw category with defined thresholds.
Get the Full Details
Common Pitfalls That Wreck Draw Schedules
The biggest issue I see is when contractors bill for materials that haven't been delivered to the job site. Lenders require on-site delivery before those costs qualify for a draw. Your worksheet should flag materials ordered but not yet delivered. I add a sub-row under each major line item that separates delivered costs from committed-only costs. That way, when you're calculating the draw request, you're only including what's actually on site plus the percentage-complete value of work performed. Another problem is double-counting work across draw periods. If you request payment for electrical rough-in during draw three and then include it again in draw four because the invoice wasn't marked as paid, you've now requested funds twice for the same work. I track each line item with a status column: not started, in progress, complete and billed, or complete and paid. This makes it impossible to accidentally request the same dollars twice. Lender-specific requirements will kill a worksheet faster than anything else. Some lenders want costs grouped by CSI divisions. Others want them grouped by project phase. A few want both. I've worked with lenders who require each trade to be broken out separately, and others who lump all subcontractor costs into a single line. The trick is to build your initial worksheet with enough granularity that you can roll it up or break it down depending on what the lender asks for. It takes about ten extra minutes upfront and saves you from rebuilding the whole thing mid-process.
When This Approach Falls Apart
A Construction Loan Cost Breakdown Worksheet is not a universal fix. It assumes your general contractor has provided a detailed enough budget to begin with. If the GC submitted a lump-sum contract without line-item breakdowns, the worksheet becomes a guessing game. You can estimate, but estimations create mismatches with inspections and draw requests, and mismatches create delays. The worksheet also doesn't account for change orders well unless you build in a formal change order tracking section. I add a dedicated section at the bottom of my spreadsheet for approved change orders with their impact on the original budget, the revised budget, and the adjusted draw schedule. Without this, change orders silently erode your contingency and create discrepancies that the lender will notice during the next inspection review. For smaller residential projects where the budget is under $200,000, the full worksheet structure is often overkill. A simplified version with just the core line items, percent complete, and draw amounts works fine. The complexity is worth it for projects above that threshold or for any commercial work where the draw cycle involves multiple stakeholders and tighter audit requirements.
Where to Get a Ready-Made Template
Most lenders provide their own draw request forms, but those forms are usually just payment requests. They don't include the budget mapping that makes the worksheet useful for ongoing tracking. I built my version from scratch over several years by combining elements from Fannie Mae's multifamily guidelines, HUD construction documentation standards, and the practical adjustments that came from actually working with underwriters on closed deals. You can find basic templates online from sources like the National Association of Home Builders or various construction accounting software providers. None of them are perfect out of the box. They tend to oversimplify the retainage calculation and skip the change order tracking section entirely. I recommend starting with one of those templates and adding the columns I described earlier: delivered versus committed costs, status tracking per line item, and a separate contingency draw schedule. If you want my current version, it's available as a downloadable Excel file. It includes pre-formatted tabs for the budget mapping, the draw schedule calculation, and the change order log. The formulas are locked except for the input cells so nothing breaks if you're editing on a shared drive. Download it from the link below if that's faster than building from scratch.
The real value of a Construction Loan Cost Breakdown Worksheet isn't in the formatting. It's in the discipline of keeping it updated after every inspection and every draw request. A spreadsheet you update weekly instead of monthly catches problems before they become lender red flags. A spreadsheet you abandon after the first draw is just expensive paperweight.