Understanding the Construction Loan Estimate
A construction loan estimate is a breakdown of the projected costs for building a structure, along with the loan terms that cover those costs. It's not the same as a standard mortgage pre-approval. Construction loans are different because the lender is funding something that doesn't exist yet, which means the estimate has to account for materials, labor, permits, inspections, and a lot of things that go wrong along the way. The document you receive from a lender will look like a standard Loan Estimate under TRID regulations. That means it has the ten-page format with sections on loan terms, projected payments, closing costs, and cash to close. But the numbers inside are where the real work lives. A builder or homeowner needs to understand how those figures connect to the actual construction timeline, not just the financing side of things.
Construction Loan Estimate Example
Here's what a typical one looks like in practice. Say someone is building a single-family home in the $450,000 range. The construction loan estimate would show a loan amount around $360,000, assuming a 80% loan-to-value ratio. The interest rate might sit at 8.75%, which is higher than a standard purchase mortgage because construction lending carries more risk for the bank. The loan term would be twelve to eighteen months, sometimes longer depending on the project scope. Closing costs in that estimate could run $8,000 to $12,000. That includes appraisal, credit report, title insurance, underwriting fees, and origination charges. Some lenders also charge inspection fees that aren't typical in traditional mortgages because they need to verify progress before releasing each draw. Points are another factor. You might see one or two discount points, which means $3,600 to $7,200 upfront just to buy down the rate by a quarter percent or so. The cash to close figure is where people get surprised. It's not just closing costs. The lender will want an initial deposit toward the draws, sometimes $5,000 to $15,000, and you might need to prepay interest for the first month or two. Add in the appraisal gap if the appraised value comes in lower than expected, and the estimate can shift noticeably from what the borrower initially thought they'd need.
How Construction Loan Estimates Actually Work
The estimate isn't a fixed number. It's a projection based on the construction budget and the bids from contractors. Once the loan is funded, the draw schedule takes over. The lender releases money in stages after each phase passes inspection. Foundation gets poured, inspection happens, draw one releases. Framing completes, inspection, draw two. This process continues until the certificate of occupancy comes through. Interest during construction works differently too. Most construction loans are interest-only during the build phase. You pay only the interest on the amount that's been drawn so far, not the full loan amount. That means early monthly payments might be only $2,000 or $3,000, but they'll increase significantly as more money gets released and the balance grows. After construction finishes, the loan typically converts to a standard mortgage, and the payment jumps to principal and interest on the full amount. One thing most people don't catch right away is that the estimate includes contingency reserves. Lenders usually require ten to fifteen percent of the total budget to stay in escrow for unexpected costs. That's not optional in most cases. If your construction budget is $400,000 and you need a $15,000 contingency reserve, that extra money sits in an account and only gets released when approved changes occur. Without that buffer, a single material price spike or weather delay can stall the entire project financially.
Get the Full Details
I ran into this with a client last year. Their estimate showed a $42,000 contingency line item, but the contract with the general contractor didn't explicitly reference it. The lender wanted the contingency drawn from the loan, but the GC had already baked some padding into their bid. When we flagged the overlap, the lender agreed to reduce the contingency reserve to seven percent instead, which freed up about $11,000 that went directly into the borrower's change order fund. That made the difference between finishing on time and having to pause for another round of financing. Always cross-reference the construction budget line items against what the estimate is showing. They should align, but they often don't.
Pitfalls That Show Up in Real Estimates
The biggest issue I see is that people treat the estimate as a final number. It's not. The estimate is based on your construction plans and contractor bids at a specific point in time. Material costs shift. Labor shortages hit. Permit timelines change. The estimate you get in January could be completely wrong by June if lumber prices jump twenty percent between now and then. That's not hypothetical. It happened repeatedly during the supply chain disruptions and it still occurs whenever there's inflation pressure on building materials. Another common trap involves the appraised value. Lenders order a post-construction appraisal to determine the final loan amount, but they also do a valuation upfront when you apply. If that initial appraisal comes in low, your loan estimate will adjust immediately, and your cash to close figure goes up because the gap between the appraised value and your loan request has to be covered out of pocket. I've seen this play out where the borrower ended up bringing an extra $18,000 to the table because the comps the appraiser pulled didn't reflect the custom finishes they'd paid for. Standard appraisals don't capture premium upgrades well, and construction loans are especially vulnerable to that mismatch. Draw schedule mismatches are the third major problem. The estimate lays out when money comes out, but the construction timeline rarely matches perfectly. If drywall isn't done when the draw schedule says it should be, you're either waiting on inspection or paying out of pocket to keep the project moving. Some lenders allow partial draws, but not all of them do. Check the draw schedule language in the estimate carefully before you sign. It should specify whether partial disbursements are possible and what documentation triggers each release.
There's also the issue of interest reserves. Some estimates include an interest reserve built into the loan amount, meaning the lender sets aside a portion of the proceeds to cover payments while you're in construction. Others require you to pay interest monthly from your own funds. The difference matters enormously for cash flow planning. An interest reserve of $12,000 spread across eighteen months might sound manageable, but if you miscalculate the draw timing, you could find yourself short on a particular month's payment even though the reserve exists on paper.
What to Look For When You Get One
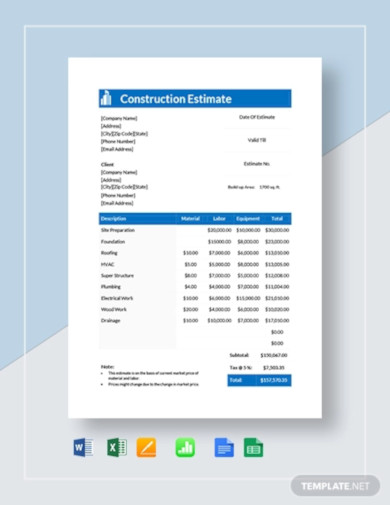
Compare the estimate against your construction budget line by line. Don't rely on the totals. Go into each category and verify that the numbers match what your contractor quoted. If the estimate shows $85,000 for foundation work but your bid says $72,000, ask the lender where the $13,000 difference came from. It might be legitimate engineering or soil test costs, or it might be the lender's padding for risk. Either way, you need to know before you close. Check the rate lock terms. Construction loans often have longer lock periods because the build takes time. A ninety-day rate lock might not cover an eighteen-month construction cycle. Some lenders offer lock extensions, but they cost extra. A typical extension runs $500 to $1,500 per sixty days. Factor that into your total cost picture rather than discovering it three months in when the market moves against you. Look at the fine print around inspections. Each draw requires an inspection, and some lenders charge per inspection. If your project has eight draw phases and the lender charges $350 per inspection, that's $2,800 in costs that might not be obvious on the estimate's closing cost page. It could be buried under "other fees" or listed separately depending on the lender's format. Dig into the breakdown.
The per diem interest calculation deserves attention too. Your first payment won't arrive for maybe thirty to sixty days after closing, depending on when the first draw releases. During that window, you're paying interest on whatever has been disbursed. Make sure the estimate shows this correctly. Some lenders calculate it conservatively, which helps you avoid payment shock, but others assume draws happen faster than they actually do, which understates your early carrying costs.
When the Estimate Doesn't Fit Your Situation
Not every construction project qualifies for a standard construction-to-permanent loan estimate. If you're doing a major renovation on an existing structure rather than new construction, you might be looking at a renovation loan product like an FHA 203(k) or a HomeStyle Reno loan instead. Those have different estimate structures and different draw rules. A renovation loan estimate will include the existing home's appraised value plus the renovation costs, whereas new construction focuses entirely on the building phase. Owner-builder loans are another variation. Some lenders allow you to act as your own general contractor, but the estimate for those loans is stricter. They typically require more documentation, higher credit scores, and sometimes a larger down payment. The contingency reserve often jumps to fifteen or twenty percent because the lender has less oversight on how the money actually flows. If you're considering this route, expect the estimate to look significantly different from a standard builder scenario. The bottom line is that a construction loan estimate is a living document tied to a live project. The numbers shift, the timelines slip, and the assumptions behind every figure deserve scrutiny. Treat it as a starting point for negotiation rather than a finished product, and you'll avoid the kind of surprises that turn manageable projects into financial headaches.