Most CSR Policies Are Just Decor
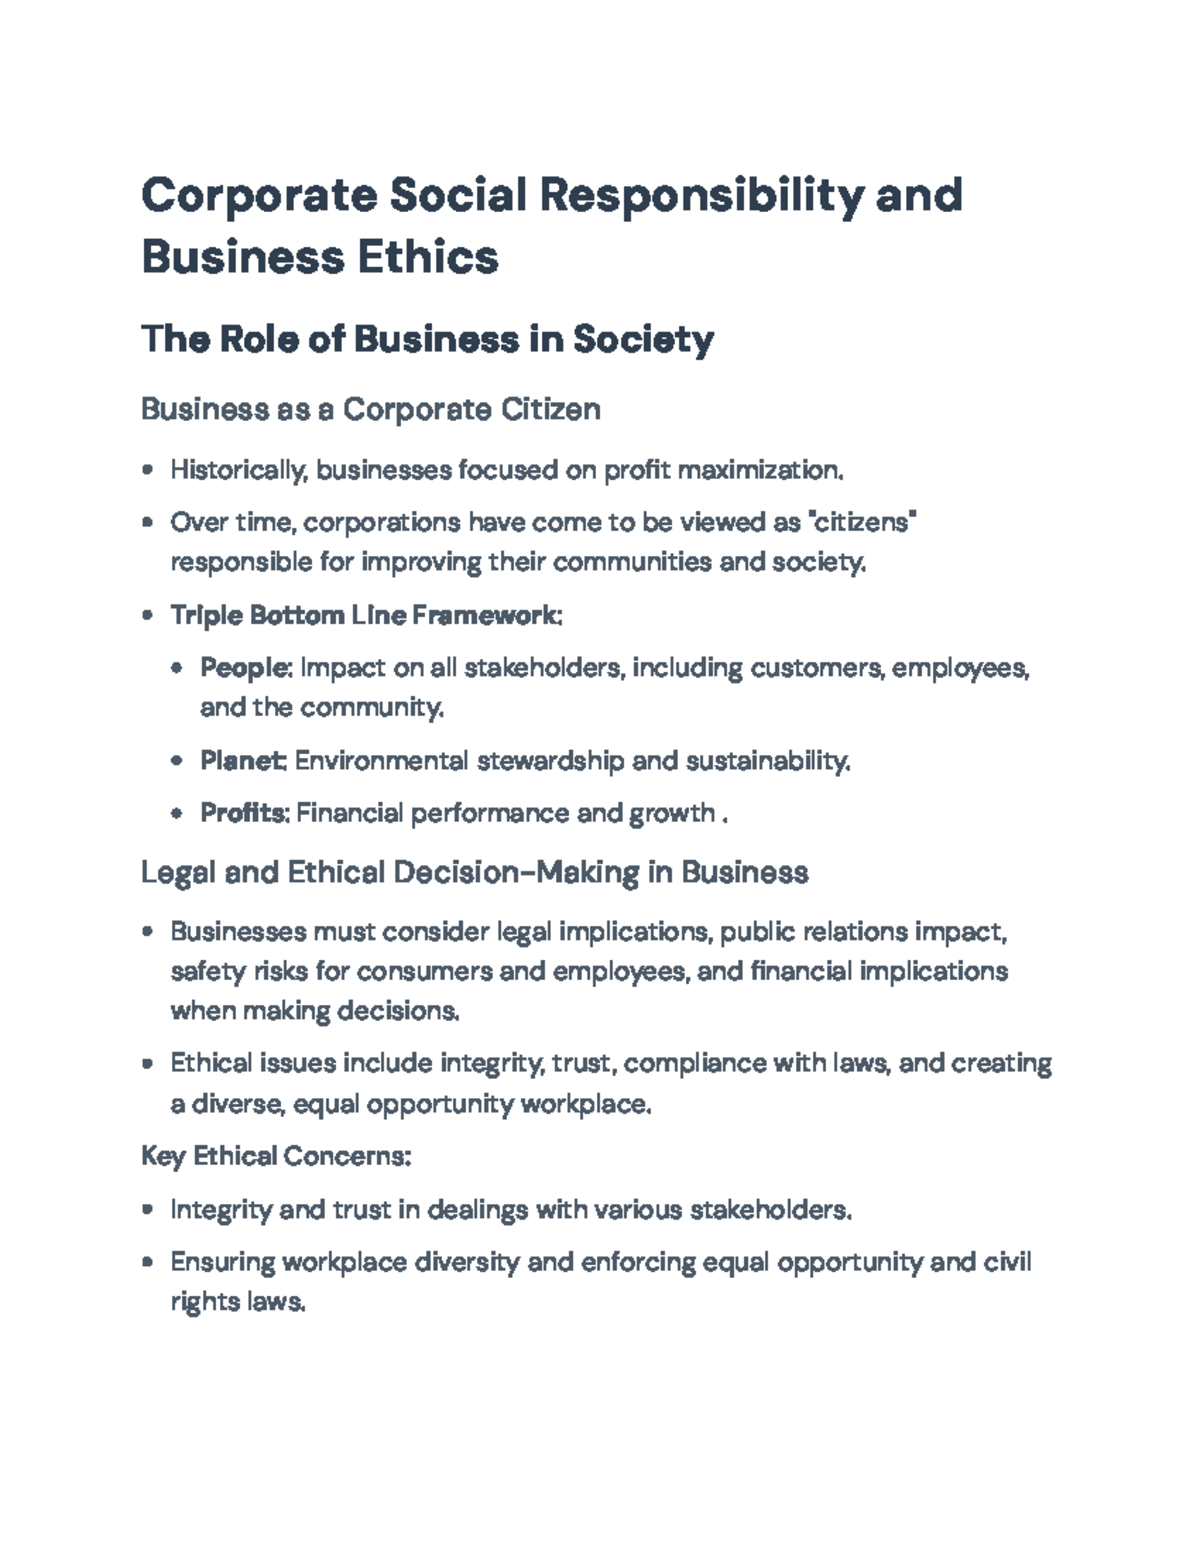
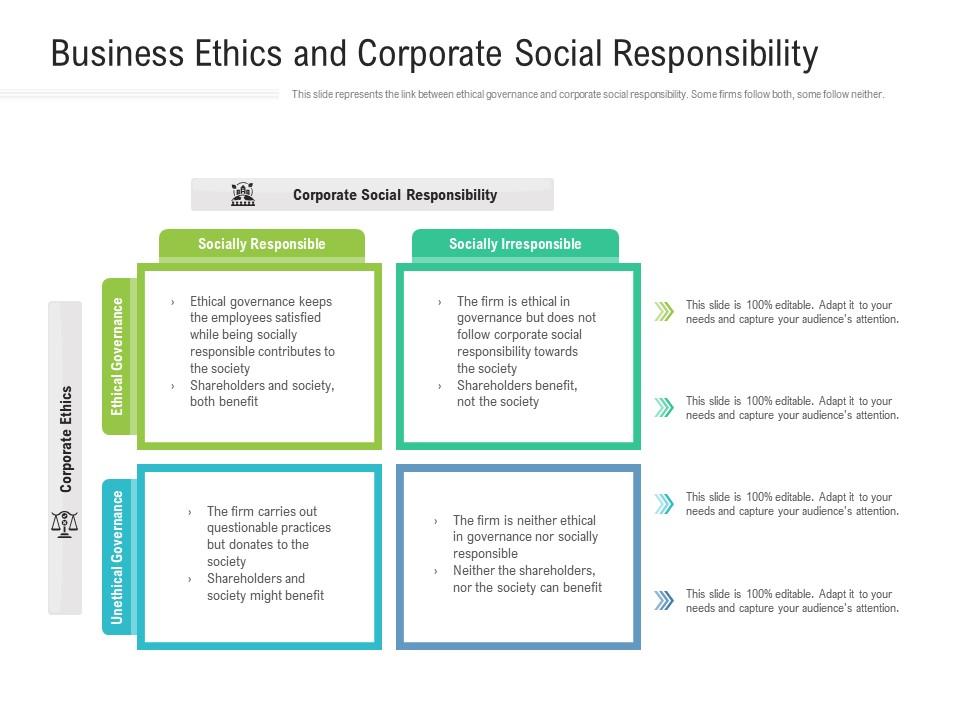
I spent years auditing supplier chains and reviewing ESG reports for mid-market companies. The pattern is always the same. Someone drafts a sustainability mission statement, the marketing team puts it on the website, and then nobody touches it again. Meanwhile the actual work — supply chain tracing, emissions calculations, labor audits — either never happens or is done so poorly that the data would fall apart under any serious scrutiny. That gap between what's written and what's real is where most organizations sit right now. At its core, this concept just means a company takes responsibility for how its operations affect people and the planet, not just how much profit it pulls in. The definition sounds simple because it is. The execution is what makes it miserable. You have to map every link in your value chain, figure out who's actually responsible for violations at each node, and then either fix them or cut the relationship. There's no elegant shortcut through that process. The tricky part nobody talks about is that ethics and CSR are not the same thing. Ethics is about your own behavior — do you pay fair wages, do you hide nothing in your financials, do you treat whistleblowers like humans. CSR is outward-facing — community investment, environmental footprint, charitable giving. Most companies treat CSR as a donation line item and call it a day. That is not sufficient. The modern standard expects both, and increasingly, investors and regulators treat them as inseparable.
How to Actually Build This Without It Being Theater
Start with a materiality assessment. That means sitting down with your actual operations and identifying which social and environmental issues matter most to your business specifically. Not the generic list from some consulting firm. Your list. For a manufacturing company in Southeast Asia, water usage and supplier labor conditions will rank differently than for a software firm in Germany. Do this with people who know the ground reality, not just the boardroom. A proper materiality exercise usually takes four to six weeks and costs between three and eight thousand dollars if you outsource it, or roughly two weeks of internal staff time if you do it yourself. Next, set measurable targets for each material issue. Vague commitments like "we strive to reduce our environmental impact" are worthless. I once saw a company claim they were "committed to carbon neutrality" while their Scope 3 emissions — the ones from their suppliers and product use — were growing twelve percent year over year. Pick specific numbers. Reduce greenhouse gas emissions by forty percent by 2030 against a 2022 baseline. Source one hundred percent of key materials from audited suppliers by Q3 next year. Publish the baseline data publicly so you can be held accountable. Then build reporting infrastructure. GRI, SASB, and the new EU CSRD framework all have overlapping requirements but different audiences. If you operate in Europe, CSRD compliance is now mandatory for large companies and phase-in for medium-sized ones. GRI is the global baseline for voluntary reporting. SASB gives you industry-specific metrics that investors actually use when comparing companies. Map your data needs to at least two of these frameworks so you are not starting from zero every reporting cycle.
The Edge Case That Broke My Team
Here is a specific problem I dealt with that most guides never mention. We were auditing a tier-three supplier — that's a supplier's supplier — for a clothing brand. The facility was certifying its labor practices as compliant under the brand's code of conduct. But we noticed the electricity bill had dropped dramatically in the months leading up to each audit. We dug deeper and found they had shifted overtime work to an unregistered neighboring workshop that had no safety equipment, no proper fire exits, and paid workers cash under the table. The main facility looked perfect on paper during audits. The actual labor conditions had just been outsourced to somewhere invisible. The workaround was brutal but necessary. We stopped relying on self-reported supplier data entirely for that region and switched to anonymous worker interviews conducted by local fixers who knew the area. We also cross-referenced utility records, payroll tax filings, and local health department violations against what suppliers reported. That added roughly forty hours of extra investigation time per supplier site, but it caught three out of five suppliers in that region who were running shadow operations. The brand ended up dropping two of those suppliers and putting the third on a six-month remediation plan with quarterly unannounced audits. It cost them an estimated two hundred thousand dollars in delayed orders and transition costs. They still chose to do it rather than quietly ignore it, which says something about the pressure from institutional investors at the time.
Get the Full Details
Counter-Intuitive Things You Should Know
First, more disclosure is not always better. I have watched companies publish extensive sustainability reports full of impressive language and vague figures, only to get shredded in media investigations because they disclosed so much that the gaps became obvious. Sometimes a short, verifiable report with hard numbers and acknowledged shortcomings is more credible than a hundred pages of glossy content. Third-party assurance matters more than page count. Even limited assurance from a reputable firm adds significantly more credibility than no assurance at all. Second, the biggest ethical risk in CSR is often your own procurement team. When you push suppliers too hard on cost reductions, they cut corners on safety, wages, and environmental controls. I have seen this repeatedly. A purchasing department with aggressive margin targets will create the conditions for CSR violations faster than any other single factor in the organization. Aligning procurement KPIs with ethical sourcing metrics is not optional. It is the single most impactful structural change you can make.
Where This Breaks Down
CSR and business ethics frameworks fail completely in environments where local enforcement is absent or corrupt. You cannot audit your way out of a system where inspectors accept bribes and labor laws are ignored with impunity. In those contexts, the best you can do is build alternative verification channels — worker hotlines, community monitoring, partnerships with local NGOs who have real access. Even then, you will occasionally have to make the decision to leave a market entirely. That is not a failure of the framework. It is the framework working correctly. Another hard limit is small and medium enterprises. The reporting burden of CSRD and similar regulations is crushing for companies with fewer than five hundred employees. They often lack the legal and operational capacity to gather the required data. If you are in that category, focus on the substance rather than the paperwork. Build genuine ethical practices first. The formal reporting will come naturally afterward, and you will have real data to report instead of fabricating something to check a box. There is no point in filing a report that does not reflect your actual operations. It creates liability without any of the benefit. The bottom line is that Corporate Social Responsibility Business Ethics is not a marketing strategy. It is an operational discipline that requires ongoing investment, honest data collection, and the willingness to make decisions that hurt your short-term margins. Most companies do the minimum acceptable version and call it done. The ones that do it properly are the ones that survive when investigations, regulations, and consumer expectations inevitably tighten further.