Running Cost Analysis In Managerial Economics Without Losing Your Mind
The first time I tried to allocate overhead for a mid-sized manufacturing client, I spent three days building a cost model that looked impressive on paper and was completely useless in practice. The spreadsheet had 47 tabs. The numbers didn't add up. The client's actual decisions had nothing to do with the output. I learned fairly quickly that cost analysis isn't about making something complicated and calling it rigorous. It's about making something simple enough that a manager can actually use it before the quarter ends. Cost Analysis In Managerial Economics is the discipline of breaking down expenses so that business decisions can be made with a clear view of what each option truly costs. This means distinguishing between costs that change with output and costs that don't, identifying which past expenditures are irrelevant going forward, and estimating the impact of decisions on future cash flows. That's the textbook definition. The actual work involves a lot more judgment than formulas.
Cost Analysis In Managerial Economics: The Practical Breakdown
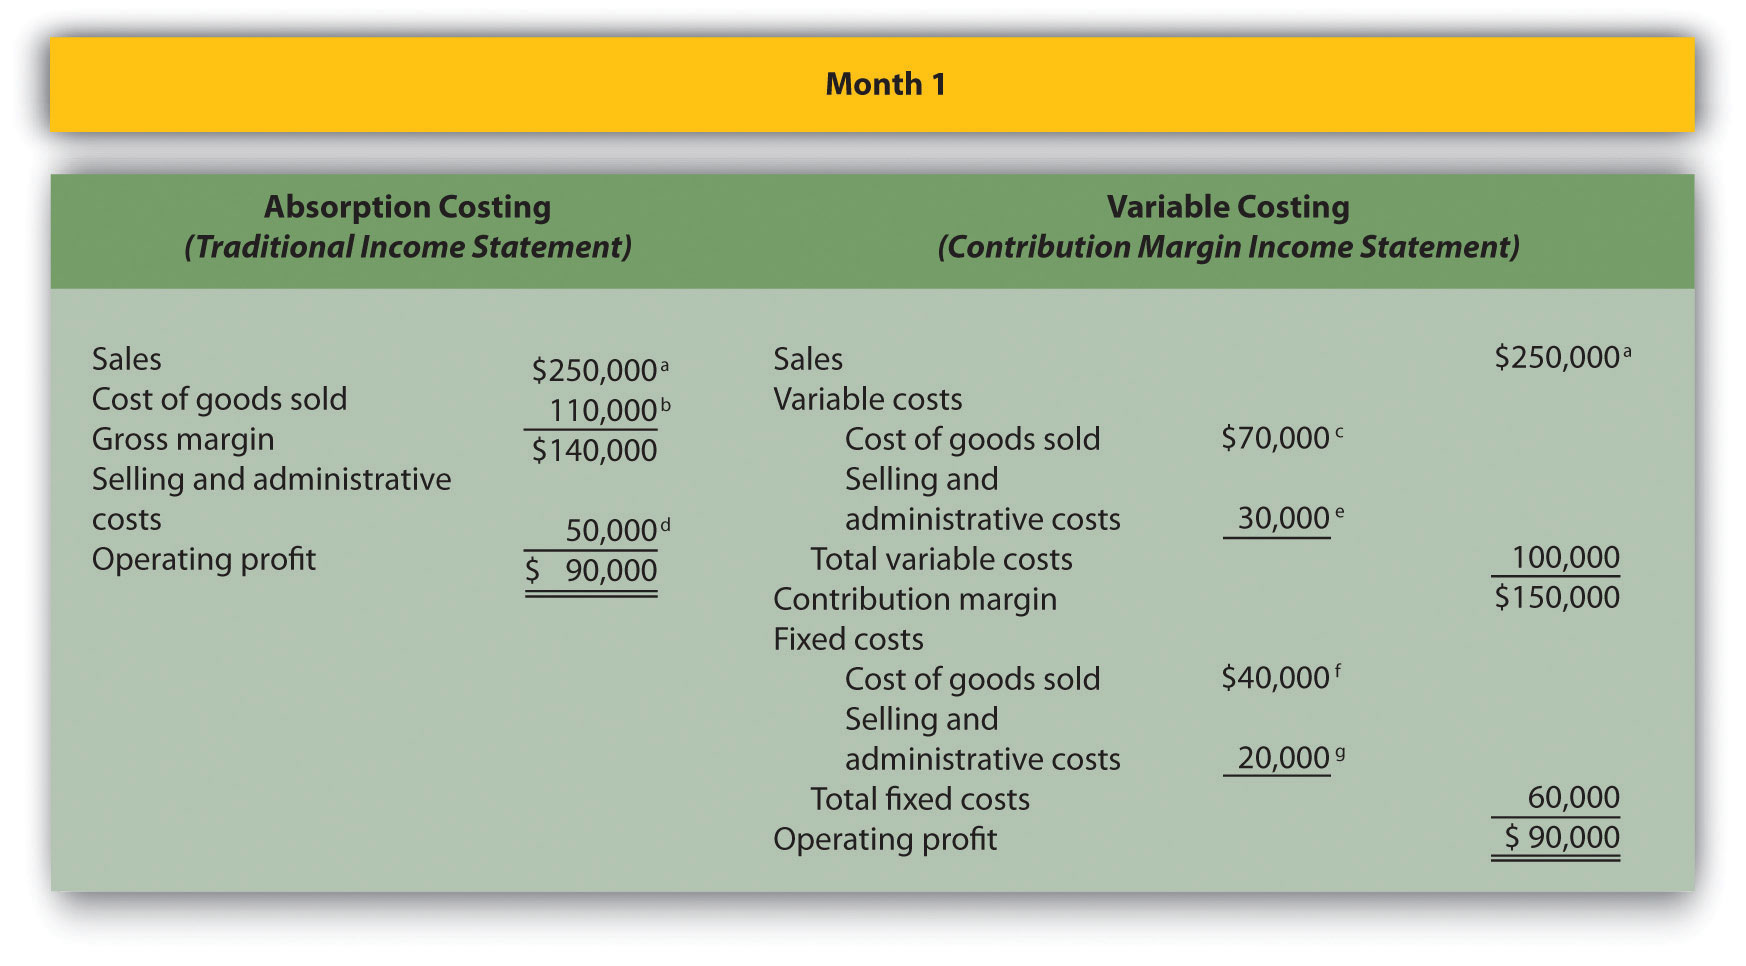
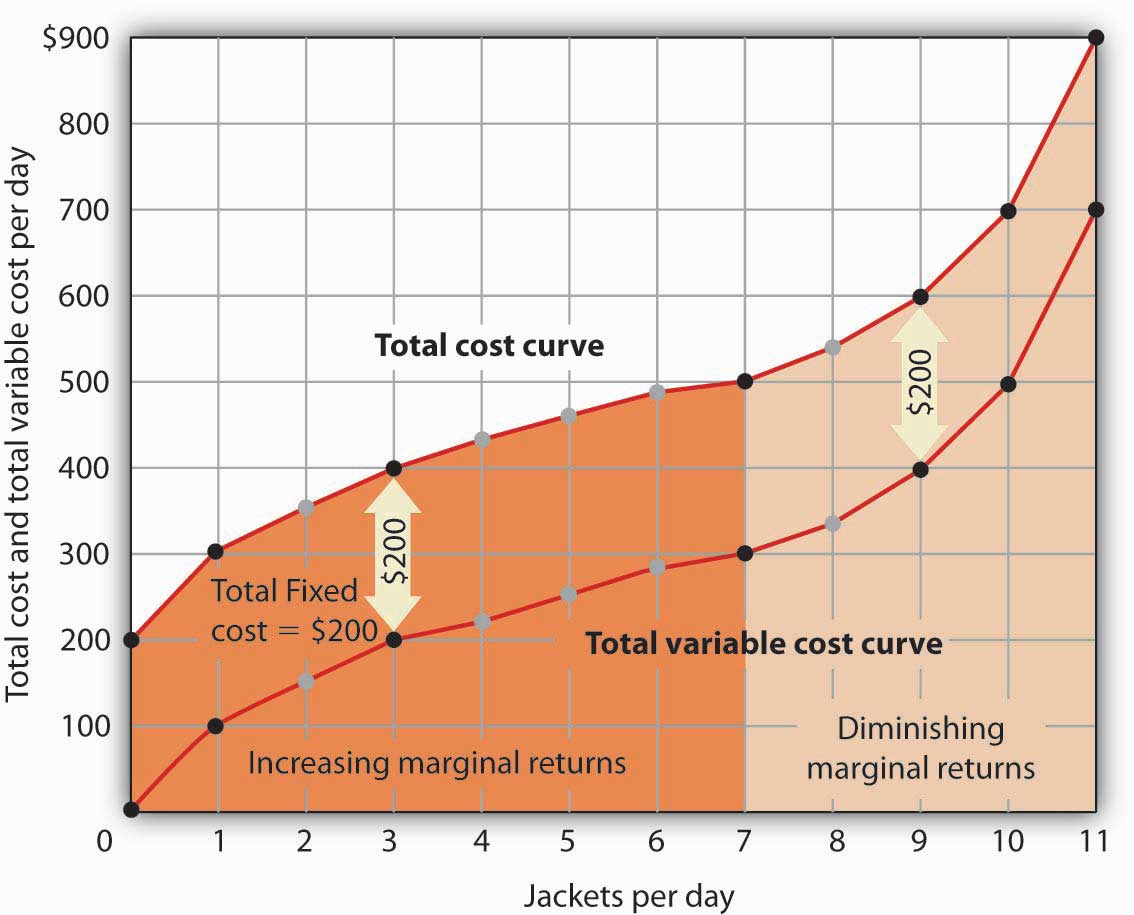
Start with the cost classification map. Fixed costs stay constant within a relevant range regardless of production volume. Variable costs shift in direct proportion to output. Mixed costs contain both elements. Semi-variable costs are the same thing under a different name. Understanding these categories isn't academic exercise. When you misclassify a cost, you misprice a product, misallocate resources, and make decisions that erode margin without anyone noticing until the end of the fiscal year. The high-low method is the fastest way to separate mixed costs when you don't have access to detailed accounting data. Take your highest activity level and your lowest activity level over a defined period. Calculate the variable cost per unit by subtracting total cost at the low point from total cost at the high point, then dividing by the difference in activity units. Once you have the variable rate, plug it back into either data point to solve for the fixed component. This usually takes twenty minutes and gives you a reasonable approximation for short-term planning. It breaks down when your cost structure has nonlinear elements or when the relevant range shifts between your two data points. For more precision, regression analysis provides a stronger foundation. Spreadsheet tools like Excel's LINEST function or the Data Analysis Toolpak can run a least squares regression in under a minute with a properly formatted dataset. The R-squared value tells you how much of the cost variation your activity driver explains. If it's below 0.7, your cost driver isn't the right choice or your data quality needs work. This step alone can save you from building a model on a false assumption.
Marginal cost deserves its own attention. It's the cost of producing one additional unit. In many organizations, managers treat marginal cost as synonymous with average variable cost, which works fine in theory but causes real problems in practice. When you're operating near capacity constraints, the marginal cost of that next unit includes overtime premiums, expedited shipping, machine wear that triggers premature maintenance, and the opportunity cost of displacing a more profitable product from the production line. I've seen companies price bids at what they thought was marginal cost and then lose money on every order because they never accounted for the capacity displacement. Opportunity cost is the other area where theoretical clarity meets practical messiness. It represents the value of the best alternative forgone when a decision is made. The standard textbook example uses resources tied up in inventory. The real-world example involves a manager who kept pushing a product line forward because the team had already invested six months and two million dollars in development. That investment was sunk. The opportunity cost was the engineering capacity those people could have deployed on a different product with a clearer path to revenue. The team couldn't let go of the money already spent. That's the cognitive trap that cost analysis is supposed to help you avoid. Relevant costing filters out everything that doesn't matter for the decision at hand. Sunk costs are irrelevant. Future costs that are identical across alternatives are irrelevant. The trick is identifying what's actually relevant when the situation isn't clean. Should a division keep or drop a product line? You look at avoidable costs versus unavoidable costs, not at allocated common costs that will exist regardless of the decision. Allocated costs are the most dangerous element in a relevant cost analysis because they create the illusion of relevance. They make an otherwise unprofitable product appear profitable simply because it's absorbing a slice of overhead that would have been absorbed by other products anyway.
Get the Full Details
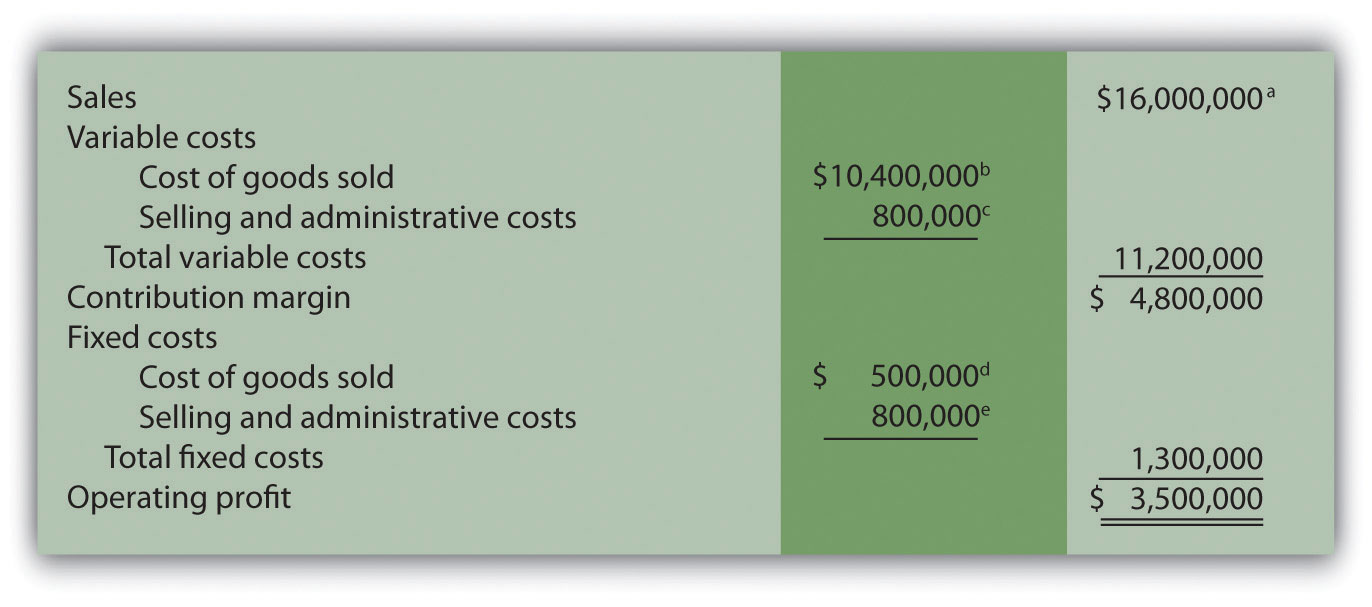
Cost-volume-profit analysis brings these pieces together into a single framework. Contribution margin equals revenue minus variable costs. The break-even point is fixed costs divided by contribution margin per unit. From there you can calculate the margin of safety and target profit volumes. The formula is straightforward. The assumptions underneath it are where things get fragile. CVP assumes a linear relationship between cost and volume within the relevant range, which rarely holds exactly in practice. It treats price as constant, which ignores competitive pressure and discounting. It works well enough for quick directional analysis but becomes misleading when you're making multi-year capacity decisions based on it. Life cycle costing expands the perspective beyond the production phase. It includes research and development, design, production, distribution, marketing, customer support, and eventual disposal or decommissioning. For product lines with long horizons, this matters enormously. A product that looks profitable at the manufacturing stage might destroy value once you account for warranty claims, support overhead, and regulatory compliance costs in years three and four. I once reviewed a project where the engineering team optimized for unit production cost and ignored the fact that the chosen materials would increase field failure rates by an amount that wiped out the entire gross margin advantage over a five-year period. The life cycle view would have caught that before the design was locked in. Activity-based costing is another tool that people either love or hate. The theory is sound: assign overhead to products based on the activities that drive cost consumption rather than using a single plantwide rate. The reality is that ABC implementations are expensive, time-consuming, and often produce results that don't change decisions because managers were already making the right calls using simpler methods. The ROI on an ABC system depends heavily on how heterogeneous your product mix is and how large your overhead pool is relative to direct costs. If overhead is less than thirty percent of total cost and your products are relatively similar, ABC adds precision without adding decision value. You're spending money to know something you already knew.
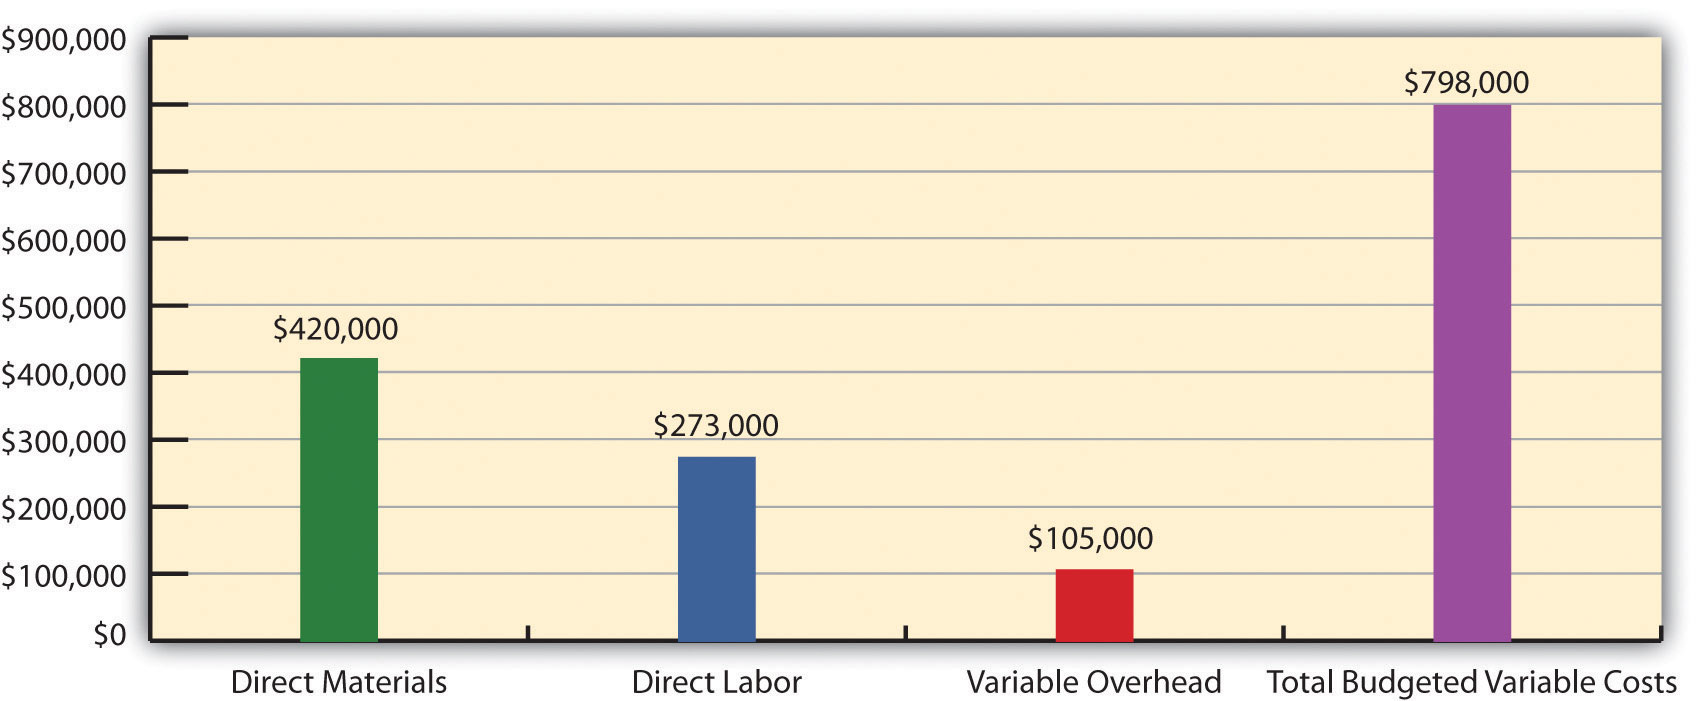
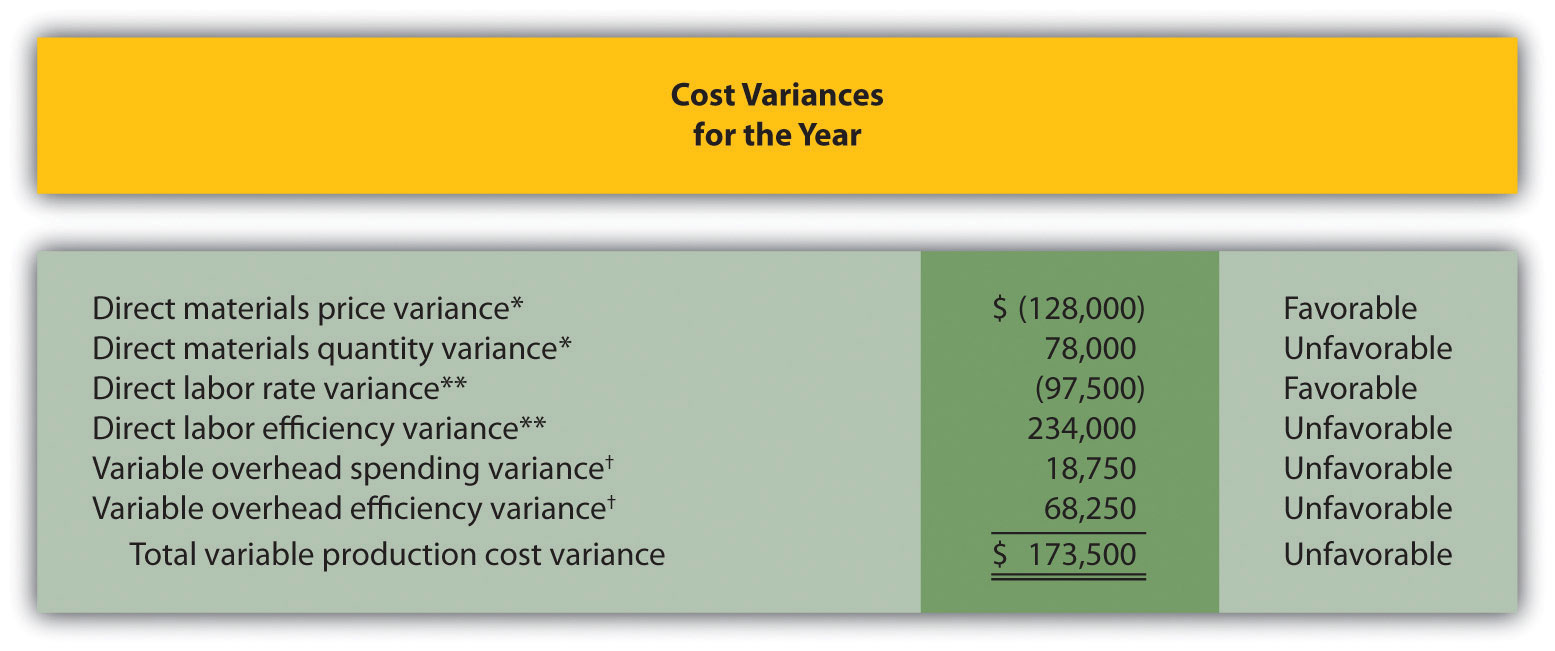
Standard costing and variance analysis remain the workhorse of manufacturing environments. Set a standard cost for materials, labor, and overhead. Track actual costs. Calculate variances. The material price variance and material usage variance tell you different things. One flags purchasing issues, the other flags production efficiency problems. The labor rate variance and labor efficiency variance split the same way. The real value comes from investigating variances that exceed your predetermined threshold, not from calculating them and filing them away. A variance report that sits in a monthly packet without follow-up is just expensive paper. One specific problem I ran into repeatedly involved shared facilities and cost allocation between divisions. Two product lines used the same warehouse space, the same quality control lab, and the same logistics staff. The finance team allocated costs based on square footage for warehouse expenses and headcount for support functions. This created a distortion because one product line moved high volumes of lightweight goods while the other moved lower volumes of heavy goods. The weight-volume relationship drove actual warehouse costs far more than square footage did. The fix was to switch to a dual-driver allocation model using both cubic volume and weight as cost drivers, then validate the results against actual invoices from third-party logistics providers. The adjusted allocation changed the profitability picture enough to alter a pricing decision that was quietly eroding margin on the heavier product line. The most common pitfall I see is treating cost analysis as a one-time exercise rather than a recurring process. The economic environment changes. Input prices fluctuate. Technology shifts. A cost model built during a period of stable commodity prices becomes unreliable when those prices move significantly. Updating models quarterly rather than annually catches these drifts early. Even a simplified update is better than running stale assumptions for twelve months.
Another blind spot is ignoring the behavioral dimension. Cost analysis affects how people behave. When you measure and reward based on cost metrics, people optimize for those metrics. This can create local optimization that hurts the broader organization. A procurement manager hitting a cost reduction target by switching to a cheaper supplier might trigger higher defect rates, longer lead times, and increased downstream rework. The unit cost went down. The total delivered cost went up. Cost analysis has to account for these second-order effects or it becomes a tool for chasing the wrong numbers. There are also scenarios where cost analysis simply cannot produce a reliable answer. When you're dealing with entirely new markets, novel products, or uncertain demand patterns, historical cost data doesn't exist and proxy estimates carry too much error to be useful. In these cases, real options analysis or scenario planning provides more value than traditional cost modeling. You acknowledge the uncertainty explicitly rather than pretending your model captures it accurately. Running three cost scenarios — optimistic, base, and pessimistic — with clearly stated assumptions is more honest than producing a single-point estimate that looks precise but rests on fragile foundations. Data quality is another constraint that shows up constantly. Cost analysis is only as good as the data feeding it. If your accounting system records costs at the wrong level of aggregation, if joint costs aren't being back-flushed correctly, if time tracking is approximate rather than actual, your output will reflect those errors regardless of how sophisticated your methodology is. I've spent more time cleaning data than building models. Don't skip the data audit. A two-hour review of source data can prevent weeks of chasing phantom variances.
For organizations looking to institutionalize this process, the most practical starting point is a tiered approach. Use simple methods — high-low, contribution margin analysis, basic CVP — for routine operational decisions that need answers within days. Reserve regression-based models and activity-based costing for strategic decisions with longer horizons and larger resource commitments. This keeps the effort proportional to the decision importance. Most decisions don't deserve the most expensive analytical tool available. The tools themselves are straightforward. Excel remains the dominant platform because it's everywhere and flexible enough for most use cases. For larger datasets or recurring models, dedicated cost accounting software or ERP modules reduce manual error and speed up updates. The choice depends on transaction volume, model complexity, and how often the analysis needs to be refreshed. A small team running monthly break-even calculations doesn't need an enterprise system. A manufacturing operation with thousands of SKUs and daily production reporting does. What matters more than the tool is the habit of questioning assumptions. Every cost model rests on assumptions about relevant ranges, cost behavior, and decision boundaries. State those assumptions explicitly. Test them periodically. When they no longer hold, adjust the model rather than forcing the data to fit an outdated structure. Cost Analysis In Managerial Economics is less about finding the right answer and more about asking the right questions with enough discipline to avoid the easy ones.