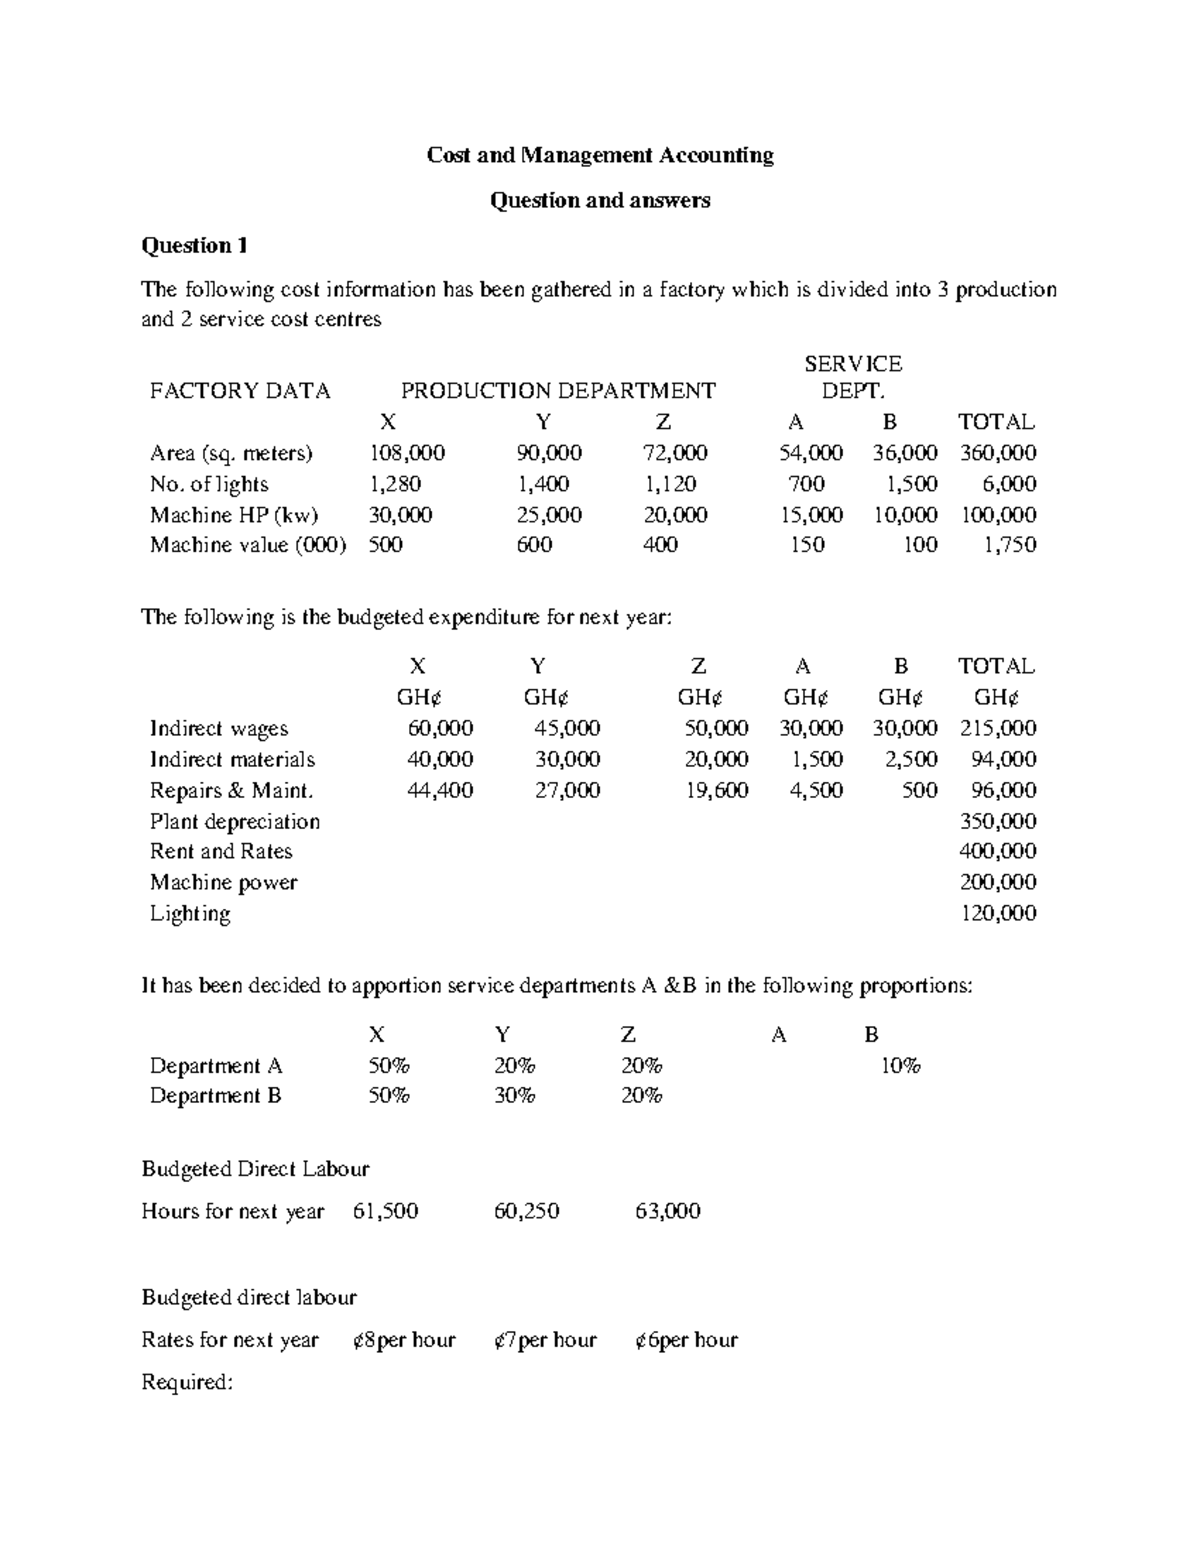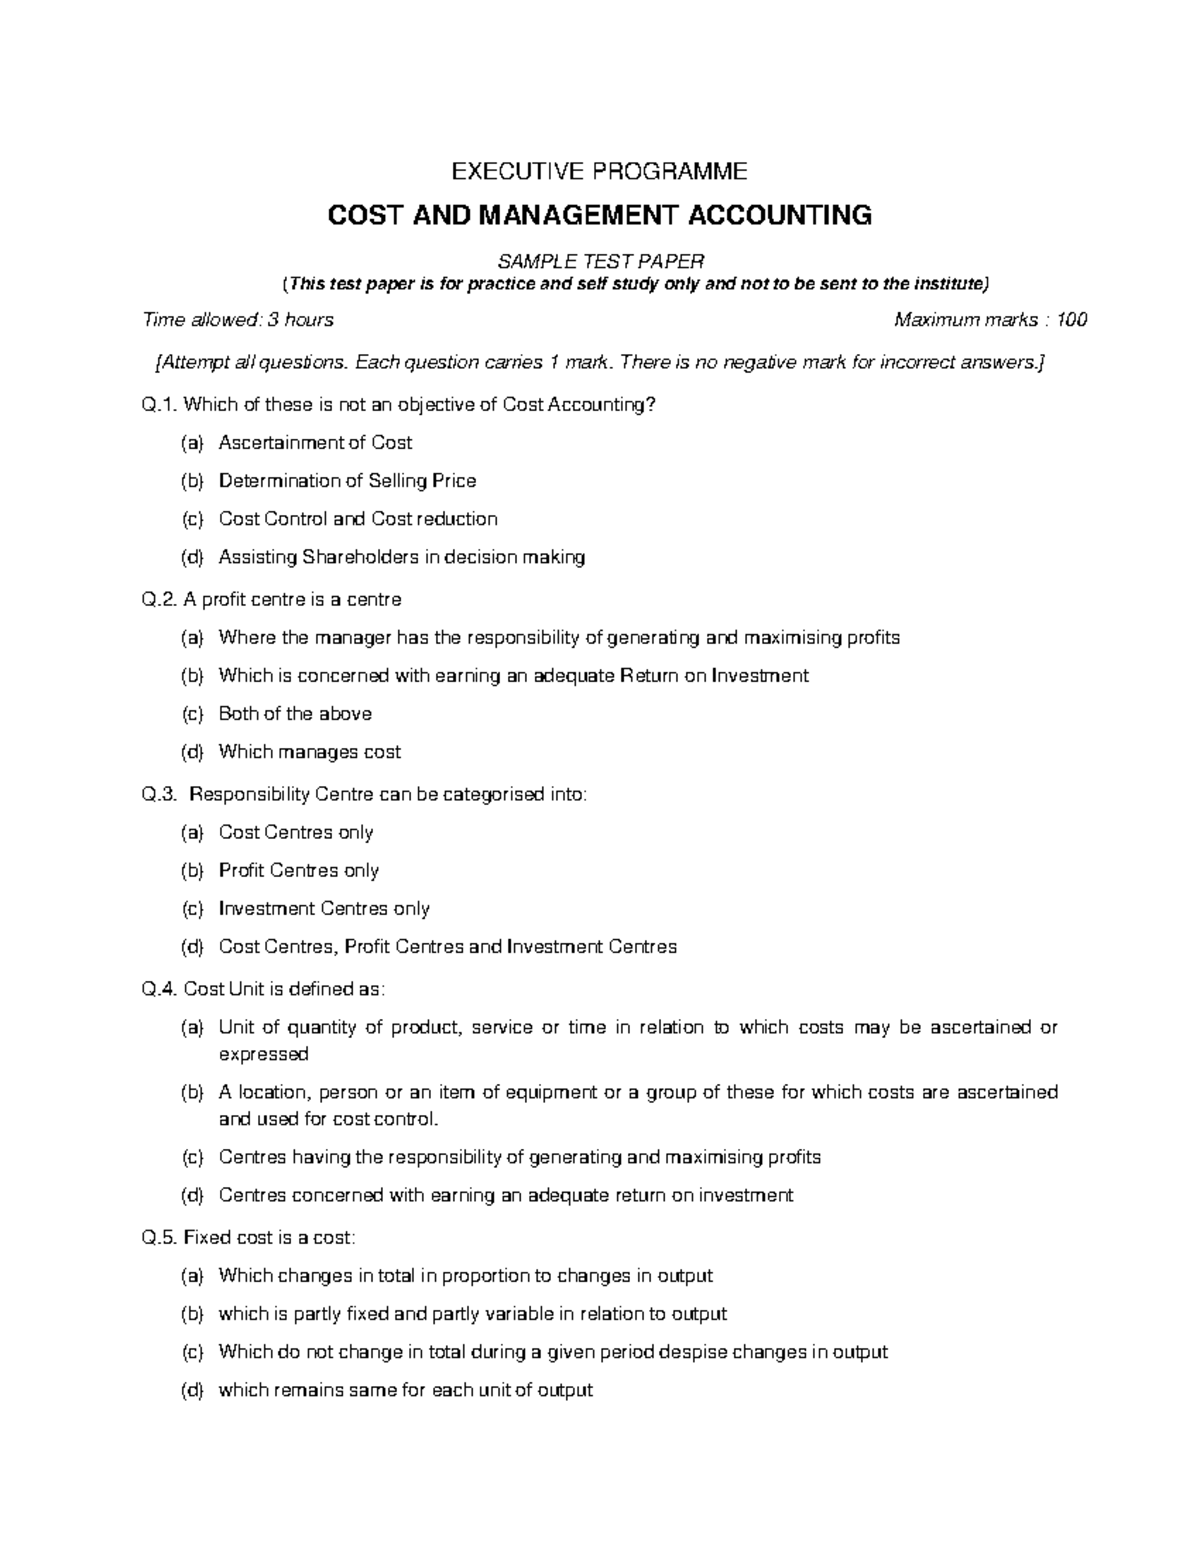
Cost Management Accounting Questions And Answers
Most people think cost management accounting is just tracking what you spend and making sure the numbers look reasonable. It's more specific than that. You're looking at how every dollar moves through a business, where it leaks, and what it actually costs to produce one unit of something. A lot of the time, people get confused because they treat it like a financial accounting exercise when it's really an operational one. Cost management accounting is the practice of tracking, analyzing, and controlling costs within an organization so that decision-making is based on real data instead of assumptions. It's used internally, not for external reporting like GAAP or IFRS require. That's the first thing people miss. External financial statements don't need this level of detail. This exists to help a company figure out whether it should make a product in-house or outsource it, whether a particular customer is actually profitable, or whether a manufacturing process is bleeding money on overhead. The core methods are standard costing, activity-based costing, and marginal costing. Standard costing compares what something should cost against what it actually costs, and then you investigate the variances. Activity-based costing assigns overhead based on what actually drives the cost, not just on direct labor hours or machine hours, which most legacy systems still use. Marginal costing separates fixed and variable costs so you can figure out contribution margins for pricing decisions.
I've seen too many companies run activity-based costing and get results that are wildly different from their standard costing numbers, and then they just pick whichever one looks better for the quarter. That's not how this works. The point isn't to find the answer that supports a decision you've already made. The point is to find the discrepancy and understand why it exists. If ABC and standard costing give you two different pictures, you have a process problem somewhere, not a calculation problem.
A Specific Problem I Dealt With
About four years ago, I was working with a mid-sized food manufacturer that had a discrepancy between their absorption costing and their actual gross margins on certain product lines. They were using machine hours as their sole overhead allocation base, which is common but outdated. The problem was that their most profitable product by the standard system was actually losing money once you accounted for the setup time, quality inspections, and material handling that each product required. Those activities weren't tied to machine hours at all. I rebuilt the overhead allocation model using four cost drivers instead of one: machine hours for processing, setup hours for changeovers, inspection hours for quality control, and material moves for warehousing. The result flipped their top three products. Two of them were money losers at the current volume. We ended up adjusting pricing on those two and dropped a low-volume specialty line that was eating up setup time across three production runs. The whole restructure took about three weeks of data collection and two weeks of recalibration. Without it, they would have kept expanding a product line that was subsidizing their actual profitable operations.
Get the Full Details
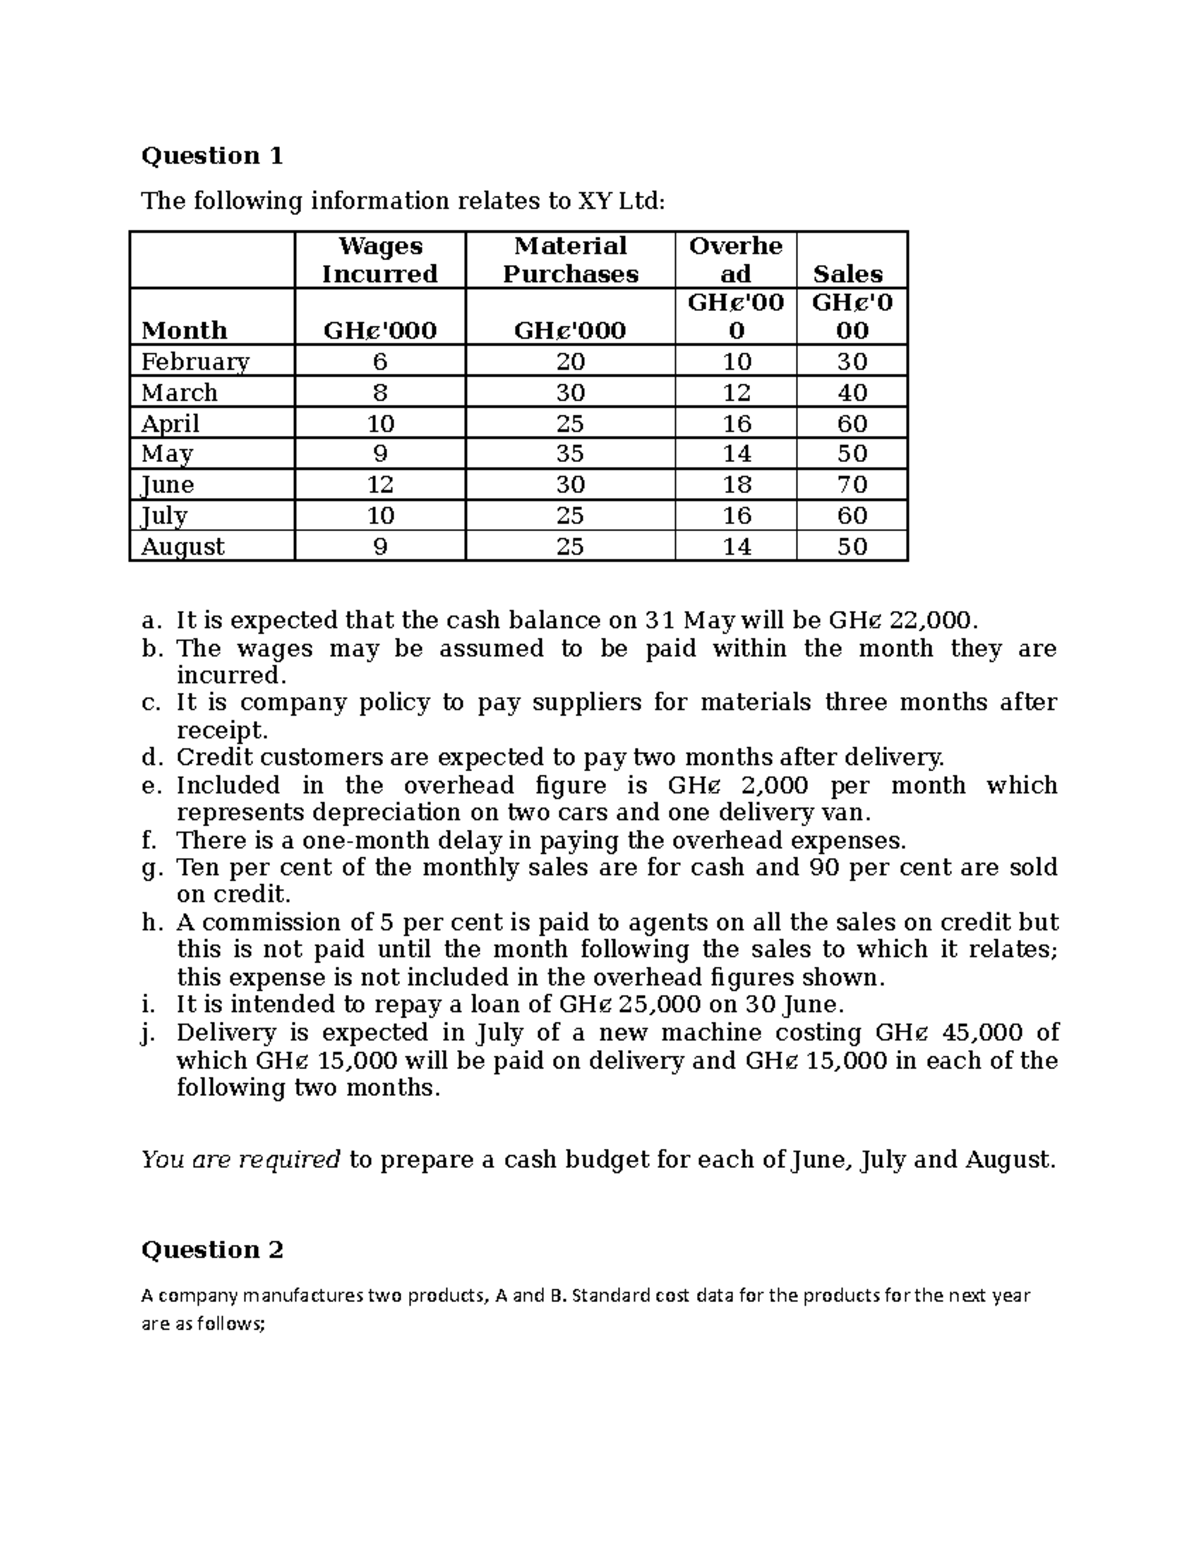
Common Questions People Have
Should I use ABC or stick with traditional costing?
It depends on how complex your overhead is. If your overhead is less than 20 percent of total costs and it correlates well with production volume, traditional costing is fine. If overhead is higher or driven by multiple activities that don't scale with volume, ABC will save you from bad decisions. The problem with ABC is that it requires accurate data collection, and most companies don't have the systems to capture that without a lot of manual entry. If you can't track setup times or material moves accurately, ABC just gives you fancy wrong numbers. You calculate the difference between standard and actual, then you assign the variance to a responsible party or department. Price variances usually go to procurement. Usage variances go to production. Efficiency variances go to operations. The key is that variances need to be investigated, not just recorded. A $5,000 unfavorable materials price variance might look small in a quarterly report, but if it's happening every month on a specific component, you're looking at a supplier contract that needs renegotiation or a specification that's unnecessarily strict. Yes, but you need to identify what your cost drivers are. For a service business, it might be client hours, project complexity tiers, or support ticket resolution time. The framework is the same. You're just applying it to different inputs. I worked with a software consulting firm that thought they were profitable across all clients until we traced actual delivery hours against what they were billing. Three of their ten largest clients were operating at a loss after you factored in senior developer time and rework. They ended up restructuring those contracts or dropping the clients entirely.
You don't need expensive software to start. A well-built Excel model with clear cost pools and allocation logic will get you 80 percent of the way there. The problem is that Excel breaks down when you're dealing with more than a few thousand transactions or when multiple people need to update it simultaneously. Once you hit that scale, you look at ERP modules dedicated to cost management, like SAP CO or Oracle Cost Management. The transition is painful because your Excel model is probably your only source of truth and nobody wants to rebuild it in a new system. You migrate one cost pool at a time and validate against the old model before moving to the next. Cost management accounting assumes that you can accurately measure and assign costs to specific activities or products. That breaks down in environments where costs are shared across too many departments with no clear causal relationship. A shared IT infrastructure cost, for example, is nearly impossible to allocate fairly. You can try to use headcount or server usage, but neither feels right. In those cases, you either leave the cost unallocated and track it separately at the corporate level, or you accept that the allocation is arbitrary and focus your analysis on the costs you can actually trace. Another failure point is when management treats cost accounting data as static. Costs change. Supply chains shift. Labor rates adjust. If you build a cost model and never update it, it becomes worse than useless because it gives you false confidence. I've seen companies run the same allocation model for five years without refreshing the underlying rates, and then wonder why their product mix decisions didn't improve profitability. The model wasn't the problem. The stale data was.
Pitfalls To Avoid
Don't allocate fixed costs based on expected volume. If you allocate based on what you think you'll produce and then produce less, your unit costs look inflated and you might cancel a product that's actually contributing to covering fixed costs. Always allocate fixed costs based on practical capacity, not expected output. Don't chase perfection in your cost tracking. If you're spending more on data collection and model maintenance than the decisions are worth, you've missed the point. A good cost model should take less time to run than the meeting where you'd discuss the decision without it. If it takes three days to produce a report that gets a fifteen-minute conversation, simplify the model.

Cost Management Accounting Questions And Answers
Here are some of the questions I get asked most often in workshops and consulting engagements. How do I decide which products to discontinue? Look at the contribution margin after tracing all variable costs and avoidable fixed costs. If a product covers its variable costs and contributes to fixed costs, discontinuing it doesn't automatically improve profit unless you can eliminate the fixed costs or redeploy those resources more profitably. What's the difference between cost accounting and cost management? Cost accounting is the measurement and recording. Cost management is using that data to make decisions. You can have excellent cost accounting and terrible cost management if nobody acts on the numbers.
How often should I update my standard costs? At least annually, but if your input costs are volatile, quarterly or even monthly makes sense. The standard is supposed to be a realistic benchmark, not a historical artifact. Should joint costs be allocated? For decision-making, no. Joint costs are sunk at the split-off point. Allocating them to individual products can make a profitable product look unprofitable. Treat joint costs as a common cost and evaluate each product on its own revenue minus separable costs. How do I handle overhead in a lean or just-in-time environment? Traditional absorption costing tends to overstate product costs in lean environments because fixed overhead gets spread over fewer units when you reduce batch sizes. Activity-based costing handles this better because it ties overhead to actual activities rather than production volume.