Why Most Finance Journals Are Boring and What to Do About It
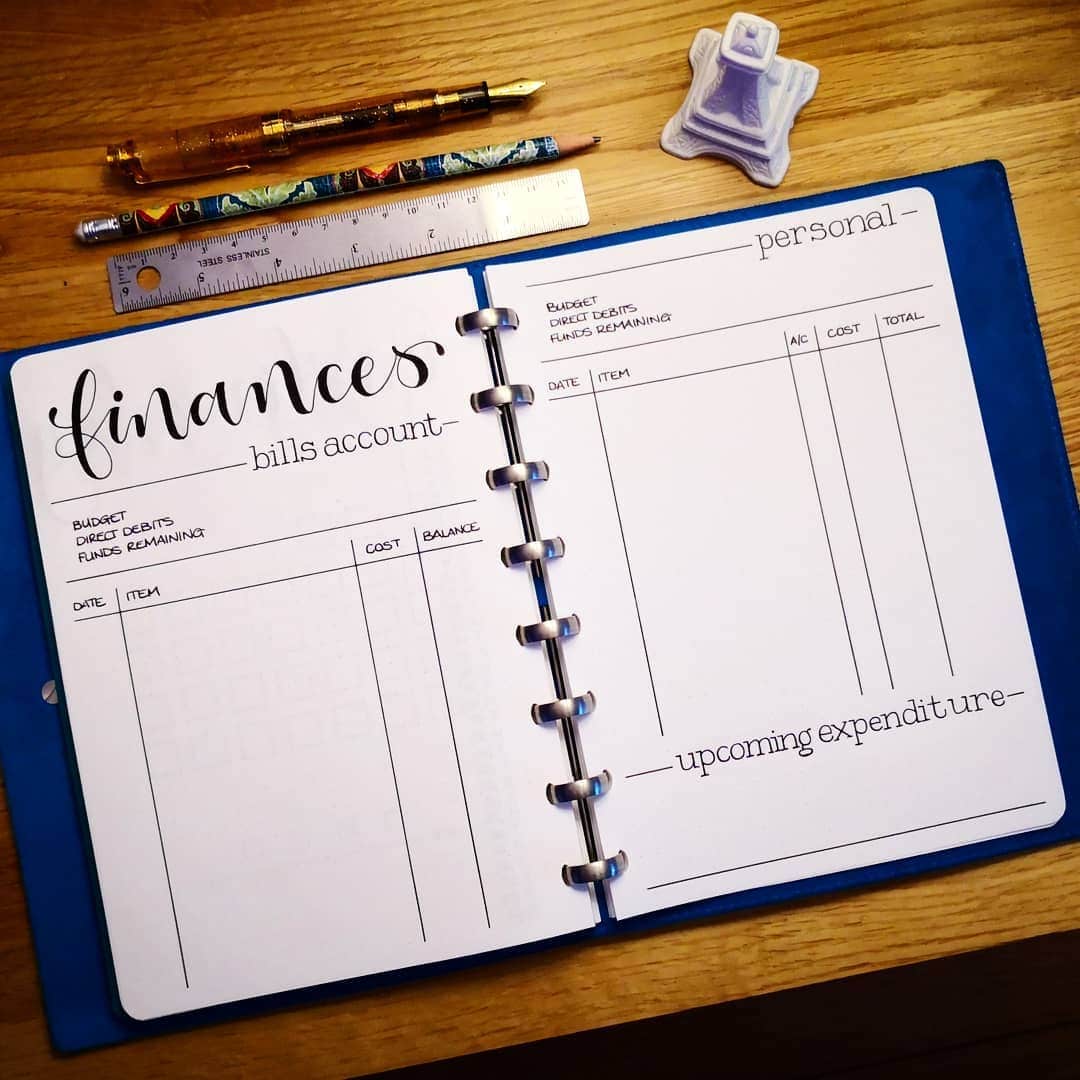
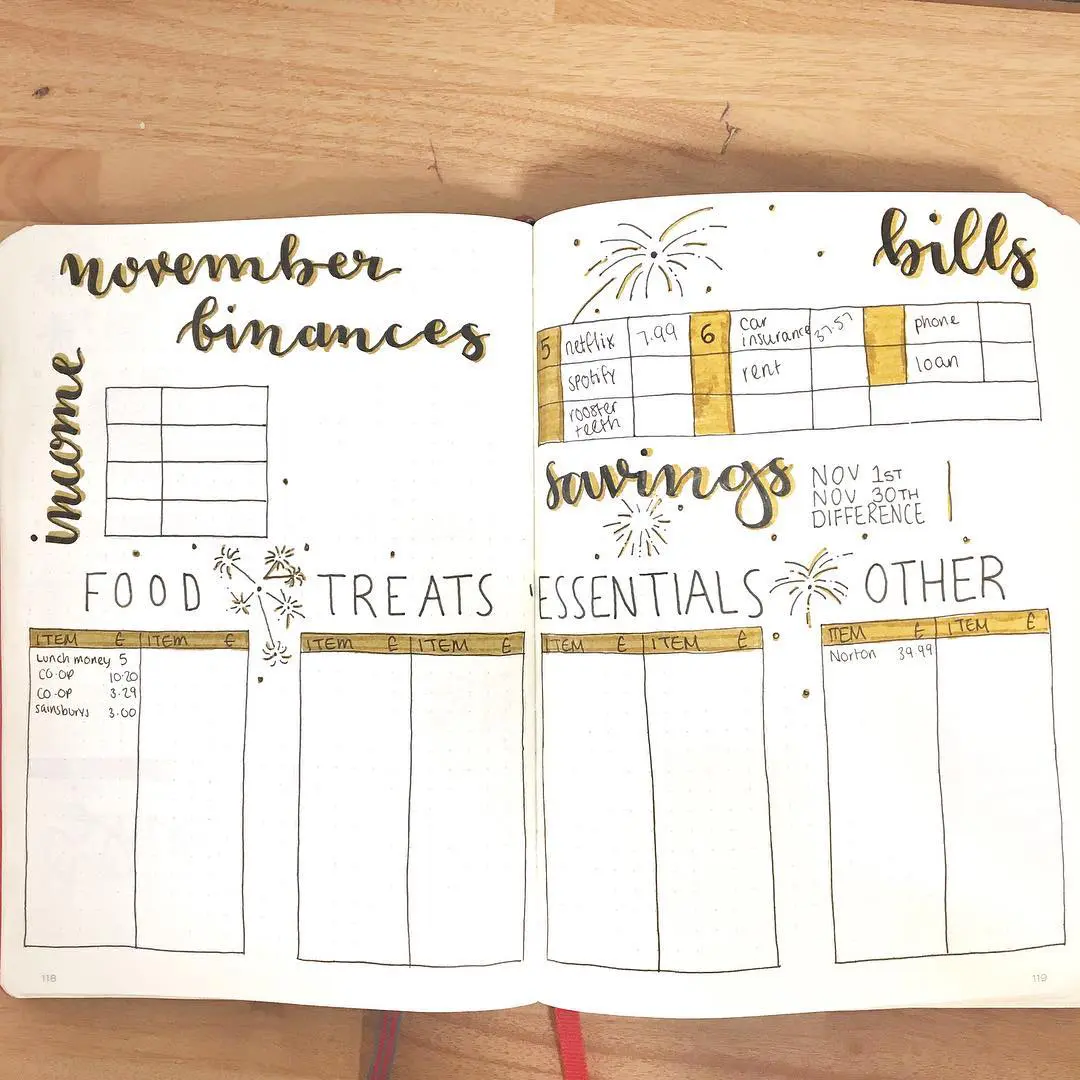
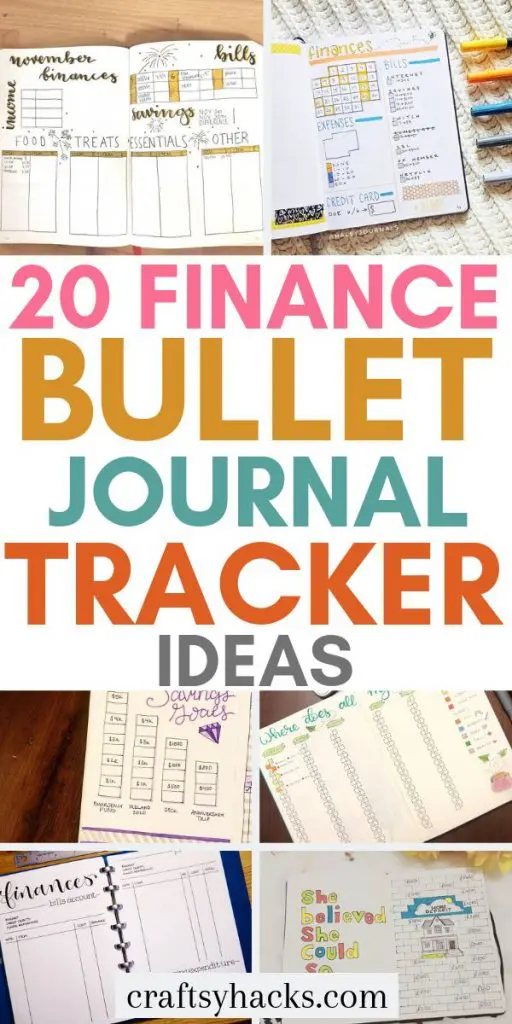
Standard spreadsheets work fine for tracking expenses, but they don't help you actually understand your financial behavior. I spent years watching people fill out identical columns for month after month until they stopped looking at them altogether. The problem isn't that budgeting doesn't work. The problem is that most journal formats treat you like a robot entering data instead of a person making decisions. Creative Finance Journal Ideas are about switching from pure recording to actual reflection. The best systems I've seen combine transaction tracking with brief notes about the emotional or situational context behind each spending decision. You capture what happened, yes, but you also capture why it happened. That distinction matters more than most people realize.
Here Is One System That Actually Sticks
Start with a simple weekly review rather than daily micro-tracking. Daily tracking sounds efficient but it creates friction that makes people quit within three weeks. I recommend blocking out forty-five minutes every Sunday evening to log the previous week's major transactions and answer three questions for each one: what triggered it, was it aligned with your current priorities, and would you do it again under similar circumstances. Use a plain notebook or a simple app. Apps like Notion, Obsidian, or even Google Docs work fine for this because you can cross-reference entries and search back through months of data. The tool doesn't matter as much as the consistency of the reflection process itself. Here is where most people go wrong. They write things like "spent forty dollars at restaurant" and move on. That entry has zero analytical value. Instead you should write something like "spend forty dollars at restaurant after long work day because cooking felt like too much effort. Felt guilty about spending but enjoyed it anyway." The difference is the second entry gives you information you can actually use when patterns emerge.
The Specific Problem I Ran Into
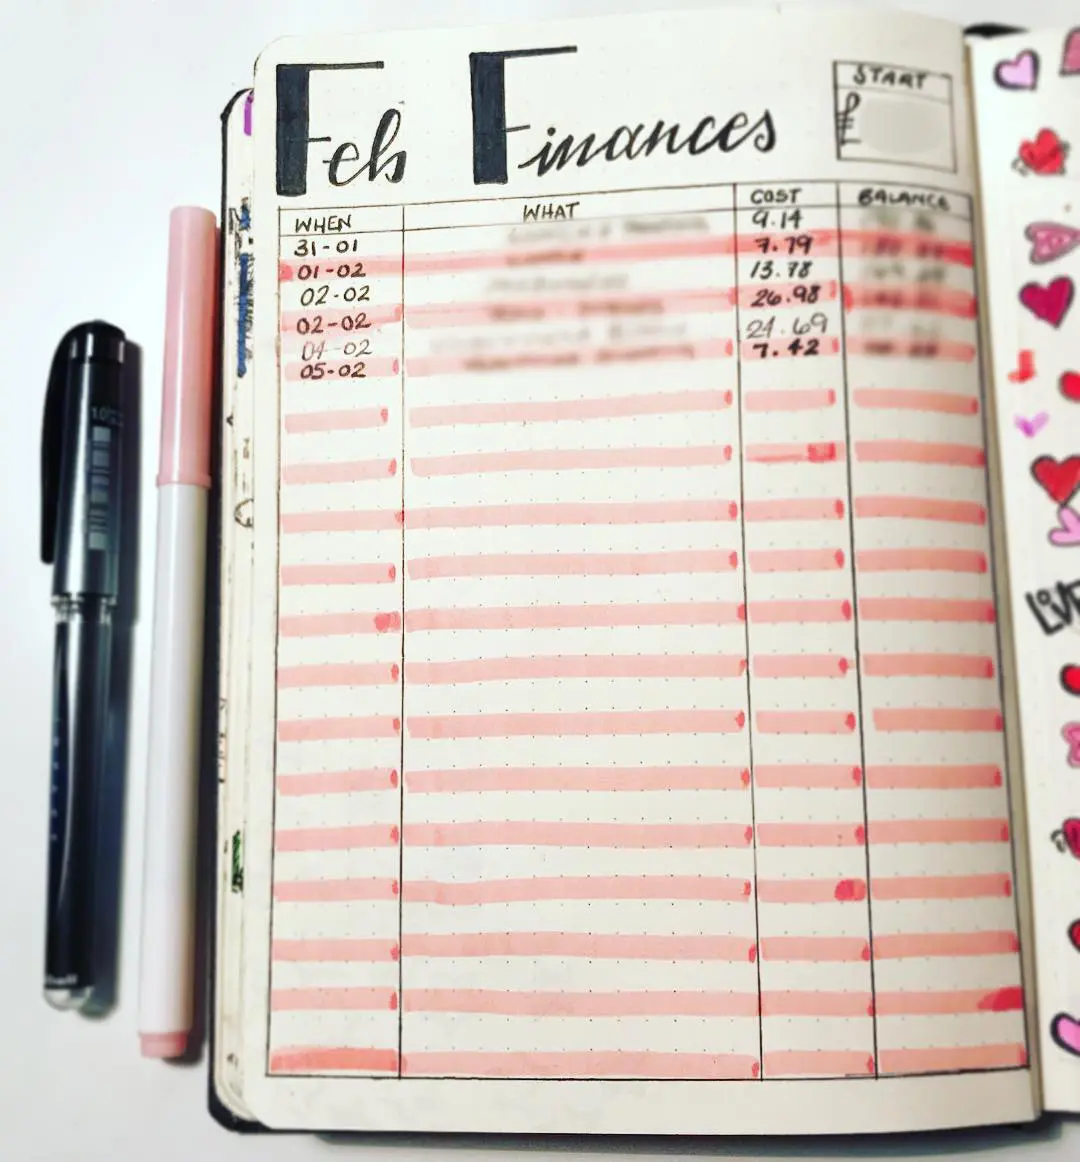
Early on I built a very elaborate journal system with categories, subcategories, color coding, and conditional formatting. It took me roughly two hours to set up and I used it for about eleven days. The complexity itself became the barrier. Every time I opened the spreadsheet I felt obligated to categorize something perfectly instead of just noting what happened. Perfect is the enemy of consistent here. My workaround was brutal simplification. I switched to a single column for date, a single column for amount, a single column for description, and one column for a five-word max emotional context tag. That's it. I could log an entry in under thirty seconds. The system that looked worst on paper produced the most useful insights over six months because I actually maintained it.
Get the Full Details
Deeper Layers That Most People Skip
After about three months of basic reflection logging, you start noticing recurring triggers. Some people consistently overspend on weekends. Others hit a wall around midmonth when fixed bills hit and discretionary spending feels unjustified so they compensate with something impulsive. Identifying these patterns is the actual point of the exercise, not just accumulating data points. Try adding a monthly net worth snapshot alongside your transaction journal. Not a perfect calculation with every asset and liability. A rough estimate you do in two minutes. That monthly anchor gives you context for the daily stuff. When you see your net worth trending upward even while you're spending impulsively on random purchases, it changes how you feel about those purchases. You can address the behavior from a position of real awareness rather than guilt. One counter-intuitive thing that caught me off guard. The more detailed you try to make your journal, the less honest you become. When you have to fill out a form with ten fields for every transaction, you start gaming the system. You round numbers. You misclassify things. You stop journaling entirely. Simplicity preserves honesty. Honesty produces usable data. That chain is non-negotiable.
A Practical Template You Can Adapt
Date | Amount | Category | Where | The Real Reason (one sentence) Example entry from my own journal from last November: 11/14 | $87.50 | Food | Grocery store | Bought expensive coffee beans I don't actually need because a colleague mentioned a new roast and I wanted to sound knowledgeable about something. That entry looks almost ridiculous. But six months later when I reviewed it, I realized I had a pattern of buying unnecessary specialty food items whenever I felt socially insecure at work. That's actionable information. "Spent money" alone is just a number. The journal format gives you the pathway to understanding.
What This Approach Cannot Do For You
I need to be clear about the limitations. A creative finance journal will not fix structural income problems. If your expenses exceed your income regardless of spending choices, journaling won't change that math. It will help you see the gap clearly, but it won't close the gap. You still need to address income or fundamental cost structure separately. The system also requires honesty, and honesty is hard to maintain when you're stressed about money. During periods of financial strain, some people find themselves avoiding their journal entirely because looking at the numbers feels painful. That's a real failure mode. If you hit that wall, switch to a less frequent schedule. Weekly becomes biweekly. Biweekly becomes monthly. Something is better than nothing, and stopping completely means you lose visibility into your own behavior during the exact period when that visibility matters most. Another limitation worth noting. Journaling works best for variable spending categories like food, entertainment, shopping, and hobbies. It is far less effective for fixed obligations like rent, car payments, insurance premiums, or loan payments. Those are what they are. Trying to add emotional context to a mandatory payment rarely produces useful insights. Focus your journaling energy on the categories where you actually have decision-making power.
Long-Term Considerations
Most people abandon journaling after six to eight months because the novelty wears off and they feel like they've already learned everything worth learning. That's not accurate. The insights compound slowly. The real value shows up around month nine or ten when you catch yourself about to make a purchase and immediately recognize the trigger pattern before the transaction happens. That moment of pause is the entire point of the exercise. If you want to deepen the practice without making it complicated, consider adding a quarterly review. Thirty minutes to look back at the past three months of journal entries and identify any emerging themes. Usually two or three themes surface. Maybe you're spending more on dining out when you work late. Maybe gift-giving seasons consistently break your budget. Those quarterly reflections keep the system useful instead of letting it become background noise. The core takeaway is straightforward. Creative Finance Journal Ideas only work if the format is simple enough to sustain and reflective enough to produce genuine insight. Anything more complex than that is usually just elaborate avoidance dressed up as productivity.