Why a Daily Finance Printable Actually Matters
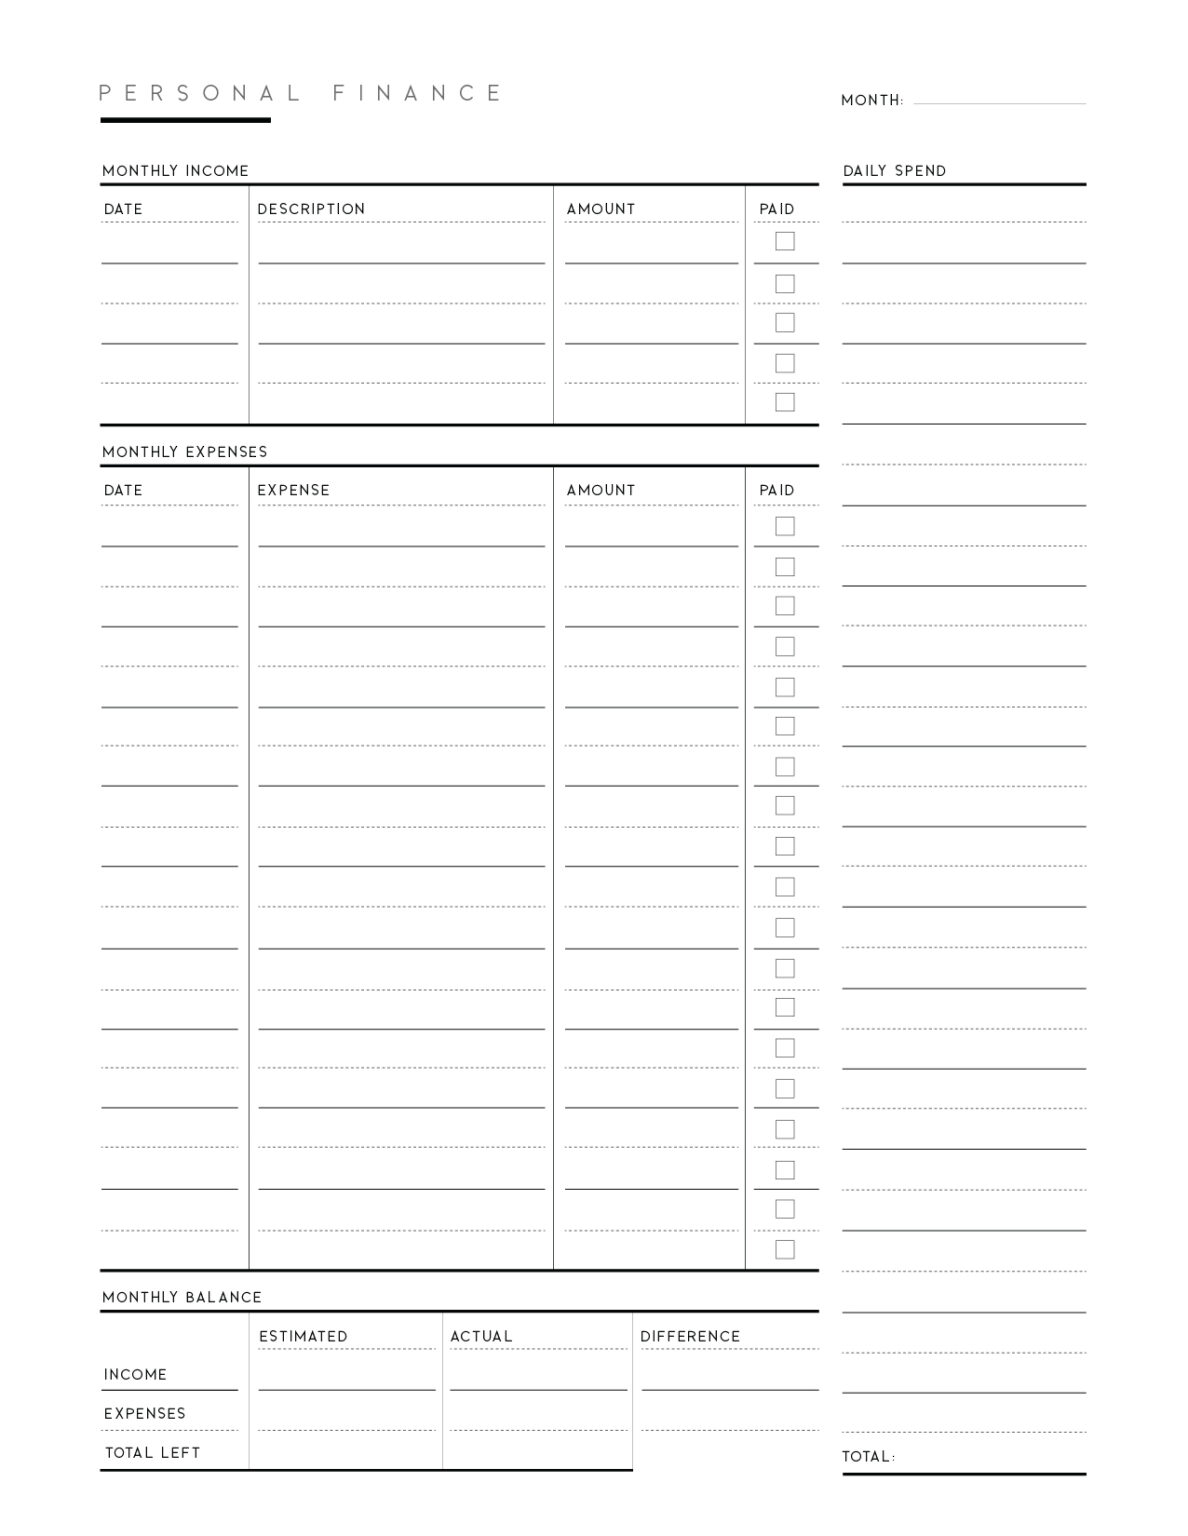
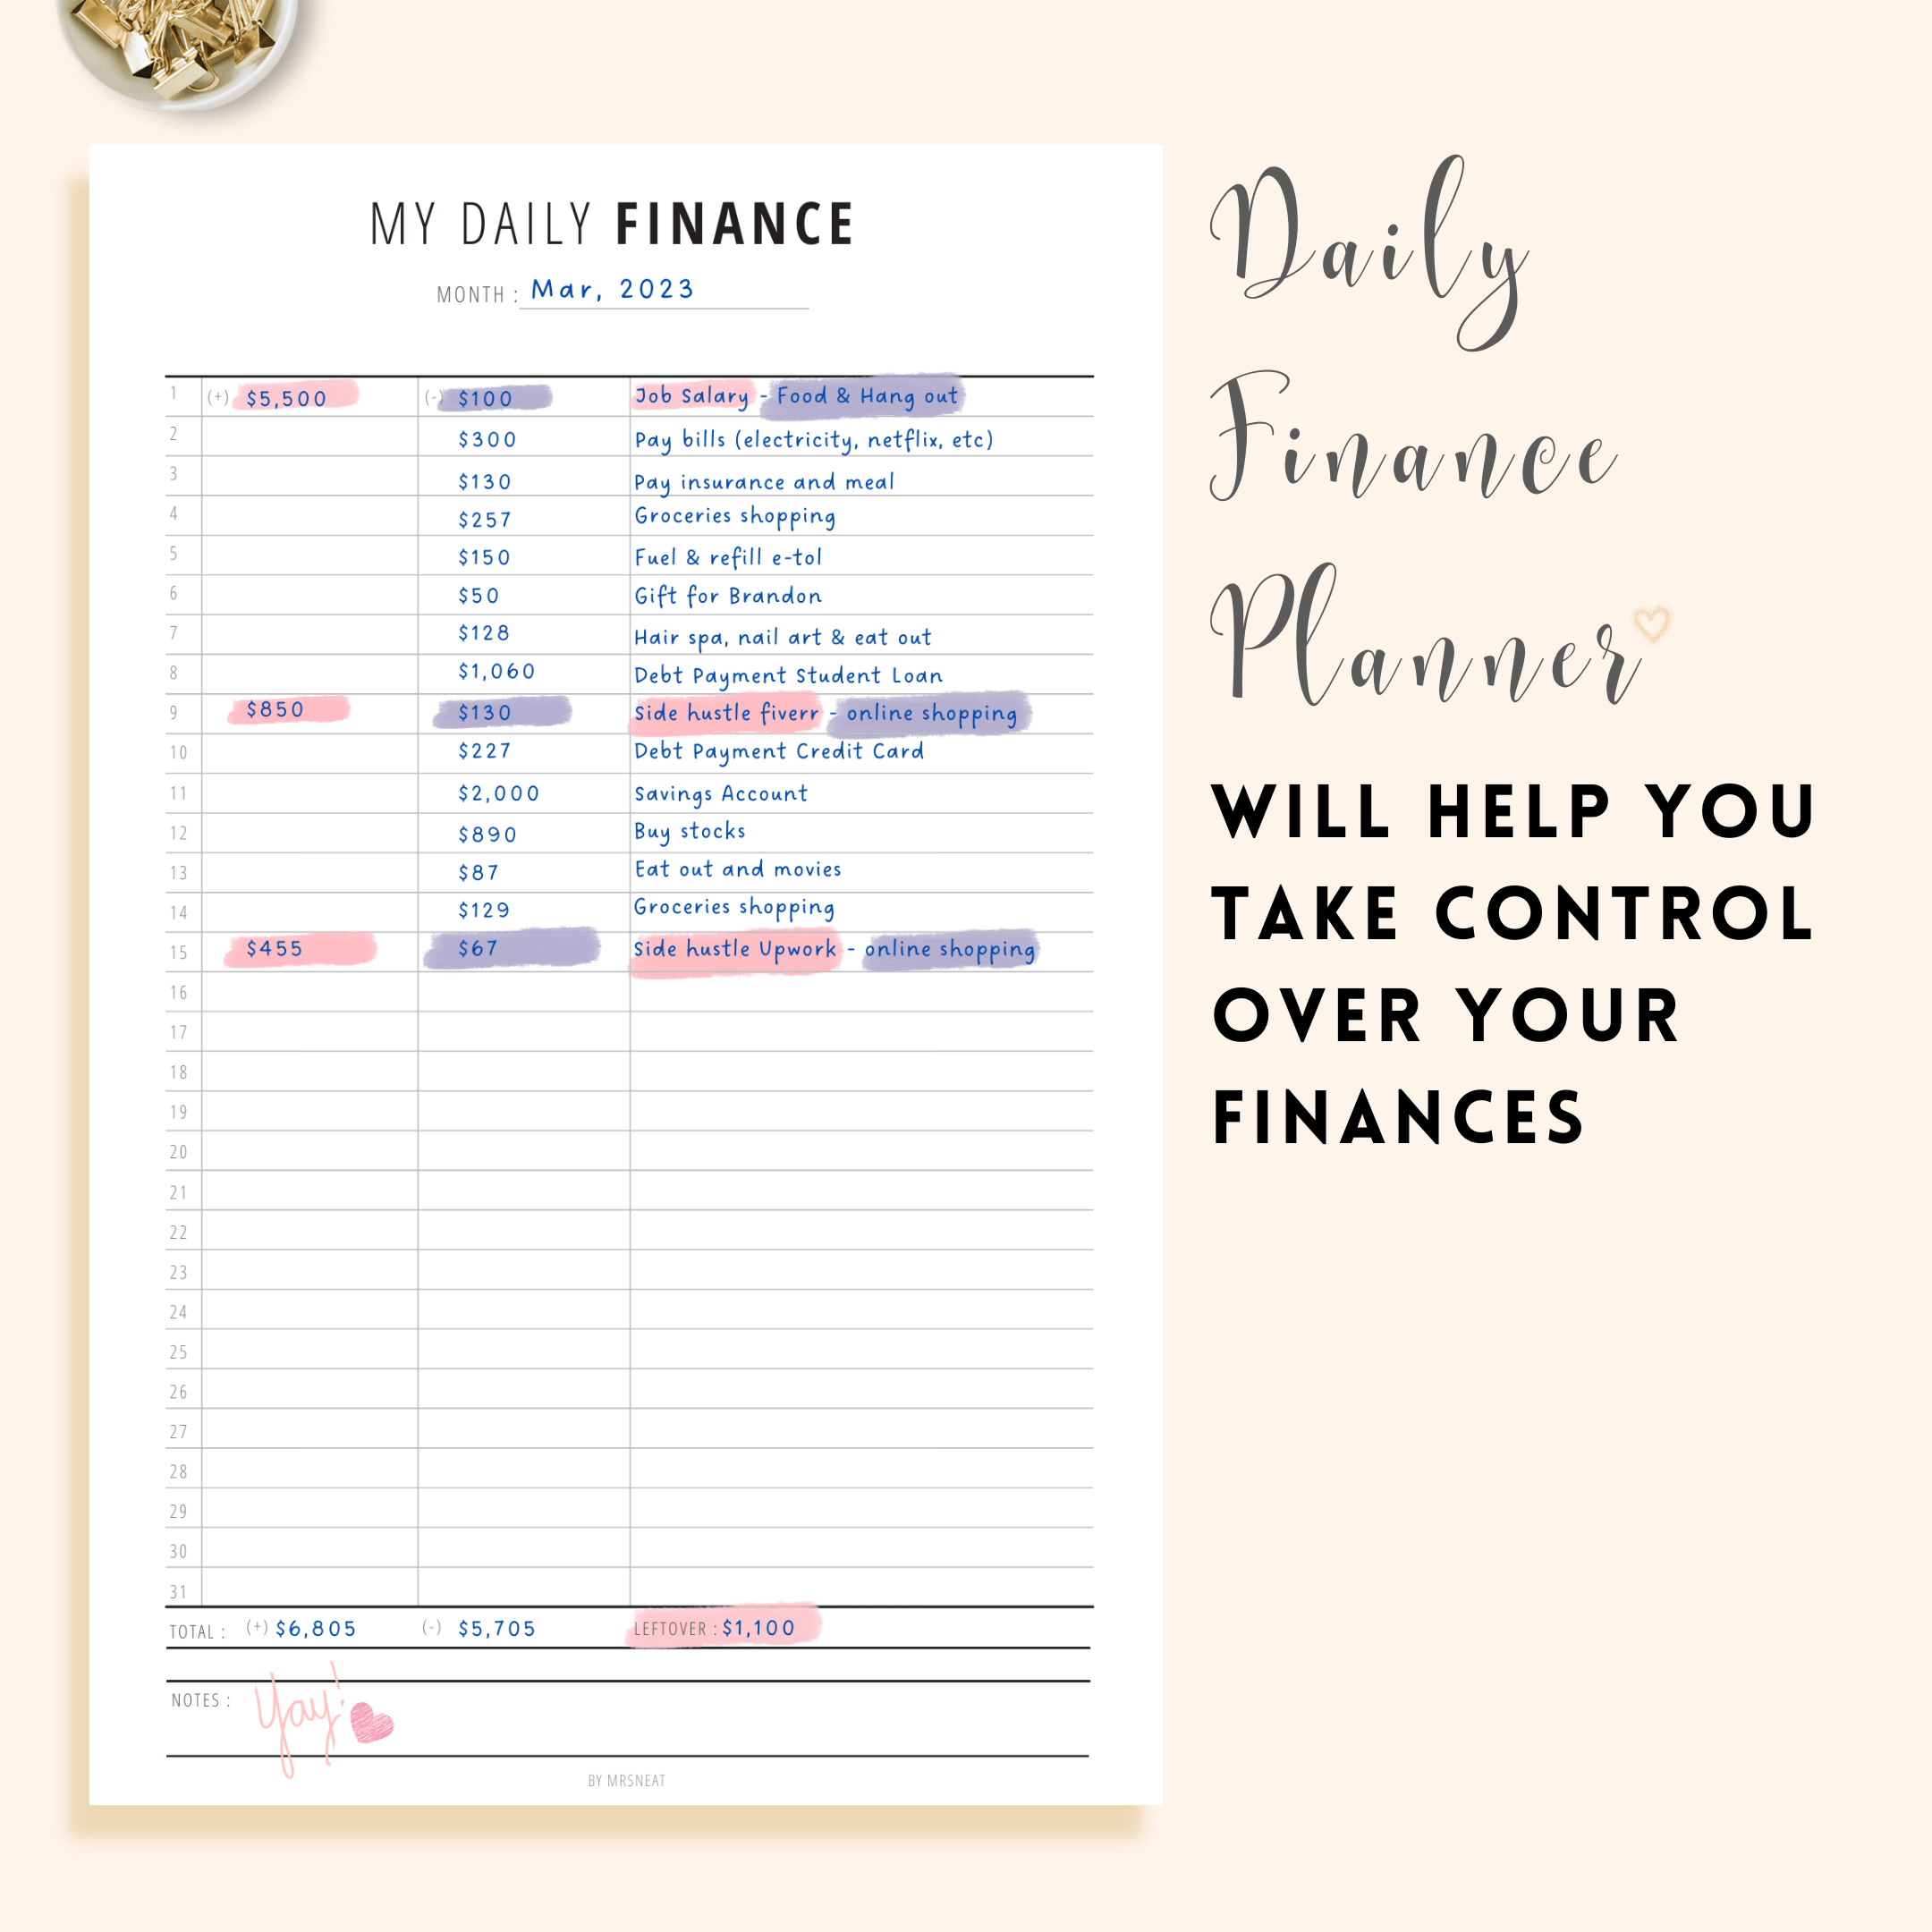
Most budgeting apps fail because they require you to be consistent. That sounds obvious, but consistency breaks down the moment life gets busy. A Daily Finance Printable does something different: it forces you to commit to a single page, once a day, and nothing more. The constraint is the point. You write down your income and every outflow on a structured sheet. You total it at the end. You move on. I stopped relying on spreadsheets around 2019. They became too easy to manipulate, and way too easy to ignore for three days at a time. A printed sheet on my desk was harder to cheat myself out of. I started using a Daily Finance Printable layout that looked nothing like the generic templates online. Mine had a column for transaction reference, a running cumulative balance, and a separate section for recurring fixed costs. The difference between my version and the standard one wasn't aesthetic; it was the cumulative balance column. That single addition caught errors immediately instead of letting them hide in a month-end summary.
The Core Structure of a Useful Daily Finance Printable
Start simple. Do not build a twelve-column masterpiece on day one. The layout needs five essential sections, and everything else is optional clutter. First, a header with the date and a starting balance pulled from your bank account or cash on hand. Second, an income column where you record deposits, side payments, or any money coming in. Third, an expense section with sub-columns for category, amount, and a quick reference note. Fourth, a running balance after each transaction. Fifth, an end-of-day total that reconciles against your bank balance or physical cash. The running balance is non-negotiable. Without it, you are doing arithmetic without feedback. People skip it because it feels slow. It takes about four extra seconds per entry. The payoff is that you spot a mistake while you are still sitting at the table, not three weeks later when you are trying to reconstruct why your account is overdrawn. Here is a straightforward Daily Finance Printable format you can adapt:
Date: ________ | Starting Balance: $________ Income Column Source | Amount | Cumulative Balance
Get the Full Details
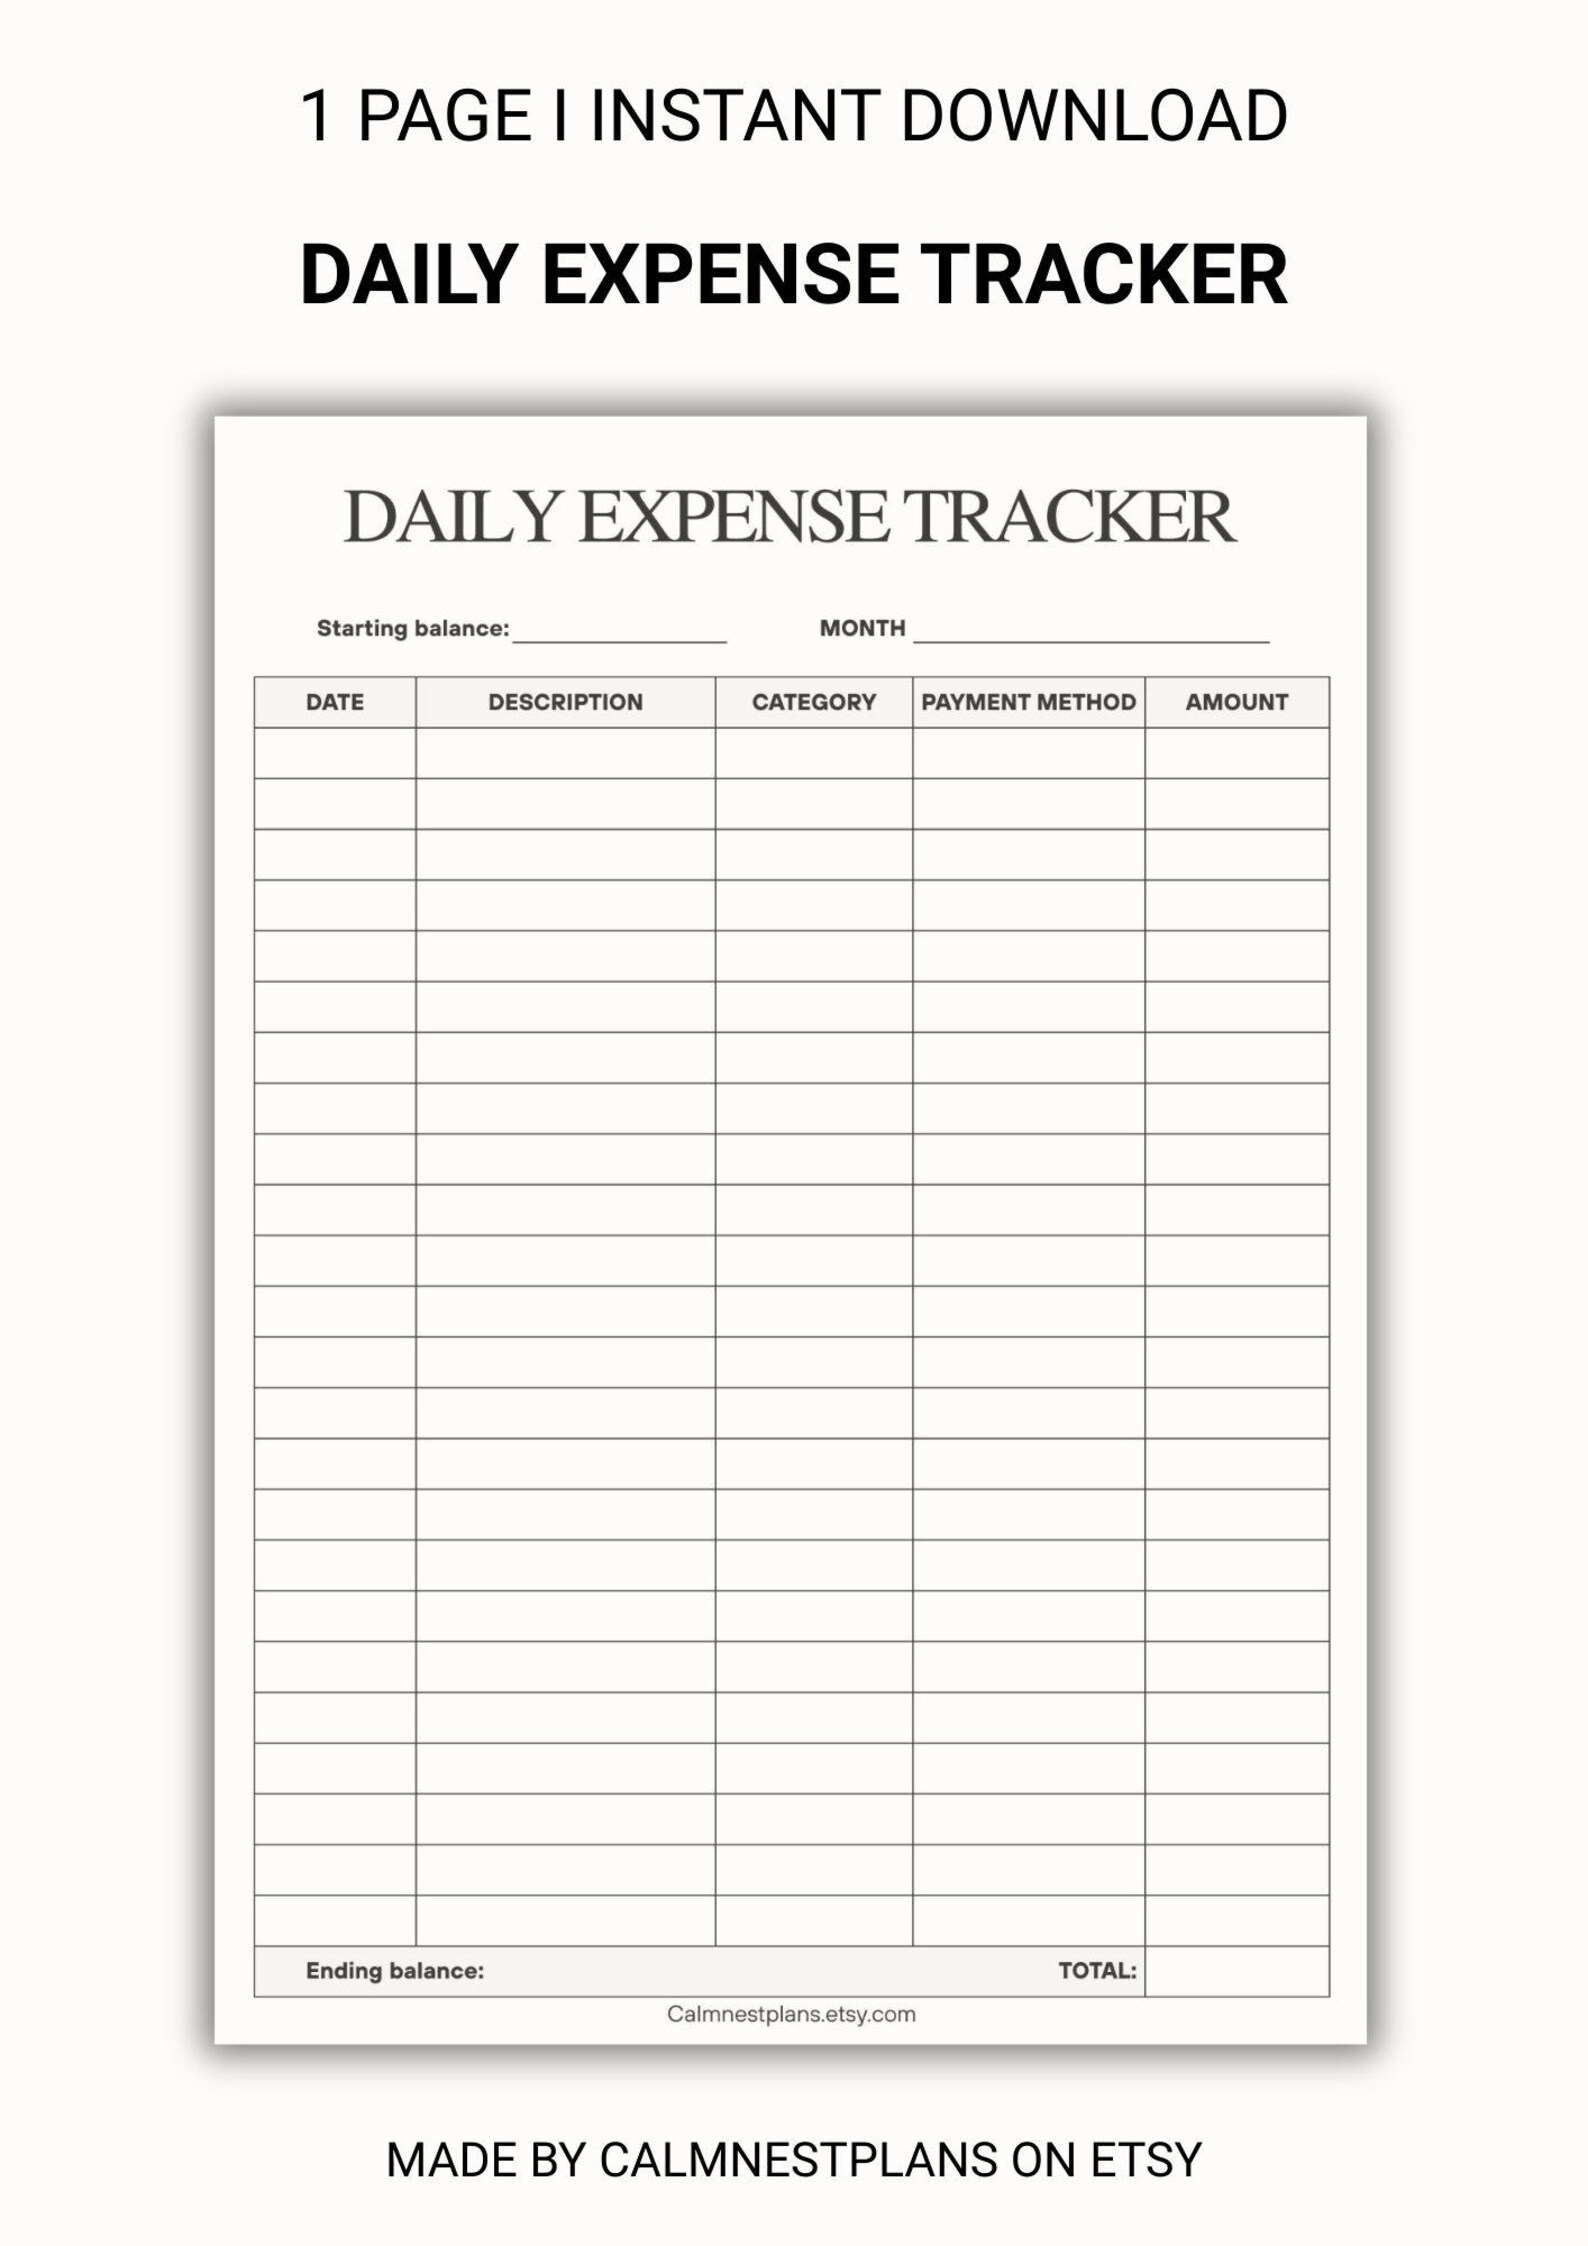
Expense Column Category | Amount | Reference | Cumulative Balance Fixed Costs Tracker (monthly line items)
End-of-Day Total: $________ | Bank/Cash Reconciliation: $________ I keep this as a printed weekly pad. Each page covers one day. The stack ends up about half an inch thick after a month. That thickness is the data you need for monthly review.
How to Set It Up Without Overcomplicating It
You do not need special supplies. A notebook, a pen, and a calculator work fine. If you prefer custom prints, set up a basic table in any word processor and print double-sided on standard letter paper. Four days per page keeps it compact enough to fit on most desks. Six columns maximum. More than that and you are spending more time formatting than tracking. The first week will feel slow. You will want to skip entries when you pay by card and forget the receipt. Write it anyway. Use the card statement as a backup verification, not as a replacement. The habit forms around day eight. After that, the process takes roughly nine minutes for a typical day. If you spend more than fifteen minutes on a single day, you are recording too many micro-transactions. Round coffee purchases and small miscellaneous fees to the nearest dollar. Precision below the dollar level is noise for daily tracking. Edge case I ran into and how I handled it: travel expenses. Hotel, meals, transport, and tips compress into a normal day without warning. On a three-day conference trip, my daily total jumped to forty-two dollars in one sitting. Writing that out destroyed my willingness to continue. I solved it by adding a subtotal line after every five transactions. That way I was grouping rather than listing individually. The Daily Finance Printable stayed readable, and the reconciliation at the end of each day took less than a minute because I already had chunked sums.

Common Mistakes That Break the System
Beginners tend to treat the printable like an accounting ledger. They add columns for payment method, merchant location, tax amount, and dispute status. None of that belongs on a daily sheet. Payment method can be noted in one letter if needed. Merchant details live in your statement. Tax and dispute tracking belong in a separate monthly review document. Adding them to the daily page creates switching costs that kill the habit within two weeks. Another mistake is carrying forward the wrong starting balance. People copy yesterday's ending balance instead of pulling today's actual bank opening balance. The discrepancy compounds silently. One entry off becomes three entries off by Friday. Fix this by checking your bank balance before you write anything. If your bank does not update in real time, use the prior business day's closing balance and adjust only for transactions that posted overnight. A counter-intuitive insight that took me a while to accept: reconciliation should happen daily, not monthly. Most people reconcile once a month because it feels like a chore. Doing it daily reduces the reconciliation window to about thirty seconds. You compare the printed total to the bank balance, note any difference, and move on. The difference is usually a single missed entry or a rounded figure. Monthly reconciliation turns that same difference into a forensic investigation.
Reconciling Without Losing Your Mind
Match the end-of-day total to your bank account balance for that date. If they differ by more than two dollars, investigate immediately. Check for unrecorded ATM withdrawals, autopay runs, or fees posted before you started tracking. If the difference is under two dollars, round it out and note it as a variance. Tracking every penny of variance creates false precision and distracts from the larger pattern. I track variance separately in a small monthly log so I can see if rounding errors accumulate. There is a scenario where this method fails entirely: irregular income with multiple deposit sources. Freelancers, commission workers, and seasonal employees often have income landing unpredictably across accounts. A single daily finance printable does not capture that cleanly. In those cases, use two pages per day. One for earned income by source. One for fixed and variable expenses. Merge them only during weekly review. The added complexity is worth it compared to losing track of which deposit covered which bill.
What the Data Actually Tells You After a Month
Most people stare at the totals and miss the pattern. The useful signal is not the final number; it is the variance between projected and actual spend per category. A typical month of daily tracking reveals whether your coffee habit is two hundred dollars or four hundred dollars. It shows which fixed cost increased without warning. It exposes the gap between what you think you spend and what actually leaves your account. I ran this for fourteen months before I felt confident in the numbers. The first four months were cleanup. I was correcting old habits, forgetting entries, and misreading statements. Months five through eight were stabilization. The habit held, and the variance numbers became reliable. Months nine through fourteen were optimization. That is when I started adjusting categories based on the data instead of guesses. If you want to download a ready-to-use template, search for Daily Finance Printable PDF and pick a version with a running balance column and a fixed-cost section. Avoid templates with decorative headers or extra columns that duplicate statement data. The best ones are plain tables with clear labels. Print them on matte paper if possible; glossy paper smudges quickly and makes handwriting hard to read after a few weeks.
The method works because it is friction-light and feedback-immediate. It will not fix a spending problem by itself. But it gives you the visibility that most people never get because their data sits buried in app dashboards they rarely open. Consistency beats sophistication every time.