Understanding the Derivative Before You Ever Write a Line of Code
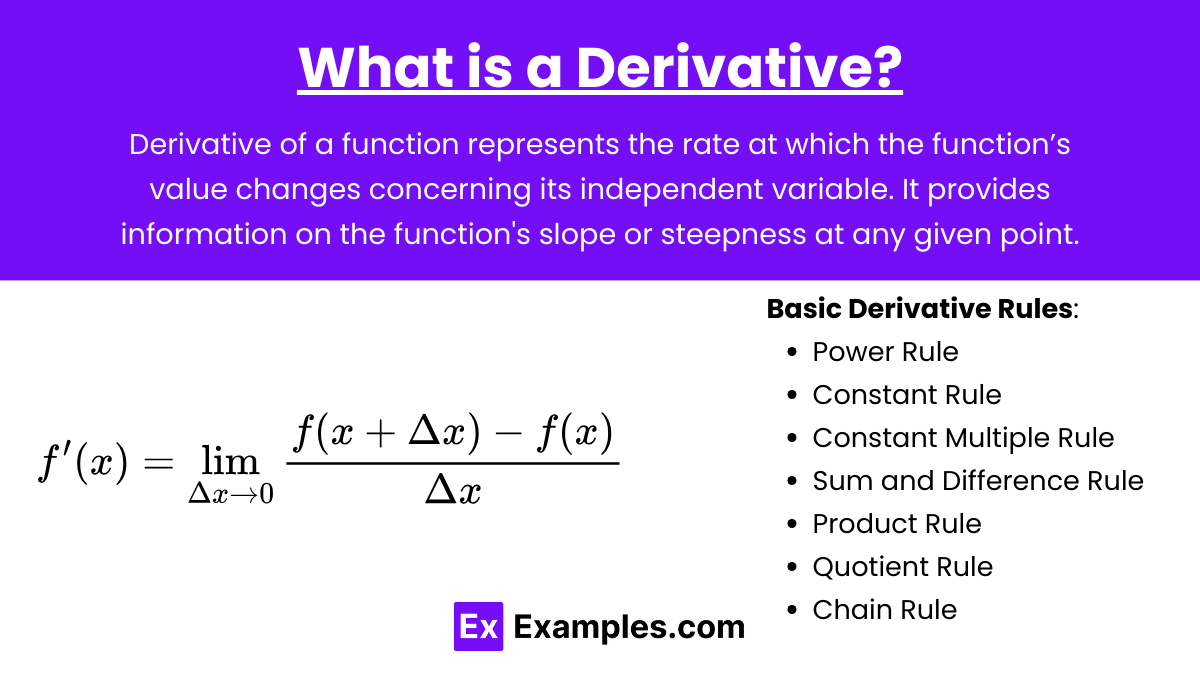
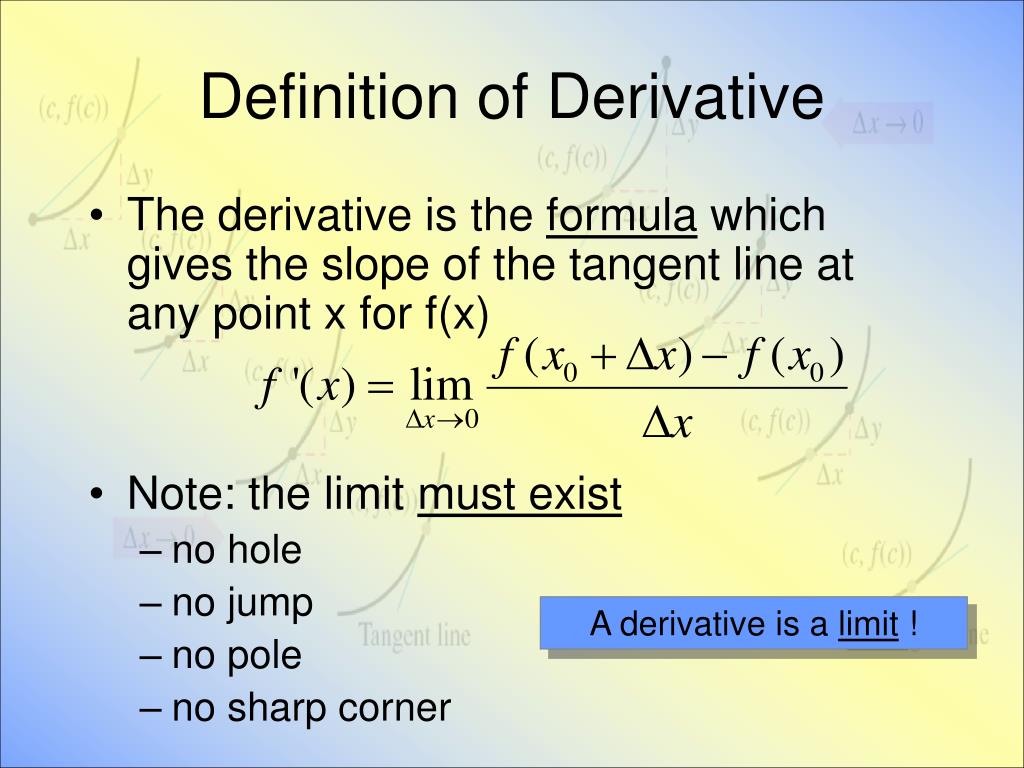
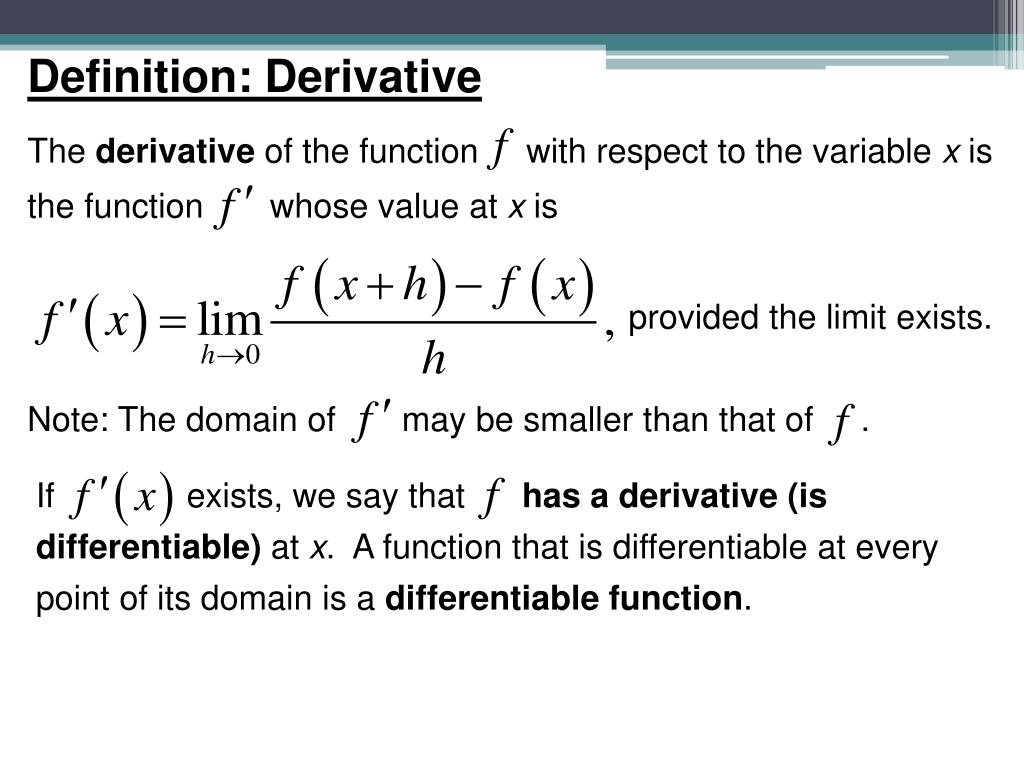
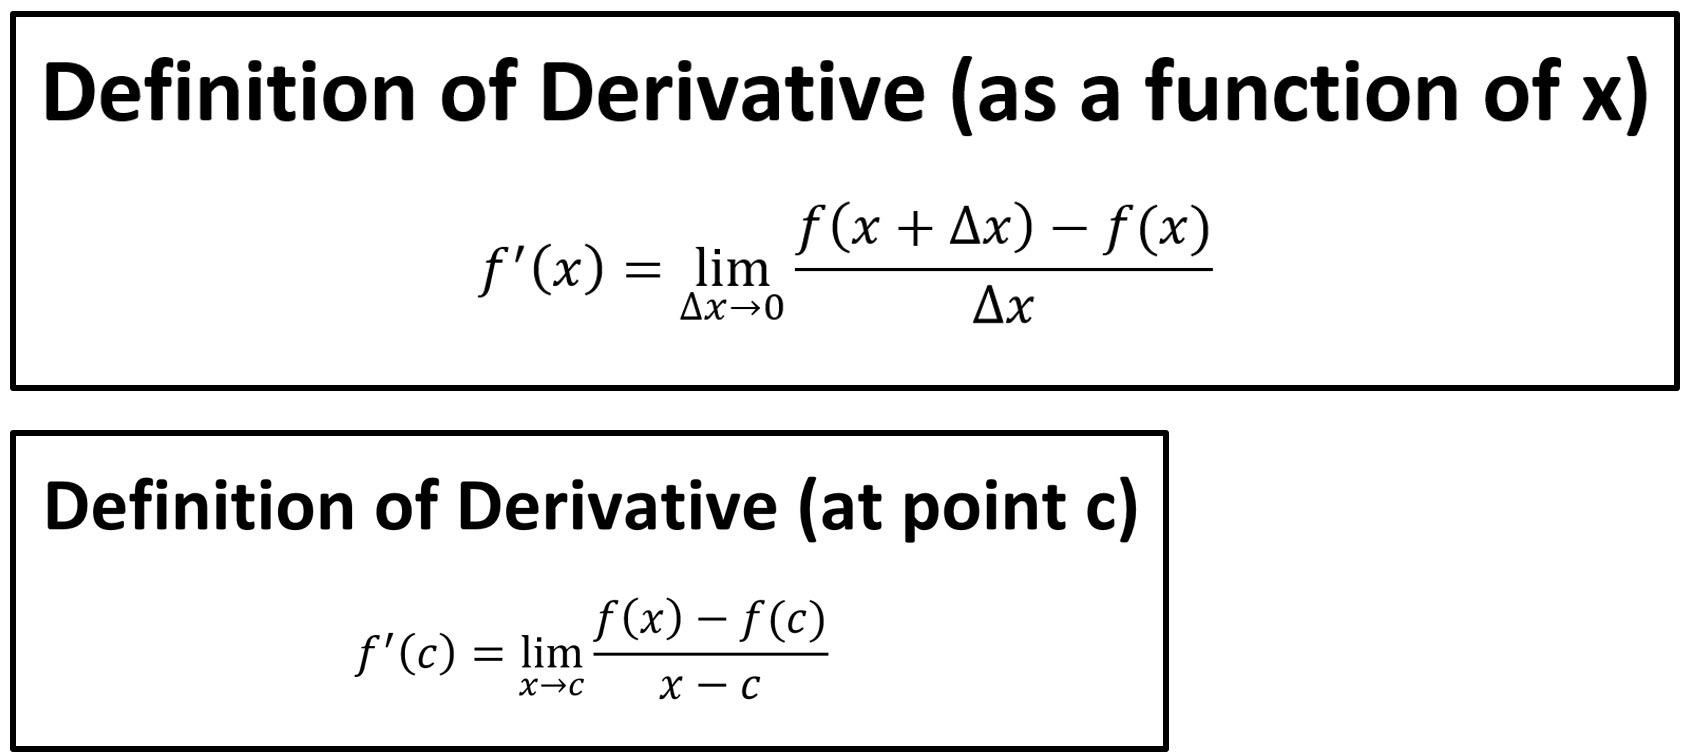
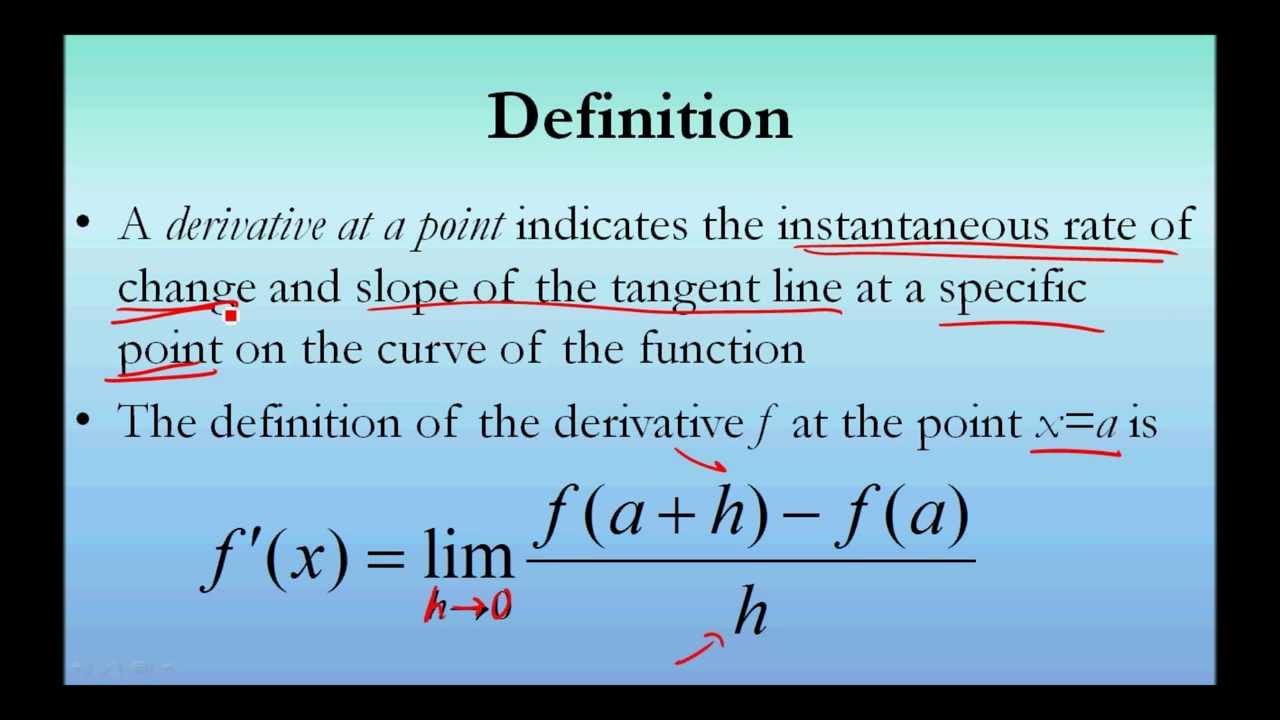
A derivative is just a way to measure how something changes at one specific point. That's it. When people talk about it in math, computer science, or finance, they're all pointing at the same basic idea—rate of change. The formal definition looks like this: the derivative of a function f at a point x is the limit of (f(x+h) - f(x)) / h as h gets closer and closer to zero. In practice, you rarely compute that limit by hand anymore unless you're taking an exam. Instead, you use rules and tables. The reason this concept matters everywhere is that almost any system that evolves over time or depends on changing inputs has a derivative hiding in it. Population growth models, stock option pricing, neural network training, heat diffusion—all of it traces back to asking the same question: if I nudge the input slightly, how much does the output shift?
Definition Of A Derivative in Plain Terms
The Definition Of A Derivative comes down to finding the slope of a function at a single instant. Not the average slope between two points, but the exact slope at one coordinate. You get there by shrinking the gap between two points until they're essentially the same point. The formal limit definition I showed above captures that precisely. Here's what the textbook version doesn't make obvious: a derivative is only useful when the function is smooth at the point you're looking at. If there's a sharp corner or a break in the curve, the derivative doesn't exist there. Period. This trips people up constantly.
How to Actually Compute One
You don't need to evaluate limits every time. There are established rules that let you skip the heavy lifting. The most important ones are the power rule, the product rule, the quotient rule, and the chain rule. Master these and you can handle most standard functions without reaching for a calculator. For any function like x raised to some exponent n, you bring the exponent down and subtract one from the power. So the derivative of x to the fifth is five times x to the fourth. Simple enough. If n equals zero and you have a constant, the derivative is zero because constants don't change. That's also worth keeping straight—people forget that sometimes. This one shows up when you nest functions inside each other. Take the outer function, differentiate it treating the inner part as a single variable, then multiply by the derivative of the inner function. For example, the derivative of the sine of three x squared works by first differentiating sine to get cosine, then multiplying by the derivative of three x squared, which is six x. The answer is six x times cosine of three x squared. This rule is non-negotiable if you're doing anything beyond the simplest problems.
Get the Full Details
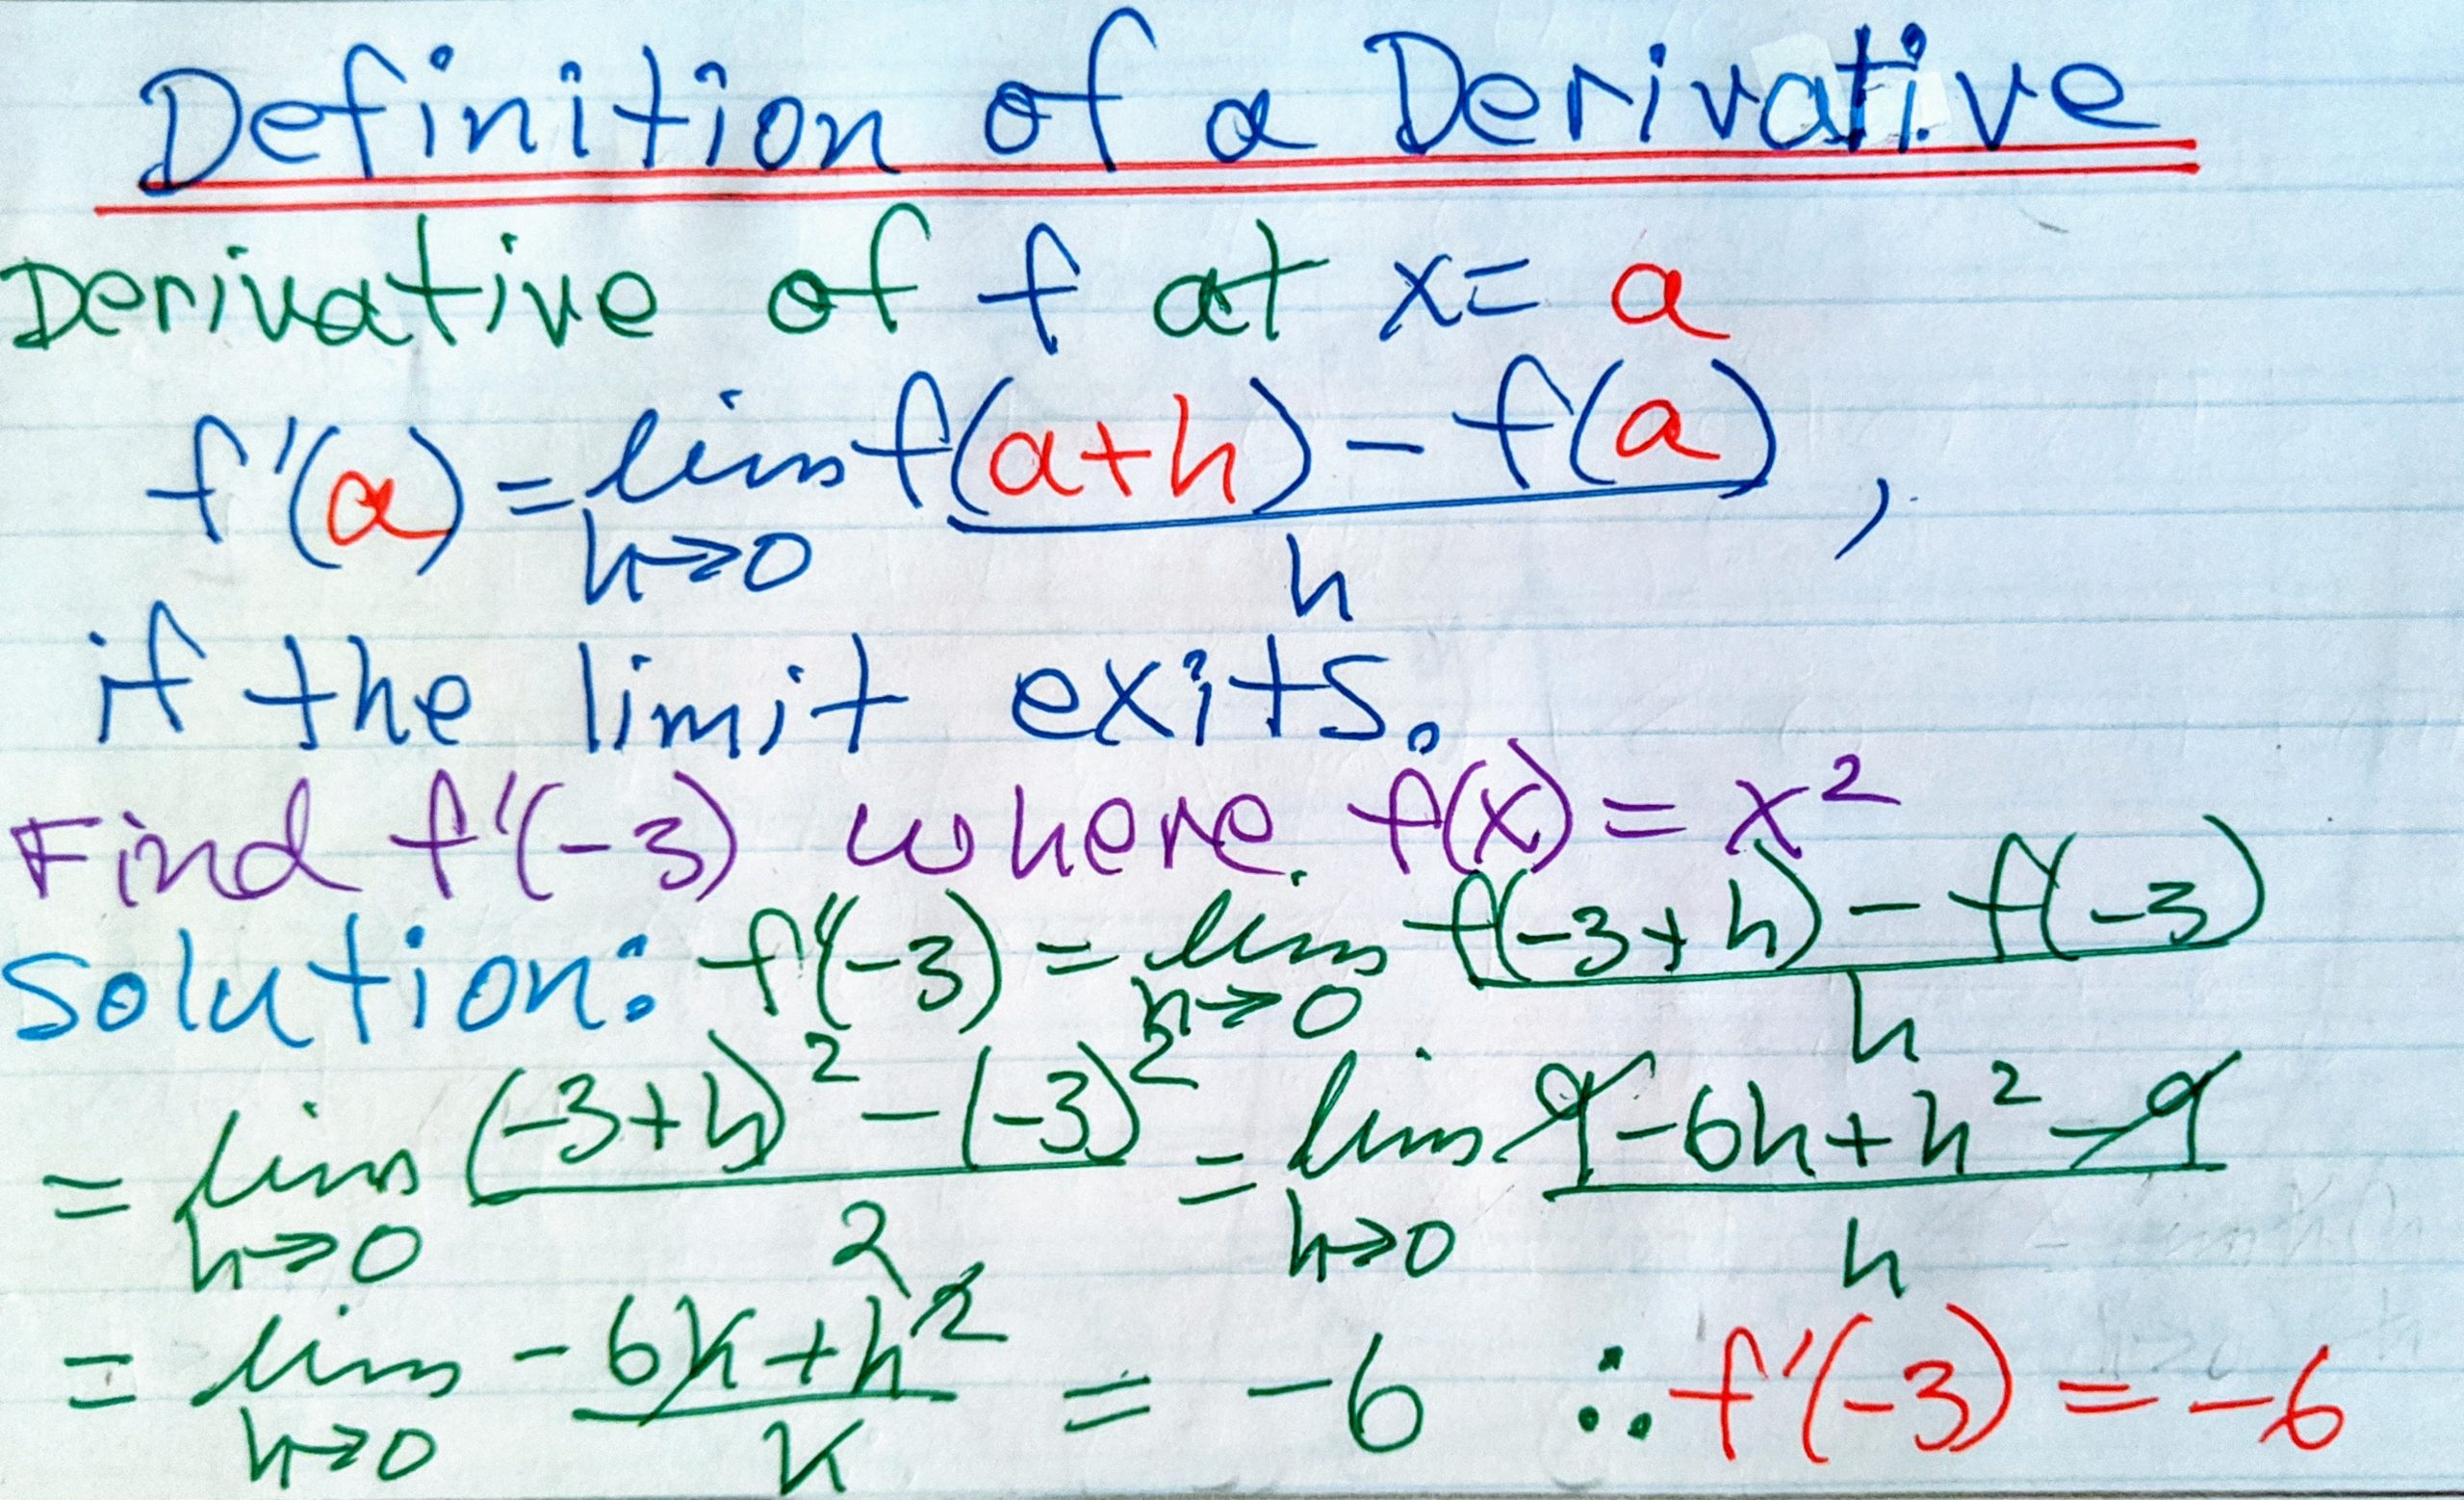
When two functions multiply together, you can't just differentiate each part separately and multiply the results. That gives the wrong answer. Instead, you take the first function times the derivative of the second, plus the derivative of the first times the second function. The order doesn't matter for the final result, but keeping track of which is which helps avoid mistakes while you're working. There's a short list of standard derivatives you'll reach for constantly. The derivative of e to the x is e to the x. That's unusually neat and turns out to be important in growth models. The derivative of the natural logarithm of x is one over x. Trigonometric functions follow their own patterns—sine becomes cosine, cosine becomes negative sine, tangent becomes secant squared. Memorizing these saves you from reconstructing them each time. I spent too many hours in college redoing derivations that I already had in a table because I refused to look it up. Don't do that. Keep a reference sheet. The time you save compounds, literally.
A Practical Example
Let's work through something that actually appears in real analysis. Say you have f of x equal to two x cubed minus five x squared plus three x minus seven. You differentiate term by term using the power rule on each one. Two times three gives you six x squared. Negative five times two gives you negative ten x. Three becomes three. Negative seven disappears since it's a constant. The derivative is six x squared minus ten x plus three. If you plug in x equals two, the derivative at that point is six times four minus twenty plus three, which equals seventeen. That means at the coordinate x equals two, the function is rising at a rate of seventeen units per unit of x. Not every function plays nice. The absolute value function has a corner at zero, so it has no derivative there. Step functions are discontinuous, which means the limit definition collapses. Functions that oscillate infinitely near a point, like sine of one over x near zero, present similar problems. When you encounter these cases, the derivative simply doesn't exist at that point, and you need to work around it. In applied settings, this matters more than you might expect. I once worked on a project involving threshold-based pricing models where the cost function switched abruptly at certain volume levels. The derivative didn't exist at those switching points, which broke standard optimization routines that assumed smoothness. The workaround was to treat the discontinuity as a boundary condition and evaluate the objective function separately on each side of the threshold, then compare the results manually. It added time to the process but avoided incorrect assumptions about differentiability.
Another edge case I ran into involved options pricing. The payoff diagram for a call option has a kink at the strike price. Standard Greeks like delta assume smooth payoffs, so near expiration and right around the strike, numerical derivatives can jump unpredictably. I ended up switching to a smoothed approximation of the payoff function for the narrow region around the strike, then fell back to exact formulas once I moved away from that zone. The transition wasn't pretty, but it prevented garbage numbers from contaminating the rest of the model.
What Derivatives Are Good For
Optimization is the biggest use case. Finding maxima and minima of a function comes down to locating where its derivative equals zero. Not every zero is a maximum or minimum—you have to check the second derivative or test neighborhoods—but the derivative gives you the starting points. Gradient descent in machine learning is just repeated application of this principle across multiple dimensions. Differentials and linear approximation are another major application. If you know the derivative at a point, you can estimate the function's value nearby using a tangent line. This is how engineers do quick sensitivity analysis without rerunning entire simulations. A small change in input multiplied by the derivative gives you the approximate change in output. In physics, velocity is the derivative of position with respect to time, and acceleration is the derivative of velocity. In economics, marginal cost is the derivative of total cost. The pattern repeats across disciplines because the underlying question is always the same.
When to Reach for Numerical Methods
Sometimes you can't differentiate a function analytically. Maybe it comes from a simulation, maybe it's defined by experimental data, maybe it's too complex for symbolic manipulation. In those cases you approximate the derivative numerically. The simplest approach is the forward difference: divide the difference between f at x plus h and f at x by h, using a small value like zero point zero zero one. Central differences are more accurate because they average the slope from both sides. Numerical differentiation introduces truncation error from the finite step size and round-off error from floating-point arithmetic. Choosing h too large amplifies truncation error. Choosing h too small amplifies round-off error. The sweet spot usually lands somewhere between one ten-thousandth and one millionth for double-precision arithmetic, but it depends on your function. If you need automation, libraries like Autograd handle this elegantly by applying the chain rule through your computational graph rather than approximating numerically.
The Bottom Line
A derivative measures instantaneous rate of change. You compute it using rules rather than limits in everyday work. It exists only where a function is smooth. It breaks at corners and discontinuities. It powers optimization, approximation, and modeling across nearly every quantitative field. The math is straightforward once you internalize the core rules and stop trying to derive everything from first principles on the fly.