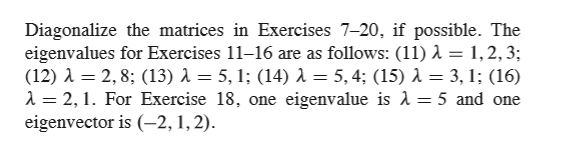
Diagonalizing Matrices: The Practical Way
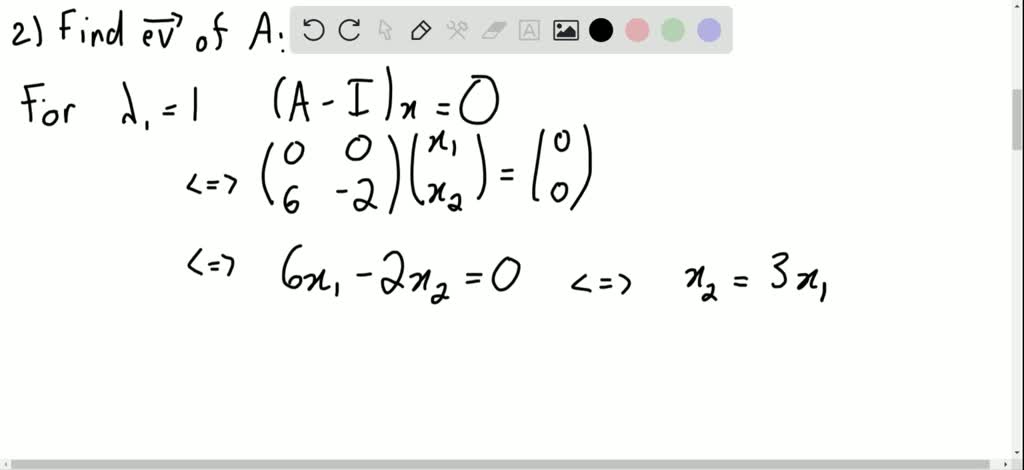
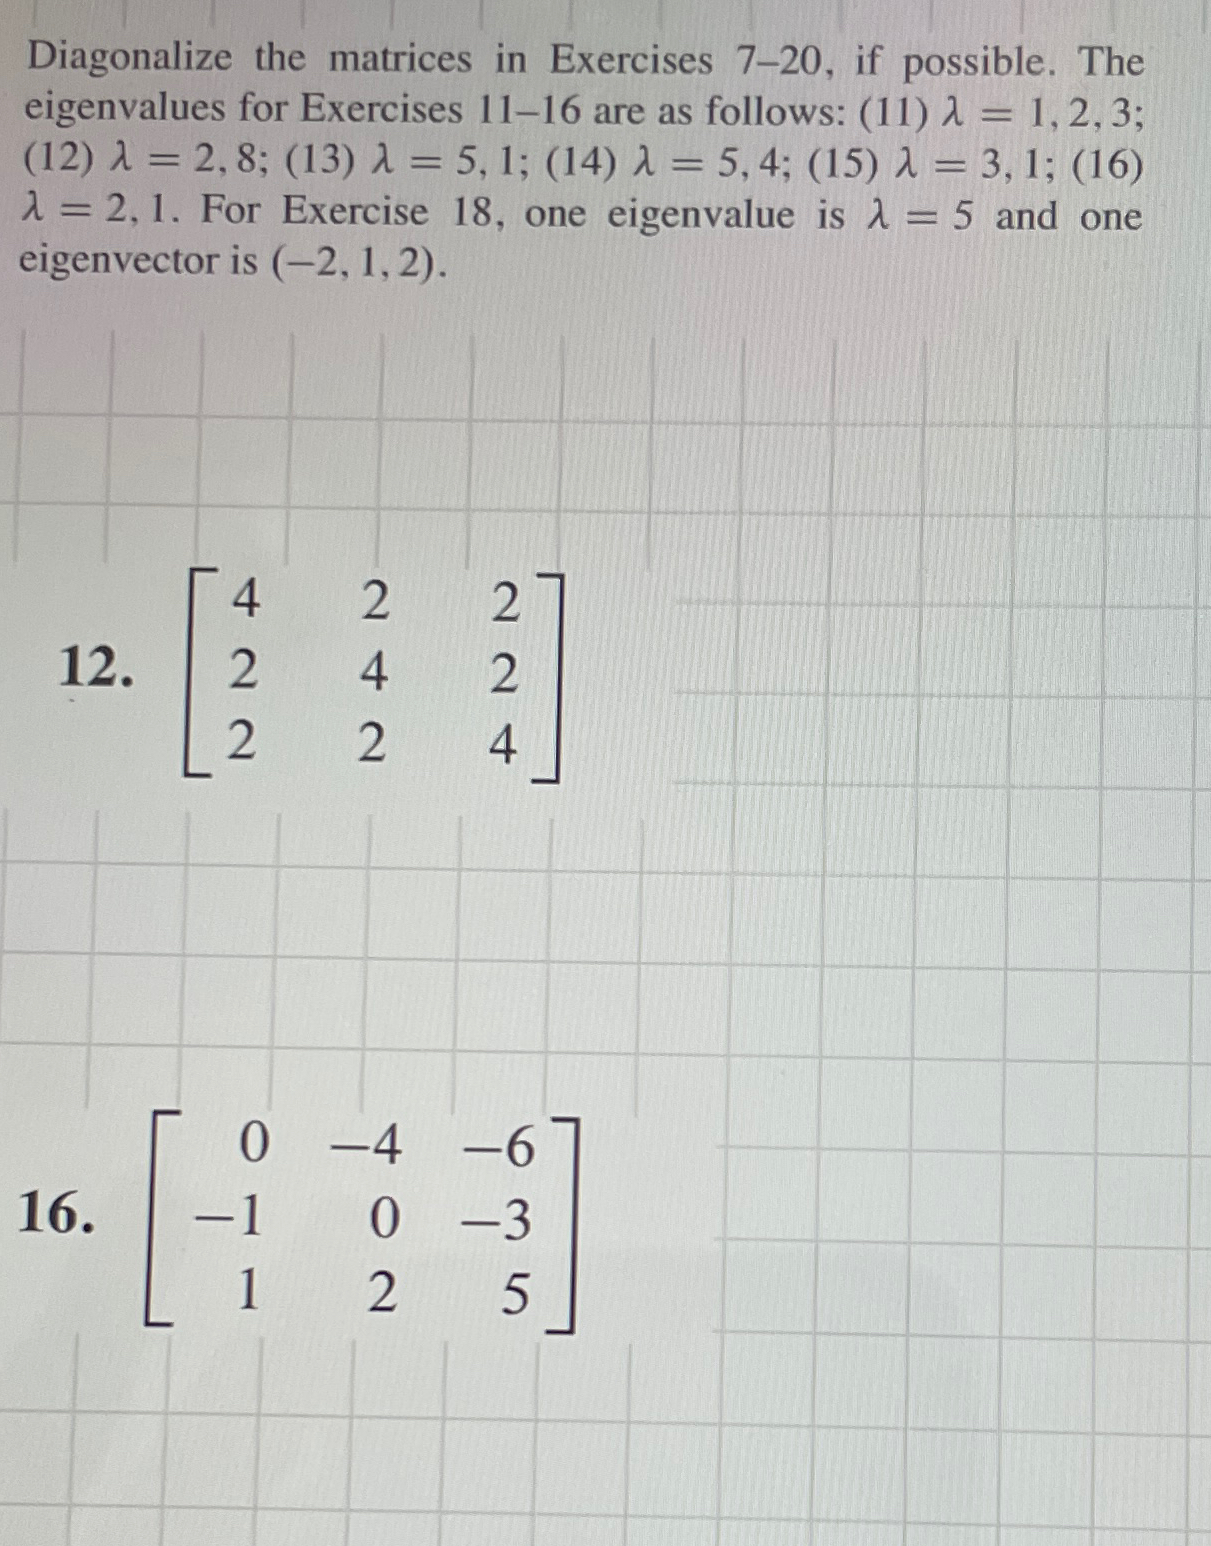
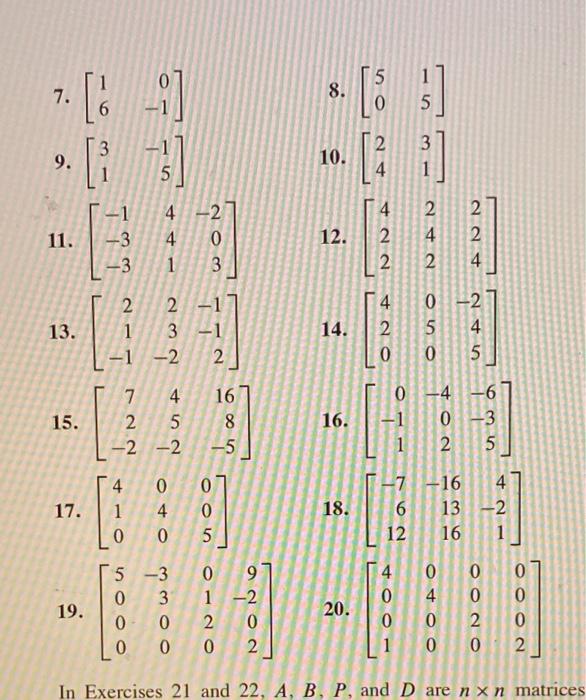
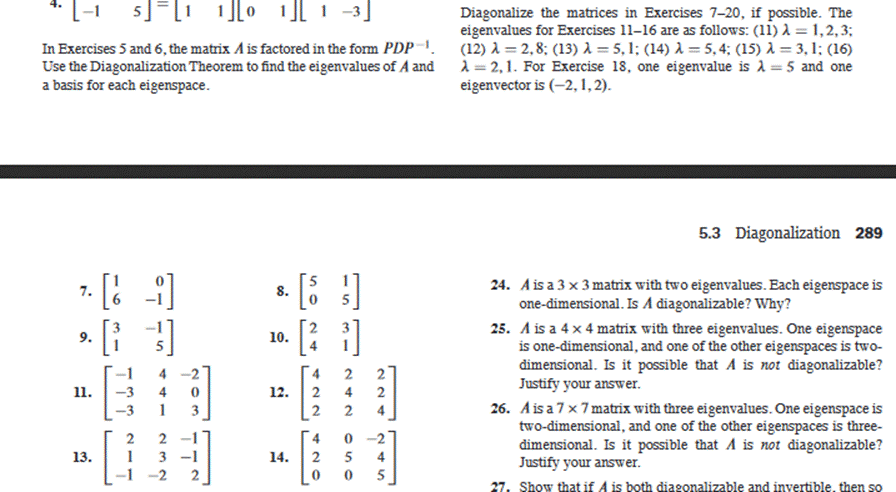
Most linear algebra textbooks throw you into exercises 7 through 20 with matrices that look deceptively simple, then expect you to figure out whether they're diagonalizable and do the work if they are. Here's how it actually goes down, stripped of textbook polish. The method is straightforward in theory. Find the eigenvalues by solving det(A - I) = 0. Then for each eigenvalue, find its eigenvectors by solving (A - I)v = 0. If the total number of linearly independent eigenvectors equals the size of the matrix, it diagonalizes. P is your eigenvector matrix, D is your diagonal eigenvalue matrix, and A = PDP^(-1).
Diagonalize The Matrices In Exercises 7 20 If Possible
The word "if possible" is doing heavy lifting here. That's where most students lose points. Not every matrix is diagonalizable. I've seen cases where the characteristic polynomial gives you distinct eigenvalues — which guarantees diagonalizability — and then the eigenvector calculations produce fractions so ugly you second-guess yourself into making an arithmetic error. Happened to me last semester during a graded quiz. 3x3 matrix, eigenvalues came out clean, but the eigenvector for = 4 required row-reducing a matrix with denominators like 7/13. I caught it by switching to an augmented matrix approach with fractions kept as improper fractions instead of decimals. Decimals introduced rounding errors that made the rows look dependent when they weren't. Here's a counter-intuitive thing nobody emphasizes enough: repeated eigenvalues don't automatically disqualify a matrix. The multiplicity matters, but geometric multiplicity is what you actually need to check. A 3x3 matrix with = 2 appearing three times in the characteristic polynomial might still be diagonalizable if it has three independent eigenvectors for = 2. That means the null space of (A - 2I) has dimension 3, which only happens if A - 2I is the zero matrix. So A = 2I. Anything less than that and you're looking at a defective matrix. I can't count how many students assumed a repeated eigenvalue meant the answer was "not diagonalizable" without actually computing the eigenspace dimension. Another thing: symmetric matrices are always diagonalizable, and the eigenvectors can be chosen orthogonal. If you're working with a symmetric matrix, you can use that as a checkpoint. After you find your P matrix, check whether P^T equals P^(-1). If it does, your work is consistent. If it doesn't, you made a mistake somewhere, because a real symmetric matrix's eigenvectors for distinct eigenvalues are guaranteed orthogonal. This catches computational errors faster than re-doing the entire problem.
For the actual exercises, start with the 2x2 cases. They're quick wins and build confidence. The characteristic polynomial is at most quadratic, so the quadratic formula handles it. Watch for the case where the discriminant is negative — that means complex eigenvalues, and over the reals, the matrix isn't diagonalizable. Over the complex field, it is, but most undergraduate courses stop at real diagonalization. When you get to 3x3 matrices, the characteristic polynomial becomes cubic. Don't panic. If the problem is from a textbook exercise, the eigenvalues will almost always be integers or simple fractions. Factor by rational root theorem — test ±1, ±2, ±3, etc. against the constant term. Once you find one root, polynomial division reduces it to a quadratic. This saves you from trying to factor a cubic directly, which is where people waste twenty minutes. For larger matrices or cases where the characteristic polynomial doesn't factor nicely, numerical methods like the QR algorithm are what actually get used in practice. But for textbook exercises, exact arithmetic is expected. Keep everything as fractions. Don't convert to decimals until the final step, and even then, only if the problem asks for it.
Get the Full Details
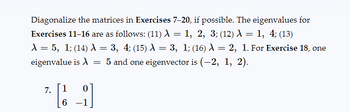
If a matrix turns out not to be diagonalizable, you can still put it in Jordan canonical form, but that's a different topic and your textbook exercises probably won't ask for it. The answer "not diagonalizable" is sufficient, but you should be able to show why by demonstrating that the geometric multiplicity is less than the algebraic multiplicity for at least one eigenvalue. One practical tip: organize your work in columns. Each eigenvalue gets its own section. Write the eigenvalue, show the characteristic equation solution, write the matrix A - I, row reduce it, identify the free variables, and write the eigenvectors explicitly. When you come back to grade your own work or check an answer key, this structure lets you find exactly where a mistake happened instead of re-deriving everything from scratch. The exercises in the 7-20 range typically progress from easy to harder, so if you get stuck on one, step back and do the simpler ones first. The pattern becomes obvious quickly. Most of them test whether you understand the difference between algebraic and geometric multiplicity, or whether you catch complex eigenvalues in a real matrix. Those are the two traps that appear repeatedly.