What You're Actually Looking At
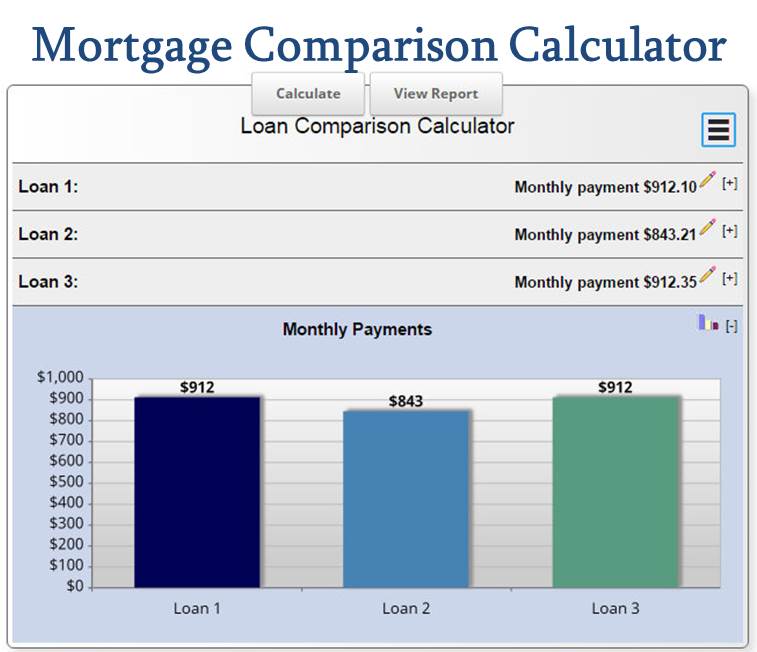
A Difference In Mortgage Rates Calculator is just a tool that compares two or more mortgage rates side by side and shows you the numerical gap between them. It sounds simple enough, but the way people use these calculators usually reveals they don't fully understand what the output actually means for their monthly payment or total cost over the life of the loan. I built and maintained rate comparison tools for a living for about eight years. The most common mistake I saw was people plugging in a 4.5% rate against a 4.75% rate and being surprised when the calculator said the difference was only about $89 a month on a $400,000 loan. They expected more drama from a quarter-point spread. That's normal. Most borrowers don't intuitively grasp how small rate changes compound across 30 years until they see it laid out.
Using the Difference In Mortgage Rates Calculator
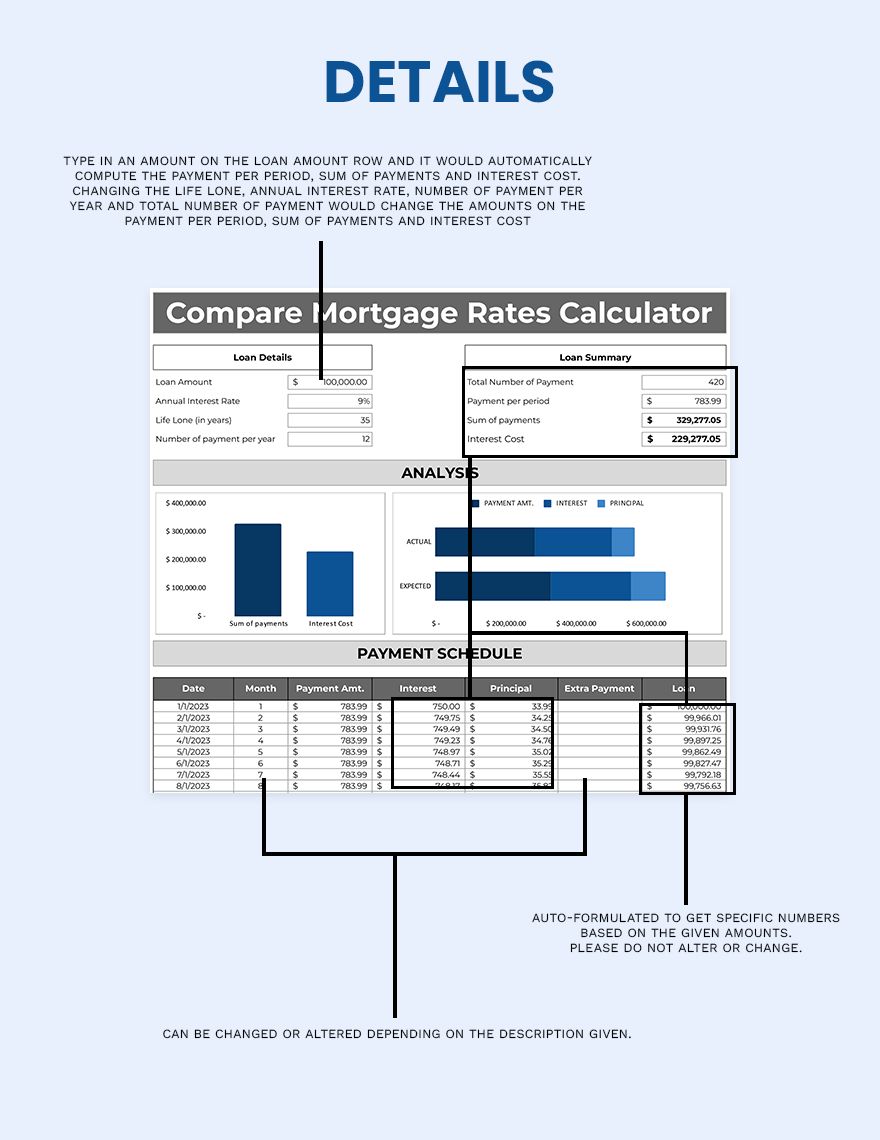
The basic process is straightforward. You enter your loan amount, the term (15 years, 30 years, whatever you're looking at), and the two rates you want to compare. Some versions of the calculator also ask for your property tax situation or whether you're including escrow. The more fields you fill in, the more realistic the output becomes. Here's where it gets tricky though. I remember working with a client back in 2019 who was comparing a 4.125% fixed-rate loan against a 3.75% adjustable-rate mortgage. The calculator showed a $67 monthly difference in his favor on the ARM. He almost took the ARM without considering the adjustment cap. The five-year teaser rate looked great on paper, but once the rate reset, his payment jumped by nearly $200 a month. The calculator didn't flag that because it wasn't built to model adjustment scenarios. I had him run a separate projection using the fully indexed rate plus the cap schedule, and the picture changed completely. That's a gap most online calculators don't cover, and it's the kind of thing that catches people off guard. You should always double-check the calculator's assumptions. Some tools assume principal and interest only. Others roll in taxes and insurance by default. If you're comparing results from two different calculators, make sure they're using the same inputs and the same payment structure. A $40 difference in monthly payment between two calculators often just means one included escrow and the other didn't.
The output will typically show you the monthly payment difference, the total interest difference over the loan term, and sometimes the break-even point if you're deciding between a higher-rate loan with lower points versus a lower-rate loan with higher points. That break-even analysis is honestly the most useful part of any rate comparison tool. It tells you how long you need to hold the loan before the cheaper rate actually saves you money after factoring in upfront costs.
Get the Full Details
What The Numbers Don't Tell You
I need to be straight with you about the limitations here. A mortgage rate difference calculator is a mathematical exercise, not a financial decision tool. It can tell you that 4.25% costs you $1,432 more per month than 3.75%, but it cannot tell you whether either rate is actually good for your situation. That depends on your credit score, your debt-to-income ratio, the lender you're working with, the market conditions on the day you apply, and a dozen other variables that no calculator can account for. One thing that surprises people is that the rate difference doesn't scale linearly. Going from 5% to 4.5% saves you more money than going from 5.5% to 5%, even though both are half a point apart. The math behind it is straightforward — it's the way amortization works — but it's not obvious unless you've run the numbers enough times. On a $500,000, 30-year loan, the difference between 5% and 4.5% is roughly $263 per month. The difference between 5.5% and 5% is only about $234. Half a point at the lower end of the rate spectrum hits harder because more of your early payments go toward principal instead of interest. Another thing worth noting is that points and rates are inversely related in a way that most people don't appreciate. Paying one point to drop your rate by 0.25% sounds reasonable until you do the math and realize you'd need to hold the loan for nearly seven years to break even. If you're planning to move or refinance in five years, that purchase is a net loss. The calculator will show you the monthly savings, but it won't automatically tell you whether buying down the rate makes sense for your actual timeline.
There's also the issue of rate locks. The rate you see quoted today might not be the rate you close at. Most lenders lock rates for 30 to 60 days, but during volatile periods — and we saw this clearly in 2022 and again in 2023 when the Fed was moving aggressively — rates can shift significantly within a single lock period. A calculator showing a 0.375% difference between two loans is only meaningful if both rates are locked simultaneously. If you're comparing a locked rate against a quoted float, you're comparing fiction against reality. If you want something more thorough than an online Difference In Mortgage Rates Calculator, the best approach is to get two simultaneous loan estimates from different lenders. The TRID rule requires them to use the same format, so you can compare line items directly. A calculator is fine for quick sanity checks, but it will never replace an actual loan estimate. The differences between lender fees, underwriting overlays, and discount points are the things that actually matter, and those don't show up in any simple rate comparison tool.