How to Build a Discounted Cash Flow Calculator That Actually Works
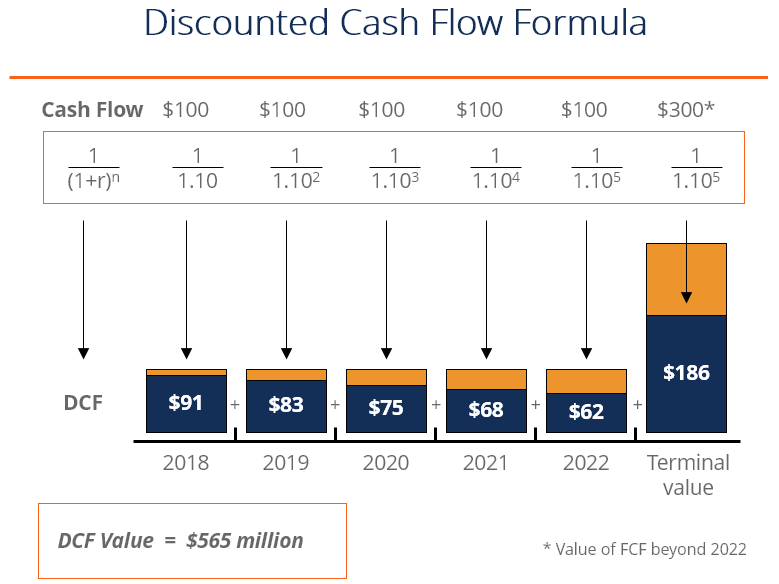
I spent about three years building financial models for infrastructure projects before I ever bothered making my own tool. The ones you find online are fine for quick estimates, but they fall apart the moment you have irregular cash flows, changing discount rates, or tax treatments that shift year to year. So I built something simple. Here is how it works and where the usual traps are. A discounted cash flow calculator takes a series of future cash flows and a discount rate, then works backwards to tell you what those numbers are worth today. The math is basic: you divide each cash flow by (1 plus the discount rate) raised to the power of the period. Sum all of those present values and you have your answer. That is the entire model. Everything else is just dealing with the messiness of real data. The formula looks like this in practice: PV = CF / (1 + r)^n. Where CF is the cash flow for a given period, r is your discount rate, and n is the period number. If you throw this into a spreadsheet and drag the formula down, you get results fast. The problem is never the formula. It is everything around it.
Building the Spreadsheet Model
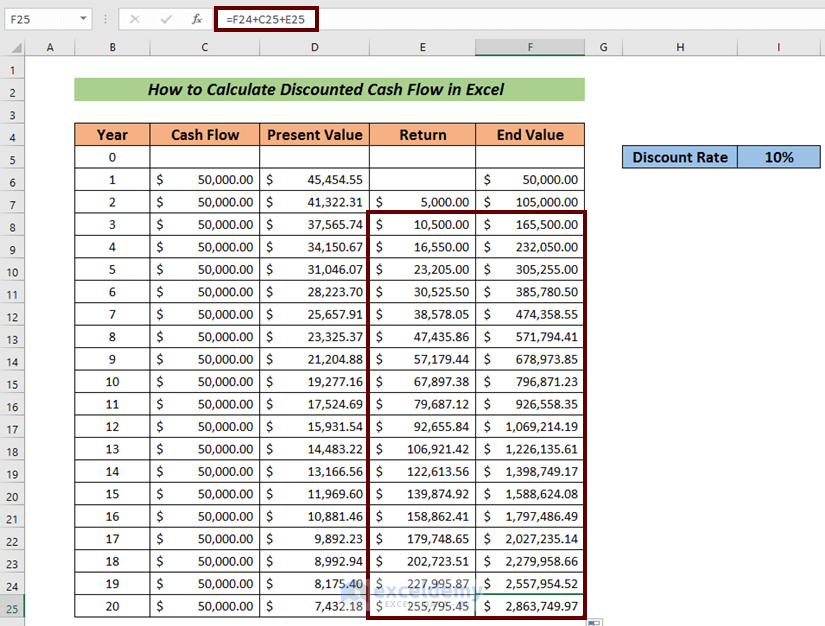
I start every model the same way. Column A is the period. Column B is the cash flow for that period. Column C is the discount rate for that period. Column D is the present value calculation. That is it. Ten rows of headers, ten rows of assumptions, and then the actual projections below that. Keeping the assumptions separate from the calculations matters more than people think. When a client asks why the valuation changed by twelve percent after you revised the discount rate from eight to nine, you need to be able to point at a single cell and say here it is. If the rate is buried inside a nested formula, you are going to spend an hour finding it. For the present value column, the formula is straightforward. In the first data row it would look like =B2/(1+C2)^A2. Drag it down. If you have a terminal value, add another row and discount that back as well. The terminal value itself is usually calculated using a perpetuity growth model: terminal cash flow divided by (discount rate minus growth rate). Keep that separate. Do not mix it into your operating cash flow column.
Using a Discounted Cash Flow Calculator in Practice
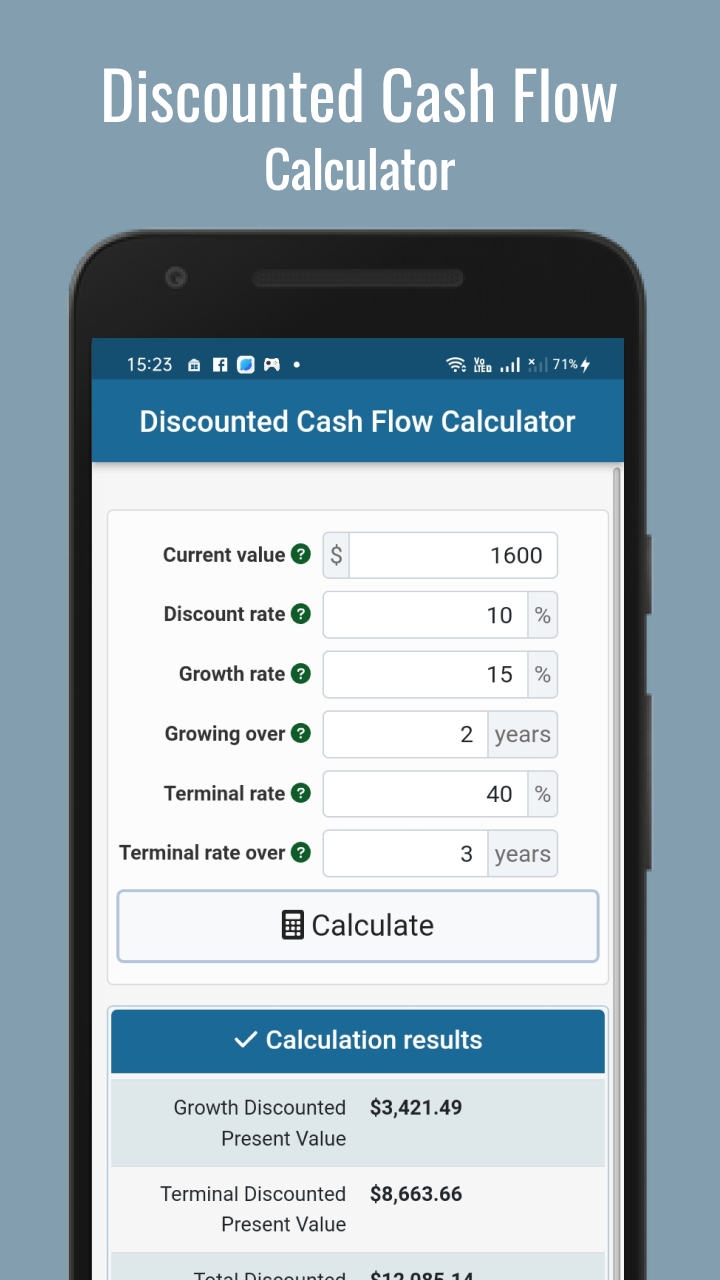
Most people I work with use an online Discounted Cash Flow Calculator for quick decisions. These are fine for screening investments or rough comparisons. I use them myself when I need a sanity check before building a detailed model. But there is a real limit to what they can do. I had a project last year where the cash flows were negative for the first three years, turned positive in year four, and then declined gradually through year twelve. The online calculator I was using assumed uniform positive cash flows and gave me a valuation that was off by nearly forty percent because it could not handle the sign changes properly. I ended up building a custom sheet with conditional logic that flagged periods where the discount rate needed to adjust based on risk phase. That took about twenty minutes and saved me from making a bad recommendation. Another thing nobody tells you about these tools: they rarely let you model different discount rates for different periods. In reality, early-stage projects carry more risk and should be discounted more heavily than mature ones. Using a single rate across the entire timeline either understates or overstates the present value depending on your cash flow profile. If your cash flows front-load, a flat rate makes the project look better than it is. If they back-load, it looks worse. The fix is simple enough. Just use a separate discount rate column instead of a single input cell.
Get the Full Details

Common Mistakes That Make the Numbers Wrong
The biggest mistake I see is mixing nominal and real cash flows. If your discount rate is nominal, your cash flows must be nominal too. If your discount rate is real, strip inflation out of your cash flows. Mixing them gives you a number that looks precise but is meaningless. I have seen this error in models from three different consulting firms. It is surprisingly common because neither party catches it during review. The second mistake is forgetting about timing within the period. Most models assume cash flows occur at the end of each year. In reality, many projects generate revenue evenly throughout the year or front-load their receipts. The difference is small for annual models but noticeable when you are working with monthly data or high discount rates. A one-period timing shift on a ten-year project with a twelve percent discount rate can change the net present value by roughly three to five percent. That sounds small until the deal is worth hundreds of millions. There is also the tax treatment issue. Some calculators let you enter pre-tax cash flows and apply a flat tax rate. Real projects have depreciation schedules, loss carryforwards, and tax credits that shift the actual tax liability year to year. A flat rate on pre-tax flows is a shortcut that works for back-of-the-envelope math but falls apart under scrutiny. If someone is going to bet money on your numbers, they will want to see the tax calculations laid out separately.
Advanced Nuance: WACC vs. Project-Specific Rates
Weighted average cost of capital is the standard discount rate people reach for. It is easy to calculate if you have the capital structure and the cost of equity and debt figures. But WACC assumes the project has the same risk profile as the company overall. That is almost never true. A company might have a WACC of nine percent but be evaluating a new venture in a completely different industry with higher risk. Using the corporate WACC for that project overstates its value. The workaround is to build in a risk-adjusted premium. Add two to four percentage points depending on how different the project is from the core business. It is not exact. Nothing about this process is exact. But it is better than pretending the numbers are more precise than they actually are. Another thing worth noting is the sensitivity of the output to the discount rate. Small changes in the rate produce disproportionately large changes in present value, especially for long-duration projects. Moving from eight to ten percent on a twenty-year cash flow stream can cut the valuation by nearly half. This is not a flaw in the method. It is just how compound discounting works. The implication is that your discount rate assumption matters far more than your cash flow assumptions. Spend more time defending the rate than defending the revenue projections. Revenue projections are guesswork anyway. The discount rate is the lever you control.
When the Model Breaks Down Completely
Discounted cash flow analysis fails in situations that are hard to spot until you are already deep into the model. One scenario is when the cash flows are deeply uncertain and the uncertainty grows over time rather than shrinking. Traditional DCF assumes you can reasonably estimate future cash flows. If you cannot, no amount of spreadsheet gymnastics will save you. In those cases, real options analysis or scenario-based modeling is more appropriate. Another failure mode is when the asset has no clear ending. Perpetual businesses are hard to value with a terminal value because the growth rate assumption becomes the dominant driver. A one percent change in your terminal growth rate from three to four percent can swing the total valuation by fifteen to twenty percent. That is not a margin of error. That is the entire result. If you are dealing with a project that has uncertain termination timing, consider building in an option to abandon or expand. Standard DCF treats the project as a commitment. It does not account for the ability to walk away or scale up when conditions change. I once worked on a renewable energy project where the cash flows depended entirely on regulatory subsidies that were up for renewal every five years. The base case DCF assumed the subsidies continued indefinitely. The model looked healthy. The reality was that each renewal cycle represented a binary risk event. We had to layer in a Monte Carlo simulation to get anywhere near useful numbers. The DCF alone was misleading in a way that was not obvious without deeper analysis.
Practical Tips for Building Your Own Model
Keep your spreadsheet clean. Use color coding sparingly but consistently. Blue cells for inputs. Black cells for calculations. This is an old convention but it prevents errors when multiple people are looking at the same sheet. Label every assumption clearly. If you come back to this model six months from now, you should not have to guess what a number represents. Include a summary page that shows the key outputs and the main assumptions driving them. This saves time during reviews and makes it easier to spot when a single assumption is driving most of the variance. Document your discount rate source. Write down where the rate comes from. Is it based on observed market data? Is it a company target? Is it a best guess? The difference matters and reviewers will ask. I usually include a small footnote section in every model that explains the rate derivation in two or three sentences. It takes about thirty seconds to write and saves ten minutes of explanation later. Run a sensitivity table at the end. Vary the discount rate and the terminal growth rate across a reasonable range and show how the valuation moves. This takes about five minutes to set up and gives you a clear picture of where the model is most fragile. If the valuation swings wildly with small rate changes, that is information in itself. It tells you which assumption needs the most defense.