Setting Up a Home Accounting System That Doesn't Fall Apart After Three Months
I spent about four years running a small contracting business out of my garage before I figured out what actually worked for bookkeeping. The standard templates you find online assume you're either a sole prop with five transactions a week or a corporation with accounting staff. Most people are somewhere in between, which is why Diy Accounting Examples tend to look correct on paper and fail immediately in practice. The core problem most DIY setups hit is category drift. You create twelve expense categories for a real estate side business, then three months later you're unsure whether a new software subscription goes under "Office Supplies" or "Professional Fees," so you pick one arbitrarily. By December, your Profit & Loss report is useless because half your expenses are miscategorized. The fix is simpler than people think: build your chart of accounts around how money actually moves through your life, not how an accountant would want it organized.
Essential Diy Accounting Examples for Real-World Setup
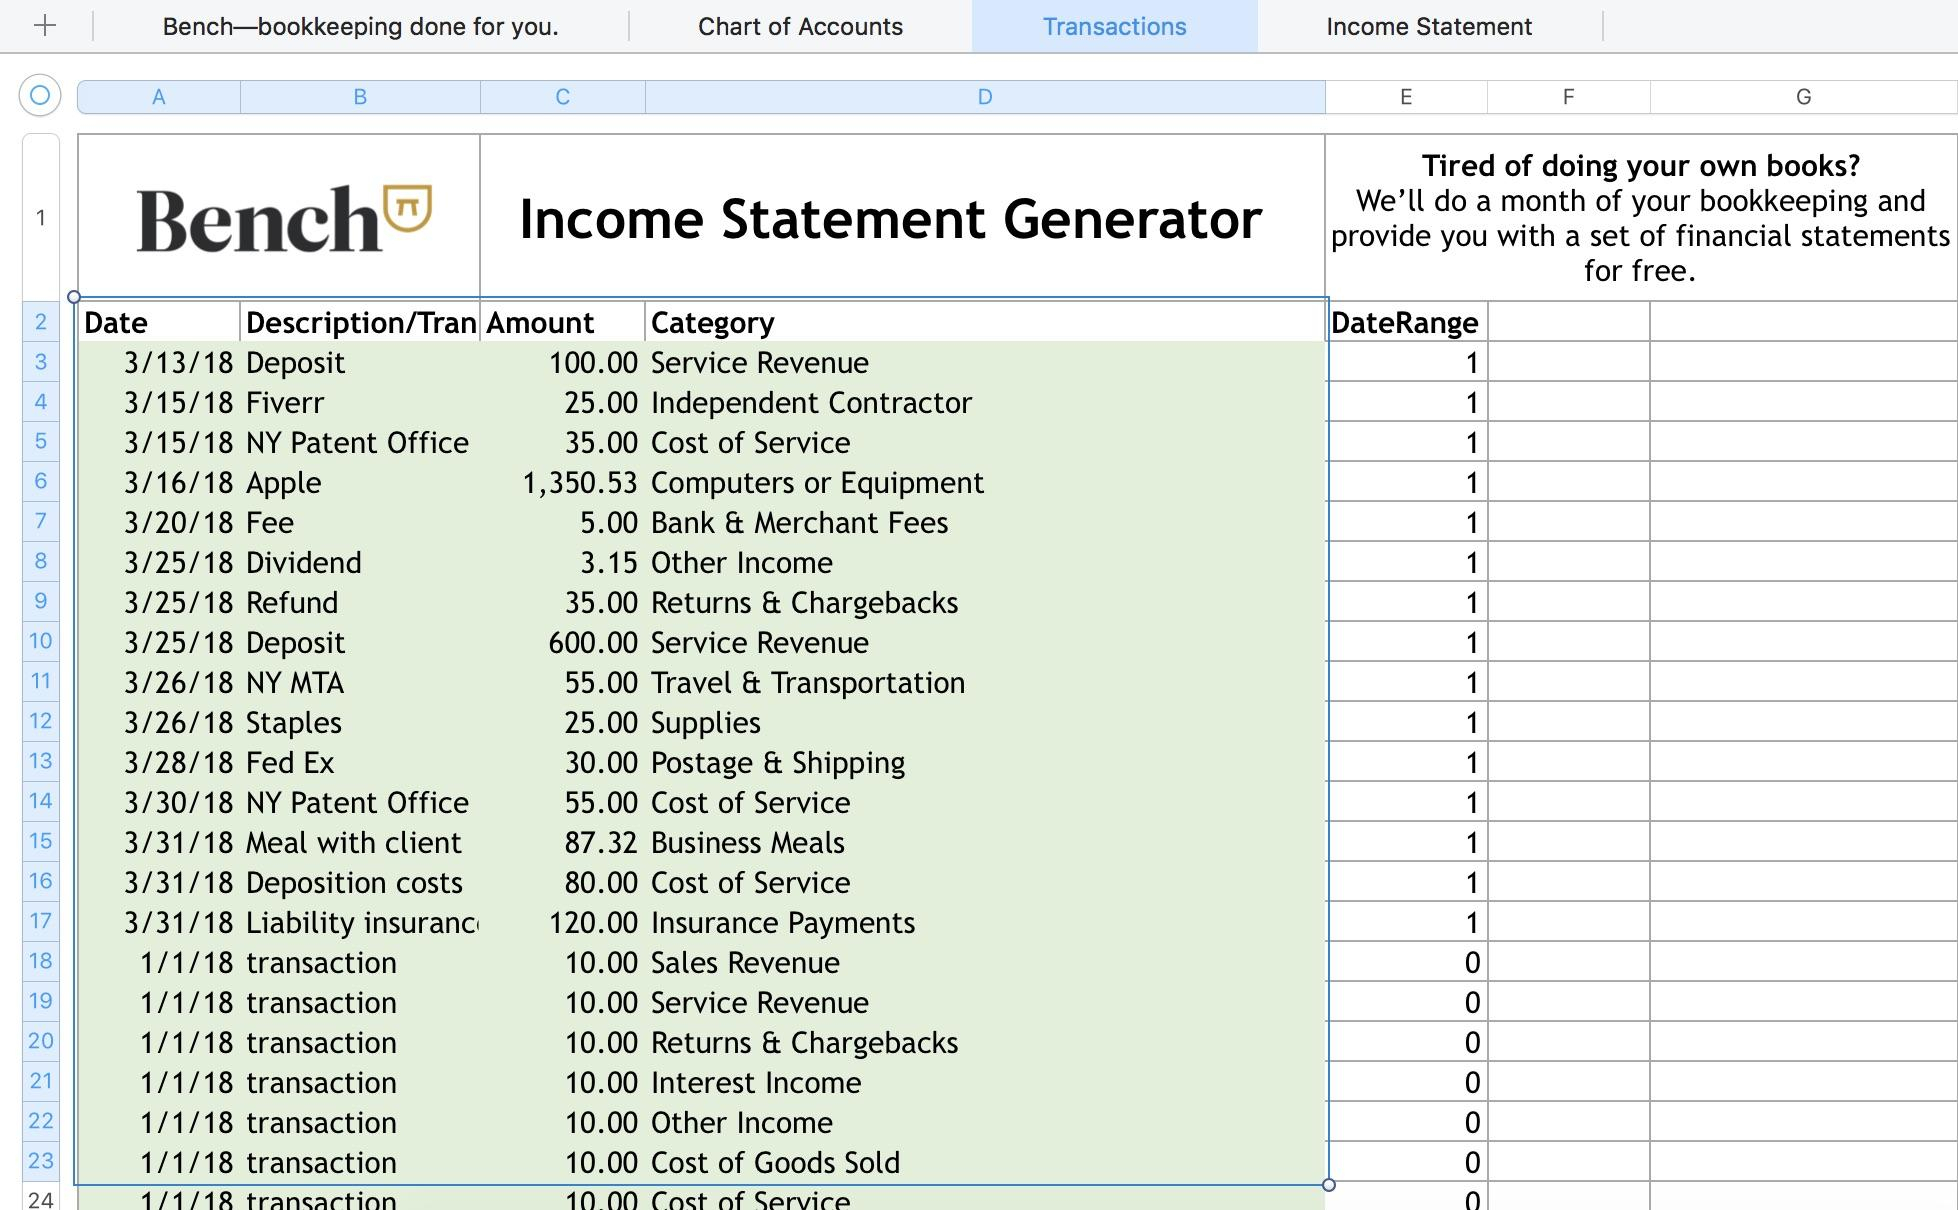
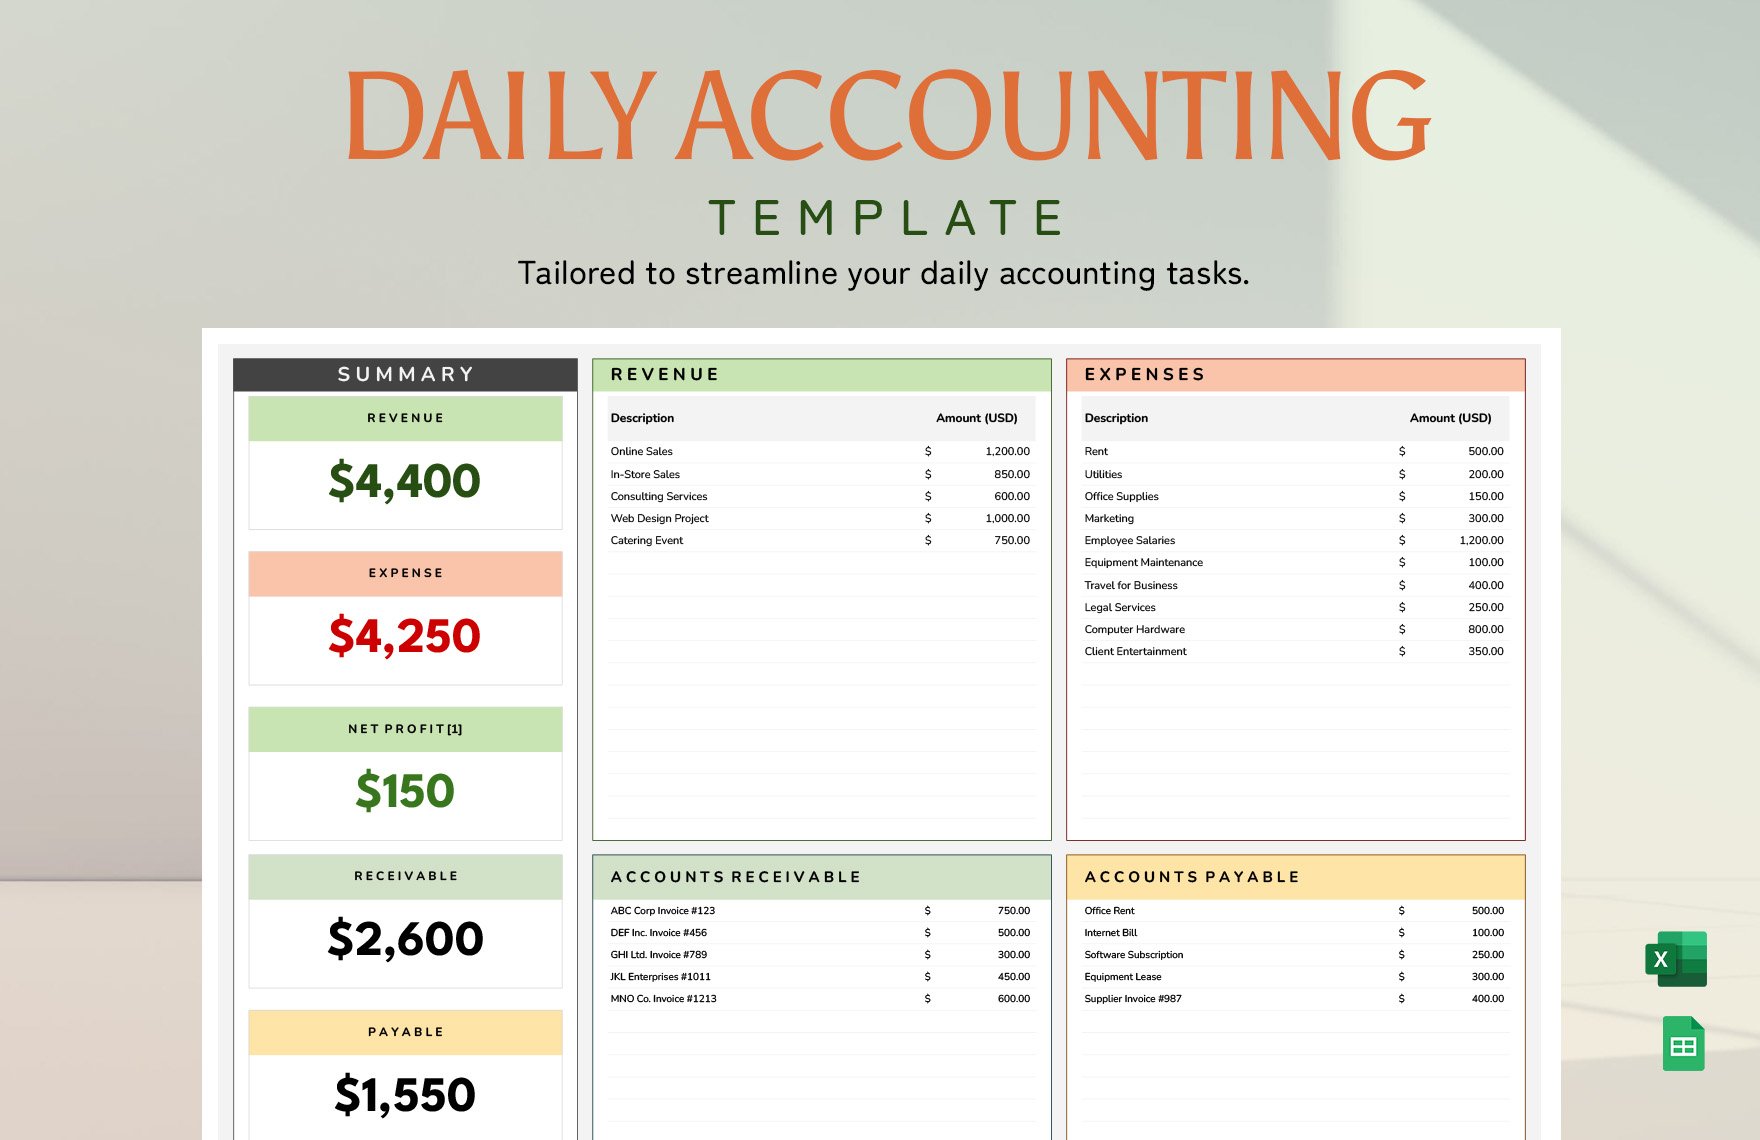
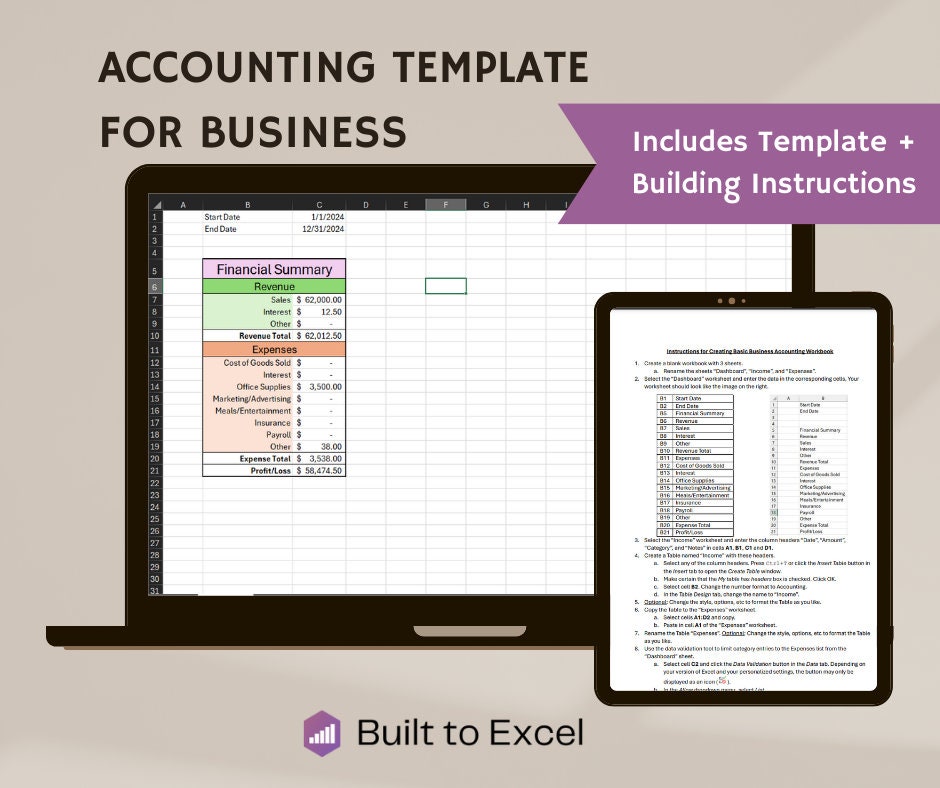
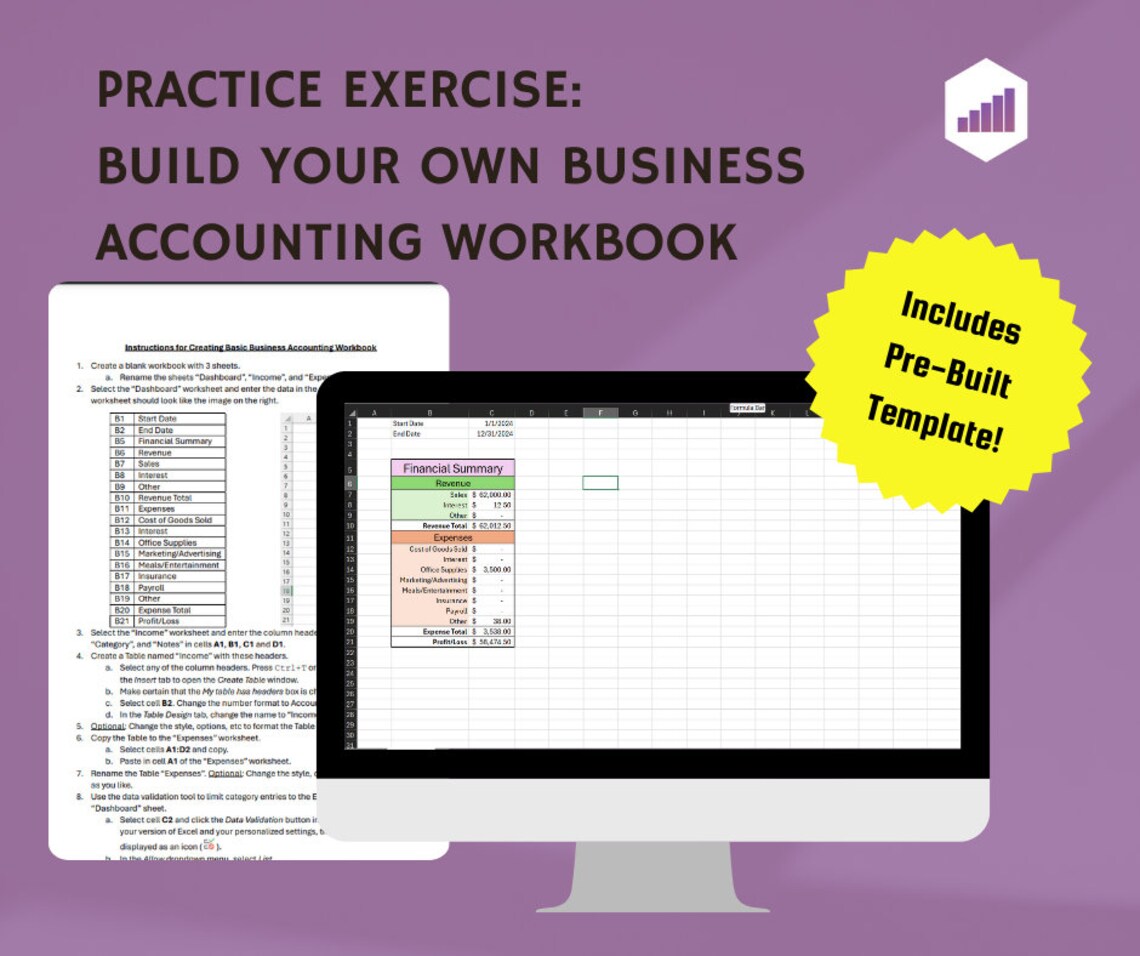
Start with a spreadsheet or a free tool like Wave or GnuCash, depending on your comfort level with software. The key is picking one and sticking with it. I see people switch programs every six months because they think the new one will solve their problems. It won't. The system matters less than consistency. Here is a concrete example that handles about eighty percent of small business and personal hybrid accounting needs: set up three main buckets — Income, Cost of Goods Sold, and Operating Expenses. Under Income, create subcategories for each revenue stream. Under COGS, track direct costs tied to each revenue line. Under Operating Expenses, group by function: rent, utilities, insurance, software subscriptions, marketing, professional fees, vehicle, and misc. That last category is where most DIY systems collect garbage, so limit it to things under fifty dollars that don't fit neatly elsewhere. Everything above that threshold should have its own line. The trick nobody mentions is tracking two numbers for every transaction: the gross amount and the net amount after tax. Sales tax collected is not income. It's a liability you owe the state. I learned this the hard way when I filed my first quarterly return and reported twelve thousand dollars in tax as revenue instead of liability. The amendment took three weeks and cost me more in time than the mistake was worth. From then on, every income entry had a parallel liability entry, and I reconciled the liability account monthly against what I actually owed.
Another practical Diy Accounting Examples pattern is the monthly reconciliation routine. At the end of each month, pull your bank statement and compare it line by line against your ledger. Flag anything that doesn't match. Most people skip this because it feels tedious, but it catches errors while they are small. A fifty-dollar misspelling in a vendor name is a two-minute fix. A fifty-dollar misspelling that has rolled into next year's tax filing is a two-hour headache. For inventory tracking, which most DIY accountants either ignore or overcomplicate, use the moving average method if you deal with physical products. Record the cost of each purchase batch, recalculate the average cost per unit after every buy, and apply that average to each sale. It is more accurate than FIFO for small operations and significantly easier to maintain than standard costing. I switched from FIFO to moving average in 2019 and cut my month-end close time from roughly four hours down to about forty-five minutes. One edge case that comes up constantly involves owner draws versus salary. If you are a single-member LLC or sole prop, you do not pay yourself a salary. Money you transfer to your personal account is an equity draw, not an expense. I watched a client of mine categorize every personal withdrawal as a payroll expense for two years, which artificially depressed his business profit and confused his tax situation entirely. The workaround is straightforward: create a separate equity account called Owner Draws and route all personal transfers through it. It keeps your P&L clean and makes tax season dramatically easier.
Get the Full Details
Depreciation is another area where DIY setups commonly go wrong. Most people either skip it or try to manually calculate straight-line depreciation in a spreadsheet column. Both approaches are fragile. If you use a tool like Wave, it handles depreciation schedules automatically once you enter an asset and its useful life. If you are doing everything in a spreadsheet, at minimum build a separate depreciation schedule tab that references your asset register and rolls cumulative depreciation into your monthly trial balance. The alternative is showing up to tax time with no depreciation recorded and paying more than you should. The main limitation of any DIY accounting approach is scale. When your transaction volume exceeds roughly two hundred per month, manual entry becomes unsustainable regardless of how well organized your system is. At that point, the time cost of maintaining accuracy outweighs the cost of basic bookkeeping software or a part-time freelancer. There is no shame in that transition. The best DIY system in the world will collapse under two hundred entries a month if you are entering them by hand. Another honest limitation is that DIY accounting assumes you have a baseline understanding of double-entry bookkeeping. If you treat every transaction as a single line item without understanding debits and credits, your balance sheet will eventually not balance and you will not know why. The learning curve is maybe two weekends of focused study, but skipping it means you are flying blind.
For most people running a small operation, side business, or freelance practice, a disciplined DIY system using the structures above will serve you adequately for years. The difference between a system that lasts and one that collapses usually comes down to whether you reconcile monthly and whether you resist the urge to add new categories every time something unfamiliar pops up. Stick to the core structure. Refine it once a quarter at most. Anything more frequent is just noise.
When to Move Beyond DIY
If you find yourself spending more than four hours a month on bookkeeping, or if your numbers regularly don't match your bank statement by more than a few dollars, it is time to evaluate whether a dedicated tool or a human bookkeeper makes sense. For most small operators, that threshold hits around the eighteen-to-twenty-four-month mark of consistent operation. Before then, a well-maintained DIY setup is perfectly sufficient and saves money that would otherwise go to monthly software subscriptions or freelance fees.