How I Actually Use a Lump-Sum Payoff Calculator Without Getting Burned
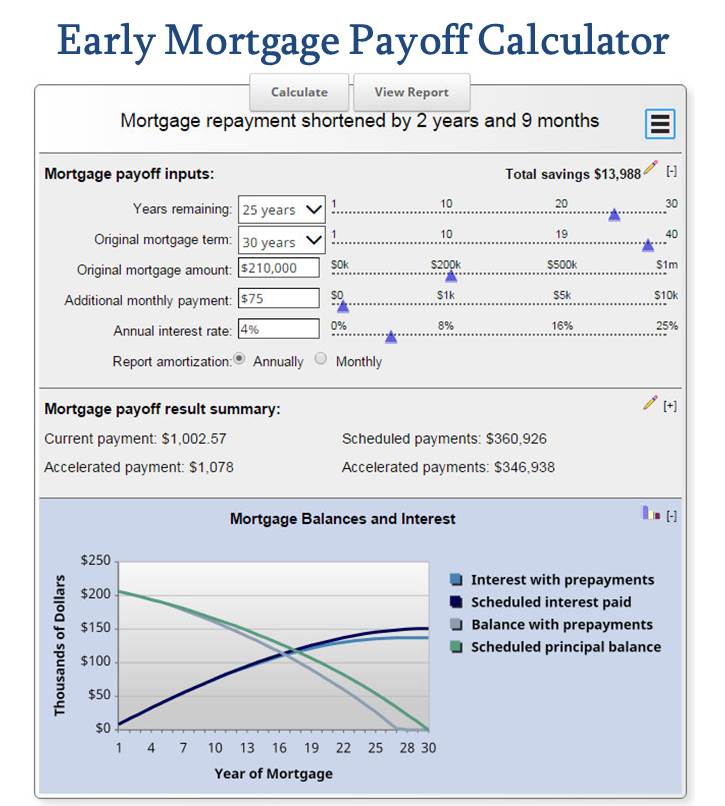
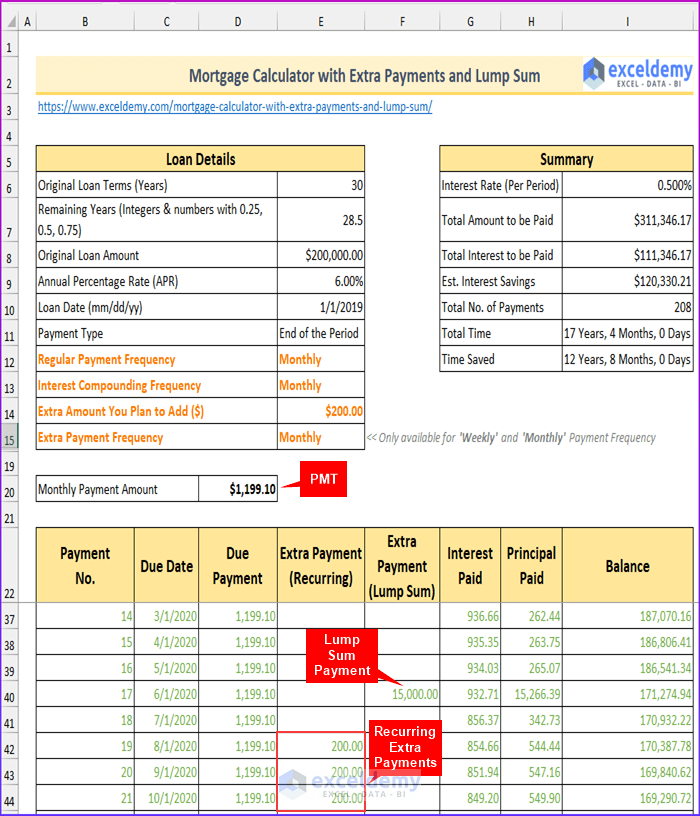
Most people who download an Early Mortgage Payoff Calculator Lump Sum tool and then try to follow its output blindly end up making a messy phone call to their servicer three weeks later. I've been doing this for long enough that I can predict the exact point where the spreadsheet stops matching reality. The first thing you need to understand is that these calculators assume your payment is applied in a very specific way, and most mortgage servicing algorithms do not work exactly the same. The calculator takes your current principal balance, your interest rate, and the lump-sum amount you want to throw at the loan. It then compounds the remaining balance forward at your stated rate and subtracts the extra payment from the principal. The difference between the original payoff date and the new payoff date is the time saved, and the difference in total interest paid is the dollar amount you save. That's the model. In practice it's close enough for a planning exercise, but the numbers it spits out are theoretical until your servicer confirms they posted correctly. I ran into this with a client in 2022 who wanted to drop $40,000 on a 30-year fixed at 3.75 percent with roughly 18 years remaining. The calculator said we'd save about $31,000 in interest and knock 6.3 years off the term. We made the payment. Two months later I pulled the statements and realized the savings were closer to $27,400. The gap wasn't a calculator error, it was the timing of the payment within the billing cycle. His servicer was using a daily simple-interest method, so a payment that hit mid-cycle earned fewer days of interest offset than a payment that hit right after the statement cut. The online tool assumed end-of-period application.
The workaround was straightforward. I had the client set a standing instruction with the servicer to apply any future extra payments within five business days of the statement date. That locked the timing variable down. For the one-time lump sum, the lesson was just to budget for a small variance and to verify the amortization schedule update in writing before assuming the numbers were final.
How I Run the Numbers Before Writing the Check
I don't trust a single calculator output without cross-checking it against the servicer's own payoff quote, because the quote includes accrued interest up to a specific date and sometimes reflects a different daily interest factor. My process is to pull the current principal balance from the most recent statement, confirm the annual percentage rate matches what's on file, note whether the loan has prepayment penalties or yield spread premium offsets, and then run three scenarios: the lump sum applied to principal reduction, the lump sum applied to term reduction, and the lump sum left as an emergency reserve instead. The third scenario is the one people skip until they're underwater. A $40,000 payment looks heroic on paper, but if that money is the only liquidity buffer for property taxes, roof replacement, or job loss, the calculator won't tell you the hidden cost of being illiquid. I always build a separate row for opportunity cost and compare the mortgage rate against what a high-yield account or short-term Treasury ladder would net after taxes.
Get the Full Details

Specific Things I Check Before Using Any Tool
The first check is the amortization type. Some portfolios still run on old-style compound interest calculations rather than daily simple interest, and the variance shows up most clearly in the last three years of the loan. The second check is whether the loan has a lock-out period. I had a loan from 2008 where the borrower tried to dump a bonus into principal and got hit with a 1.5 percent penalty because the contract locked prepayments for the first five years. The calculator doesn't know about that clause unless you paste the contract language into it. The third check is escrow treatment. If the servicer is using a shortfall method and your property tax bill jumped, the extra payment might get partially absorbed by the escrow replenishment rather than going entirely to principal. I've seen that reduce the effective principal impact by ten to fifteen percent on a single cycle. The fix is to request a principal-only payment designation in writing and to verify the posting on the next statement.
When the Calculator Is Wrong and What to Do Instead
If your loan is a government-backed refinanced product with a blended interest rate, or if you have a hybrid ARM that just reset, the standard Early Mortgage Payoff Calculator Lump Sum assumptions break down fast. The calculator will treat the rate as static. In those cases I pull the actual loan documentation, extract the adjustment caps and margin, and model the payment change month by month before committing any cash. It takes longer, maybe twenty to thirty minutes of setup, but it prevents you from overpaying early and then getting blindsided when the rate resets upward. Another edge case is a loan with negative amortization features still running from older jumbo products. Those balances can actually increase before they decrease, and a lump sum applied at the wrong point can push you into a new recast window with different terms. I learned that one the hard way in 2019 when a client's servicer recalculated the amortization schedule after a large payment and unexpectedly changed the due-date alignment, which added a partial month of interest that the original tool hadn't captured. The workaround was to request a formal payoff reconstruction from the servicer's loss-mitigation department rather than relying on a third-party calculator.
The Practical Steps I Follow Now
I start with the current payoff figure, not the statement balance, because the payoff figure is the authoritative principal number on a given date. I input that, the contract rate, and the remaining months. I run the lump sum at three levels, say ten percent, twenty-five percent, and fifty percent of the remaining balance, and I record the interest savings for each. Then I compare the lowest-cost option against the liquidity alternative. If the interest savings exceed the after-tax yield I could earn risk-free over the same horizon, and if I still have six months of expenses preserved, I proceed. Before wiring the money, I send a written instruction to the servicer specifying principal-only application and requesting written confirmation of the updated amortization schedule. I don't consider the transaction complete until I see the new schedule posted, not just a confirmation email that says the payment was received. The timeline from instruction to posted update is usually two to four billing cycles, sometimes longer for non-traditional servicers. I build that lag into the decision so I'm not surprised when the calculator's idealized timeline doesn't match the servicer's processing reality.