Why You Should Be Tracking Money Instead of Just Hoping It Works Out
I spent seven years before I ever wrote anything down about where my money went. I used apps, spreadsheets, the whole routine. Nothing stuck because I was only recording transactions after they happened. By the time I noticed I was overspending, the month was already over and nothing could be changed. That changed when I started using a prompt-based approach to finance journaling. It sounds like an odd combo — prompts and budgeting — but the structure actually forces reflection before the spending spiral kicks in. Most people treat finance journaling as a diary entry with numbers. That doesn't work because there's no prompt driving the entry toward actionable insight. Easy Finance Journal Prompts gives you a rotating set of questions that target different parts of your financial behavior: intent before purchase, review after spending, weekly pattern recognition, monthly direction-setting. The prompts themselves aren't revolutionary. What makes them useful is that they're written to interrupt autopilot habits.
Easy Finance Journal Prompts
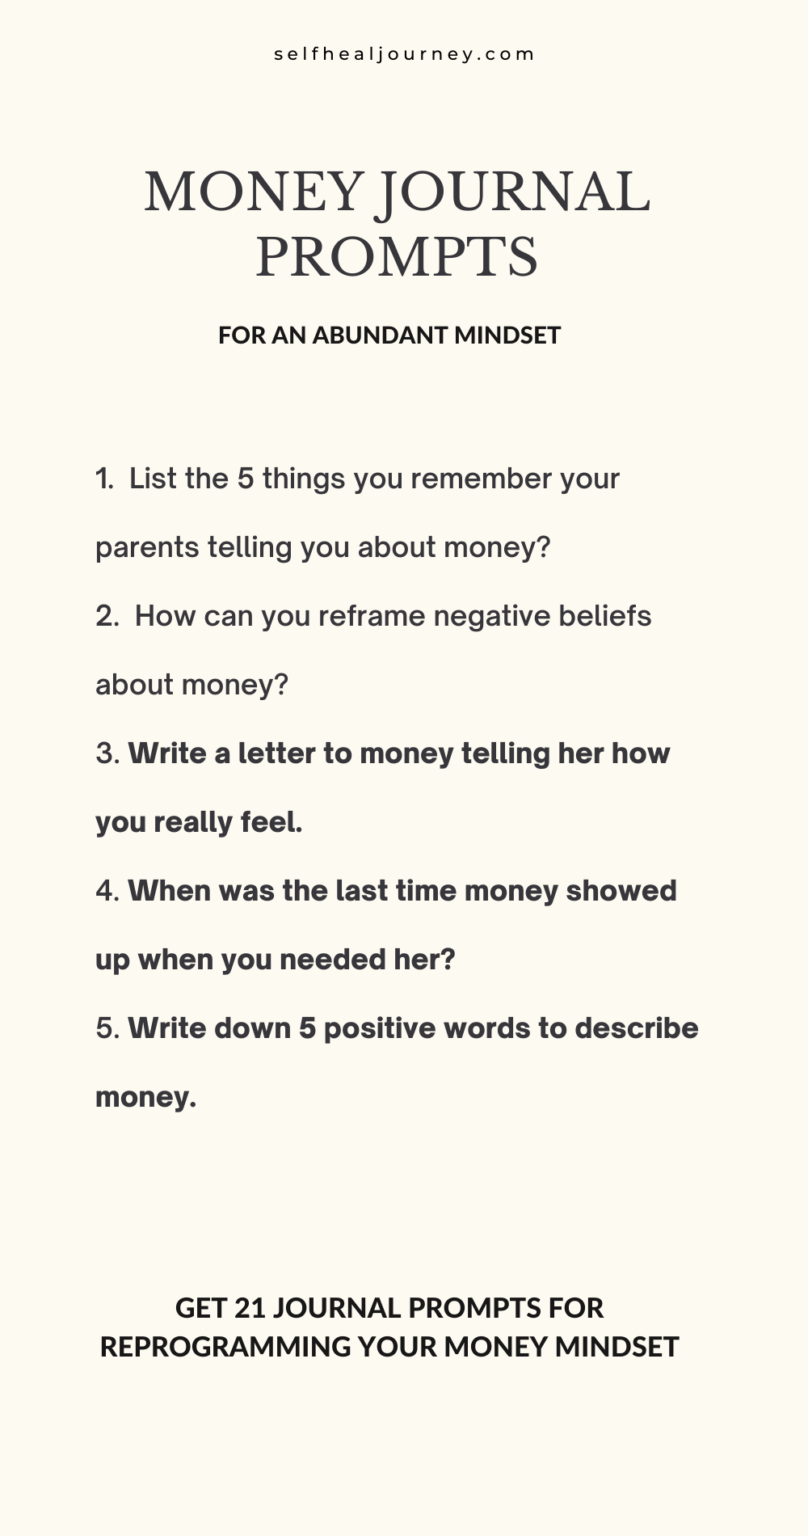
Here's the actual set I've been running with for about fourteen months now, and the one I recommend starting with: Prompt 1: What did I plan to spend money on today, and what actually happened? Prompt 2: Where did money disappear from that I didn't notice leaving my account?
Prompt 3: What financial decision did I make today that I'll probably regret in six months? Prompt 4: Did I spend money to fill a non-money hole today? Prompt 5: What's one thing I'm spending on that no longer serves me, and how much did I waste on it this month?
Get the Full Details
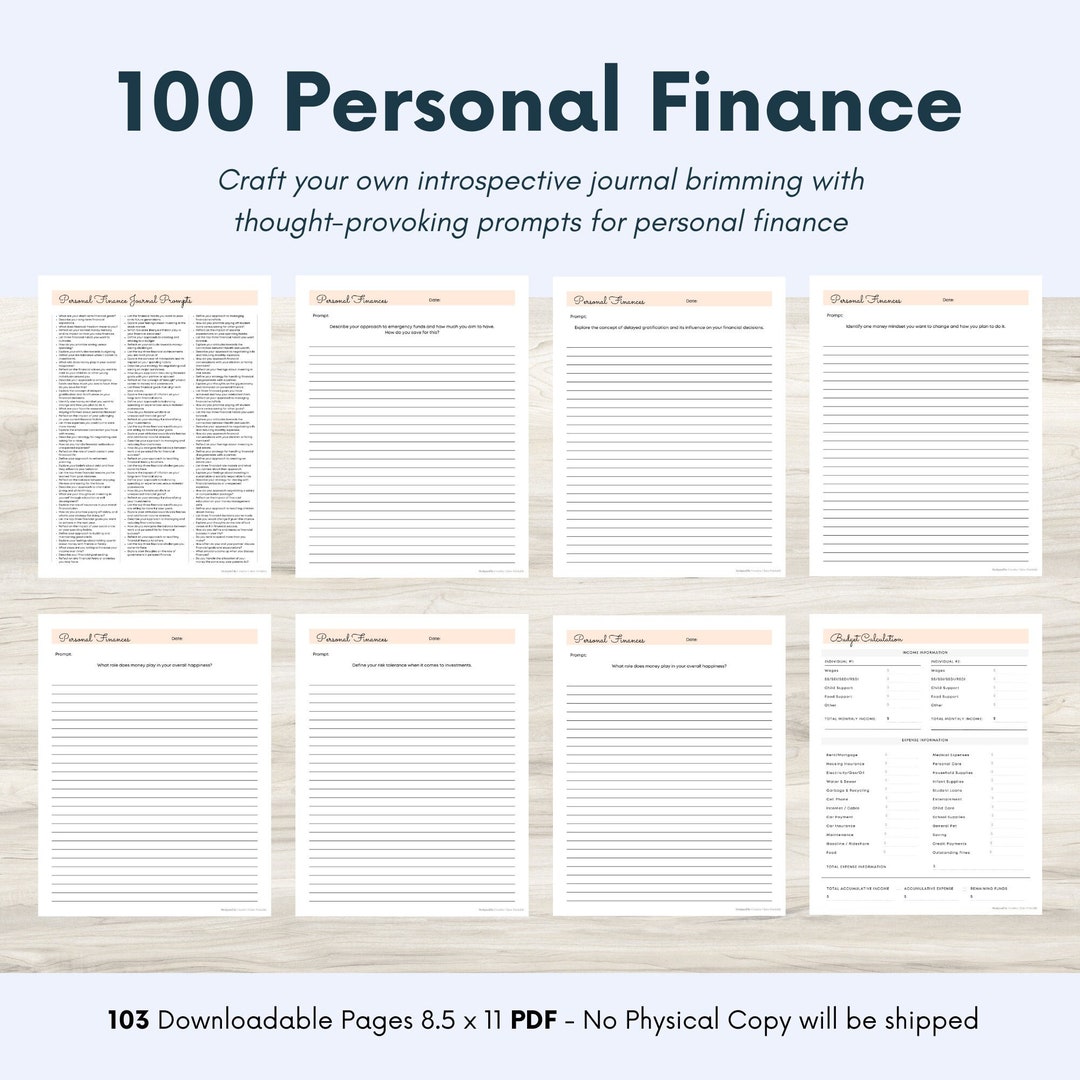
Those five rotate daily. You answer each one in whatever format works — notes app, plain text file, a free spreadsheet, doesn't matter. The format is irrelevant. The consistency is what matters. I use a simple Google Doc with dated entries and a timestamp. Takes about three minutes a day once the habit is built. Here's the part nobody tells you about this method: the first two weeks will feel pointless. Your answers will be thin. "Spent $4 on coffee." "Nothing special happened." This is normal and it's also the filter that separates people who actually benefit from this from people who quit. The insights don't come from individual entries. They come from the pattern that emerges after about twenty entries when you start reading backwards. Around entry twenty-three I caught that I was spending between eighty and one hundred twenty dollars per week on food delivery without realizing it. I had no idea. The app data showed the same total but it was invisible to me emotionally. Writing it out forced the recognition. There's a second layer to this that most people miss. The prompts are designed to surface behavioral drivers, not just numbers. Prompt 4 in particular — the non-money hole one — consistently surfaces the real reason behind impulse spending. Stress, boredom, avoidance, loneliness, fatigue. Identifying the trigger is more valuable than identifying the amount. I've seen people cut their discretionary spending by forty percent just from that single question. The money wasn't the problem. The problem was that they weren't paying attention to why they were spending it.
Another thing that trips people up: you need to check your accounts before answering Prompt 1 and Prompt 2. If you don't, you're just writing fantasies instead of data. I learned that the hard way when I wrote "I spent nothing unexpected" only to discover three recurring subscriptions I'd forgotten about that totaled sixty-seven dollars that month. The journal entry was a lie because I didn't verify the source material first. That's the main bottleneck with this system — it requires you to actually look at your accounts. If you're already checking your balances daily, this takes maybe ninety seconds extra. If you're flying blind, it'll add five to ten minutes until you build the verification habit. The method also has some real limitations. It doesn't help with debt payoff calculations, investment decisions, or anything that requires forward-looking math. It's purely behavioral tracking. If you need to model loan amortization or plan a retirement contribution strategy, this isn't the tool for that. Use a spreadsheet or a proper planner for that. This is for understanding your spending habits, not your net worth trajectory. Another limitation: it doesn't scale well if you have a very complex financial life. Multiple accounts, businesses, rental income, side hustles — you'll spend more time reconciling than journaling. In those cases, I recommend pairing it with automated aggregation software that pulls transaction data so you're not manually entering everything. The prompts still work, but the manual entry burden defeats the purpose if you're spending thirty minutes a day reconciling transactions.
For most people with a standard checking account and maybe one credit card, this is low-friction enough to sustain. I've tracked my personal finances this way for over a year and it's saved me probably two to three thousand dollars in identified waste and impulse spending. That's a rough estimate based on comparing my journal findings to my old spending patterns before I started the practice. The prompts are freely available in various forms online. You can find compiled lists on personal finance blogs and Reddit threads. I usually reference a combination of the ones I listed above and variations from r/personalfinance and r/financialindependence. The specific wording doesn't matter as much as having the rotating structure. Pick a set, commit to the daily entry, and let the patterns emerge over time. Most people give up around day ten. Don't be most people.