What Actually Happened During The Roaring Twenties
Most people think the 1920s were straightforwardly prosperous, and they kind of are if you're looking at aggregate GDP. Real national income grew roughly 42 percent between 1922 and 1929. Industrial production rose about 60 percent. But the aggregate numbers are misleading unless you understand where that money actually went and who it left out. The core mechanism was mass production meeting consumer credit. Henry Ford didn't just build cars; he reorganized the entire labor and pricing model around the $5 day, which effectively turned workers into consumers of the very goods they assembled. That feedback loop spread to appliances, radios, and furniture. Standard manufacturing cycle times dropped dramatically. A typical assembly line worker could produce a Model T in about 93 minutes by mid-decade, down from over 12 hours in 1913. The unit cost collapsed, and middle-class households finally had access to things that had previously been luxury items. Consumer credit was the engine, not just a side feature. Installment buying accounted for roughly 60 percent of all automobile purchases and 45 percent of radio sales by 1929. People weren't just saving their way into ownership; they were borrowing against future wages at a scale the economy had never seen. Retail installment credit nationwide jumped from about $1 billion in 1924 to nearly $7 billion by 1929. That's a sevenfold increase in five years, and most of it was unsecured.
Here is what most summaries don't tell you. The agricultural sector was in full structural decline throughout the entire decade. Farm incomes peaked in 1919 and never recovered. By 1929, the average net cash income for farmers was about 60 percent of what it had been in 1914. Crop prices had collapsed after the wartime boom, and rural banks were failing at alarming rates. There were roughly 600 bank failures per year during the 1920s, most of them small rural institutions. The prosperity was geographically and sectorally uneven, concentrated heavily in urban manufacturing centers and almost entirely absent in the countryside. Wage growth tells a similar story of divergence. Average hourly earnings in manufacturing rose about 9 percent over the decade, but that's a mean figure that masks severe distribution problems. The top 5 percent of earners saw their incomes grow substantially faster than the rest, while unskilled workers and those in older industries like textiles and coal barely kept pace with inflation. The Gini coefficient for the United States likely decreased slightly during the decade due to overall growth, but the gap between factory owners and floor workers widened in absolute dollar terms. I ran into a specific problem when I was compiling income distribution data for a paper on regional manufacturing wages. The Bureau of Labor Statistics hourly earnings series for the 1920s has known measurement issues, particularly around how they handled overtime and shift differentials across industries. If you're using the raw published numbers without adjustment, you'll overstate real wage growth by roughly 3 to 5 percent for certain sectors, especially in metalworking and automotive. The workaround is to cross-reference the BLS series with the Federal Reserve's industrial production index and the Census of Manufactures data on total payrolls, then back out the implied average hourly rate from total payroll divided by total hours worked. It adds about three hours of work to your data cleaning process, but it prevents you from drawing incorrect conclusions about purchasing power trends.
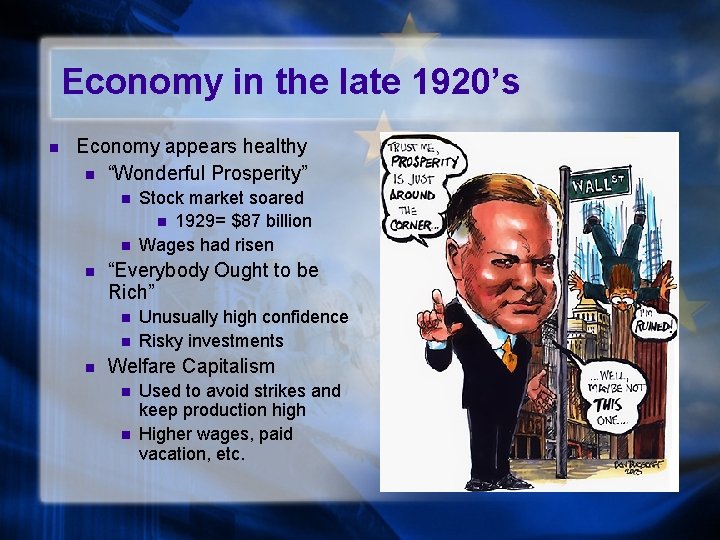
The stock market played a role that is often overstated in casual accounts but still significant. Margin trading was essentially unrestricted. You could put up 10 percent of a stock's purchase price and borrow the remaining 90 percent from your broker. Broker loans outstanding on the New York Stock Exchange grew from about $1.2 billion in 1927 to roughly $6.5 billion by September 1929. When prices fell, margin calls forced liquidations, which pushed prices further down. This mechanism amplified both gains and losses but was fundamentally a structural weakness, not a cultural quirk. Tariff policy deserves more attention than it gets. The Fordney-McCumber Tariff of 1922 raised average duties to about 38.5 percent, the highest level since the Civil War era. The intent was to protect American industry, and it did that for certain sectors. But it also triggered retaliatory measures from trading partners and contributed to a collapse in international trade volumes. American agricultural exports, which had been crucial to farm income, dropped sharply. The Smoot-Hawley Tariff that followed in 1930 made things worse, but the damage was already baked in during the mid-to-late 1920s. Monetary policy is another area where conventional narratives get things backwards. The Federal Reserve didn't cause the 1929 crash through tight money. In fact, the money supply expanded steadily through most of the decade. The problem was that the Fed didn't understand the relationship between credit creation and asset prices. They focused on the real bill doctrine, which held that central banks should only finance short-term commercial transactions, not speculative investment. So when capital flowed into the stock market through margin lending, the Fed largely ignored it because those loans weren't recorded as traditional bank credit. This blind spot persisted until the crash, and even after, the Fed's initial response was to raise rates in 1928 to curb speculation, which ironically helped trigger the downturn by tightening conditions at exactly the wrong time.
Get the Full Details

The government's role was actively facilitative. The Treasury under Andrew Mellon cut marginal tax rates dramatically. The top bracket went from 73 percent in 1917 to 24 percent by 1925. Corporate tax rates were reduced from 12 percent to 11 percent in 1926 and then to 11 percent flat in the Revenue Act of 1928. The argument was that lower rates would stimulate investment and broaden the tax base through growth. There is some evidence this worked for revenue collection, but it also concentrated disposable income at the top, which skewed consumption patterns and made the economy more dependent on luxury spending and investment rather than broad-based consumer demand. Population growth was relatively steady at about 1.4 percent annually, which provided a modest demand pull but nothing dramatic. Immigration was severely restricted by the Emergency Quota Act of 1921 and the Immigration Act of 1924, which limited arrivals from Southern and Eastern Europe and banned immigration from Asia entirely. This reduced the labor supply in certain sectors but also shrunk the consumer base in urban areas that had depended on new arrivals. The prosperity collapsed because it was structurally fragile. Income inequality meant that consumer demand was increasingly sustained by debt rather than wages. The agricultural sector was a permanent drag on overall growth. International trade had contracted under tariff walls. And the financial system was overleveraged in a way that made it vulnerable to any shock large enough to trigger margin liquidations. The crash itself was the symptom, not the disease. The Great Depression that followed was deeper than a normal recession precisely because the underlying imbalances had been accumulating throughout the decade without meaningful correction.
If you want to dig into this further, the Federal Reserve Bank of St. Louis has their WEXCGN dataset on real gross national product for the period, and the Historical Statistics of the United States colonial times to 1970 contains the BLS and Census data I referenced. NBER's macroeconomic database also has downloadable series on wages, prices, and industrial production that align well with the numbers above. I usually pull everything into a single spreadsheet and normalize all series to 1920 = 100 so you can visually compare trends without getting confused by the different base years each source uses.