How to Actually Use Economics When Making Investment Decisions
Most people treat economics as background noise. It isn't. The difference between decent returns and expensive mistakes often comes down to whether you're reading macro signals correctly and whether you understand how micro and international factors cascade through a portfolio. I spent years watching people ignore basic economic indicators while making allocation calls, then wonder why their models broke during transitions. The core problem isn't that economics is hard. It's that the discipline requires you to hold multiple frameworks at once — micro, macro, and international — and most people collapse them into a single narrative. That shortcut fails under stress.
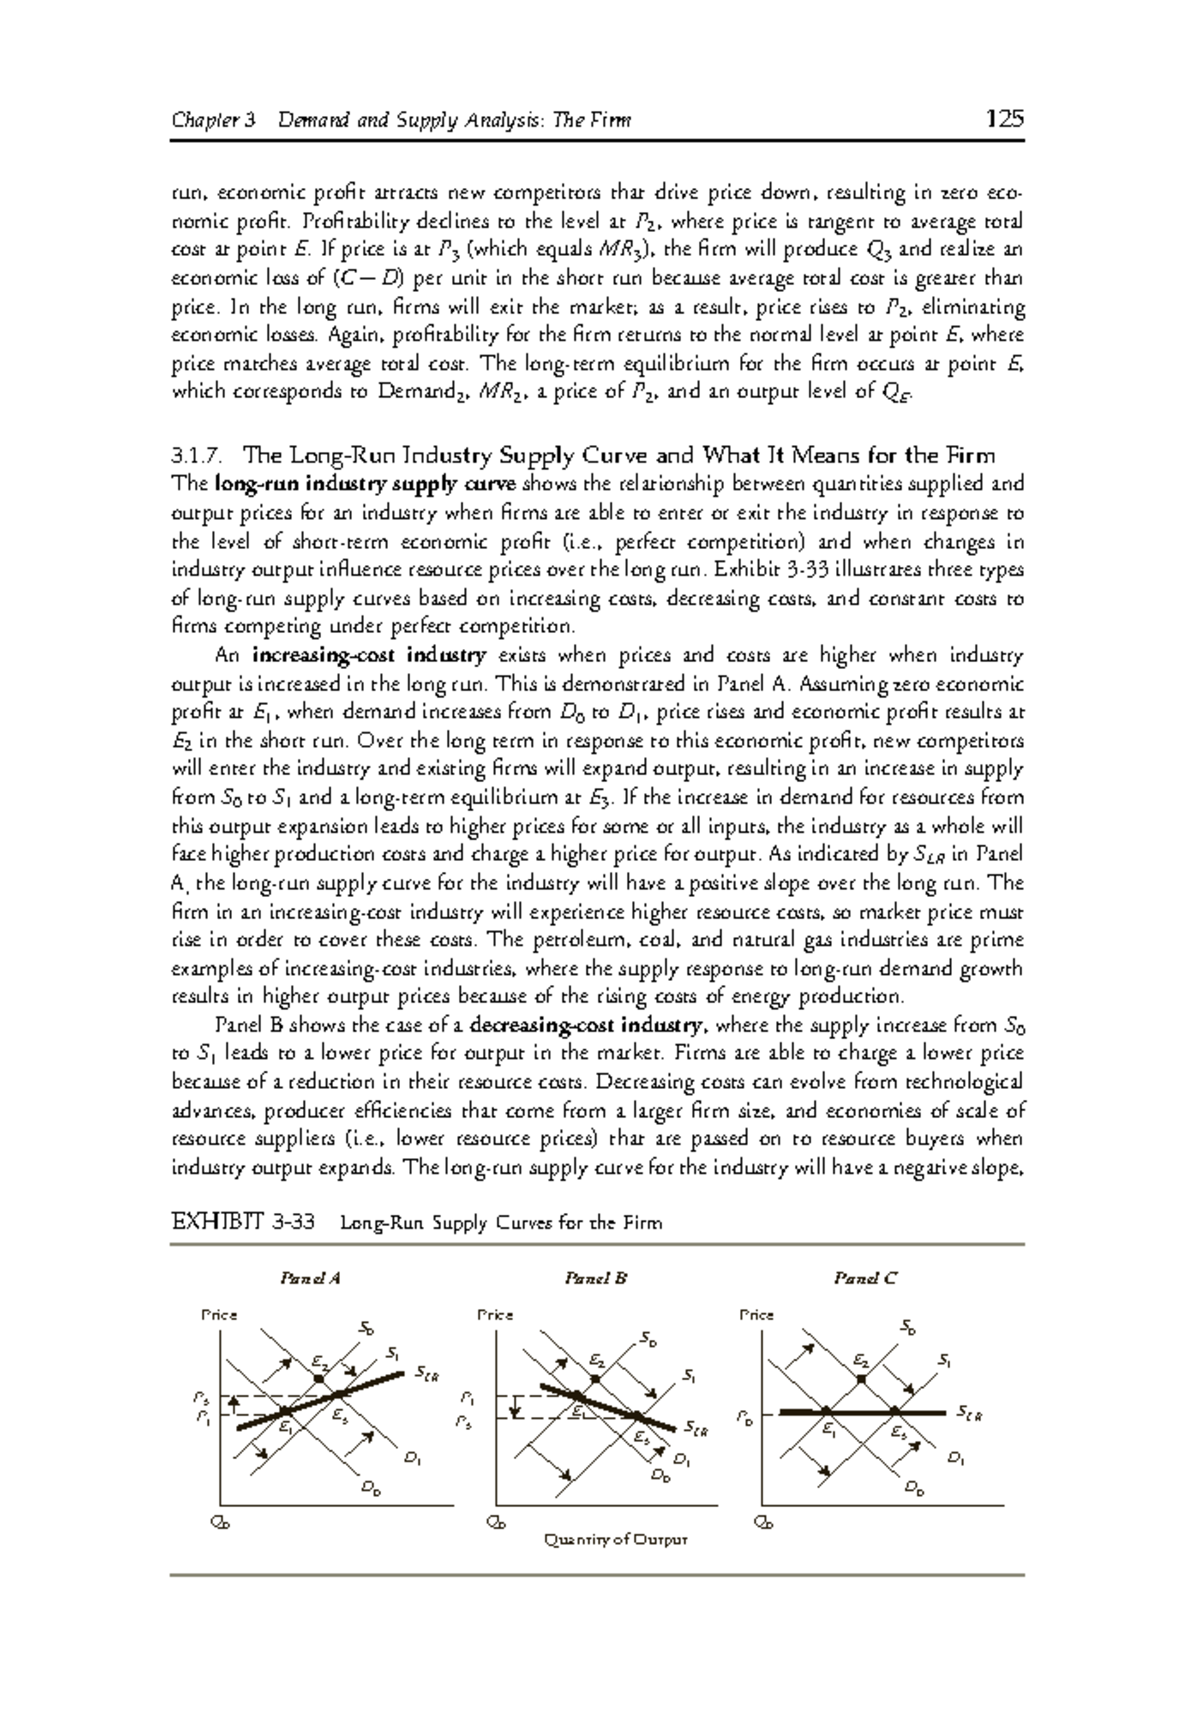
Economics For Investment Decision Makers Micro Macro And International Economics
When I say economics for investment decision makers, I mean the practical application of economic reasoning across three layers. Micro economics tells you about company-level dynamics — pricing power, input costs, competitive positioning. Macro economics tells you about the environment — interest rates, inflation, growth cycles, fiscal policy. International economics tells you about cross-border flows — currency movements, trade balances, capital migration, geopolitical friction. These three layers interact constantly. A tariff war hits corporate margins through micro channels, but it also moves currency pairs and shifts capital allocation across borders. If you only study one layer, your conclusions will be incomplete and often wrong at the worst possible moment. Here is how I approach this systematically. First, I map the current macro regime. Is it inflationary or disinflationary? Are central banks tightening or easing? What does the yield curve suggest about the next 6 to 18 months? This gives me the weather report before I decide what to plant. Second, I look at which sectors are mispriced relative to that regime. Third, I check international linkages — is the dollar strengthening or weakening, are commodity prices signaling global demand shifts, are there trade policy changes that could disrupt supply chains?
I remember running a thesis in 2022 around emerging market equities. The macro picture looked reasonable — falling US rates, stable commodities, a weaker dollar. But I had underweighted the international economics angle. A major commodity exporter had quietly moved to capital controls, and the currency was going to devalue. By the time the news hit, the move was already priced in and painful. The workaround I use now is to add a dedicated capital flow monitoring step before any allocation decision. I track reserve changes, forward premium discounts, and central bank intervention signals rather than waiting for headline news. One counter-intuitive point that nobody teaches well: correlations that look stable in normal times often flip during regime changes. A sector that correlates positively with growth might suddenly correlate with recession risk if the transmission mechanism changes. This happened with real estate in 2023. The traditional model said falling rates should support valuations. But credit availability tightened independently of rate levels due to regulatory changes, so the relationship between rates and real estate broke down temporarily. The market was slow to recognize the new regime. Another thing that trips up beginners is overconfidence in predictive models. Economic models are tools for structuring thinking, not crystal balls. A DCF model with the right assumptions gives you a range, not a precise target. A bad assumption about terminal growth or discount rate movement can swing your conclusion by 30 percent or more. I always run sensitivity tables before committing to a position. If the recommendation flips with a one percentage point change in your key variable, you do not have a conviction trade. You have a guess with extra steps.
Get the Full Details
When working through international economics, currency movements deserve more attention than most investors give them. A strong dollar does not just affect importers and exporters. It changes the discount rate for global cash flows in USD terms, which reshapes valuations across sectors. During my time managing cross-border allocations, I learned to adjust return expectations by the expected currency move before comparing asset classes. Failing to do so means your comparison is fundamentally asymmetric. The biggest limitation of using economics this way is data lag. By the time a GDP print or inflation reading confirms a trend, markets may have already moved. Forward indicators like PMI surveys, yield curve shifts, and credit spreads tend to lead, but they are noisy. The best approach combines leading indicators for timing with lagging indicators for validation. Use the leading signals to position early, but confirm with the lagging ones before committing large amounts of capital. If you want to build this into a routine, start small. Pick one macro indicator, one micro metric, and one international variable each quarter and track their interactions. Do not try to model everything at once. The goal is pattern recognition, not precision. Over six months of disciplined tracking, you will start seeing connections that were invisible before. That is when the framework becomes useful rather than theoretical.