Why Marginal Thinking Matters More Than Total Numbers
Most people who first encounter economics get hung up on total costs or total revenue. They look at a spreadsheet and try to balance the whole thing. That approach works in high school textbooks but falls apart the moment you face a real business decision. The reason economics involves marginal analysis because looking at totals obscures the actual decision point. You are never deciding about everything. You are deciding about one more unit, one more hour, one more worker. I remember working through a capital budgeting exercise for a mid-sized logistics company a few years back. They wanted to know whether to add a third shift to one of their warehouse locations. The total cost analysis looked terrible. Three shifts meant overtime, supervisory headcount increases, utility spikes, and insurance adjustments that pushed the projected annual cost well above the comfort zone of the CFO. But when I shifted the lens to marginal analysis, the picture changed entirely. The fixed costs of the building and the existing equipment did not change. What changed was the incremental revenue from the extra throughput minus the incremental labor and utility costs for just that additional shift. The math flipped from a loss to a clear profit within nine months. The total-cost framework had hidden that because it forced us to allocate overhead across scenarios where it simply did not move.
Economics Involves Marginal Analysis Because Decisions Are Incremental
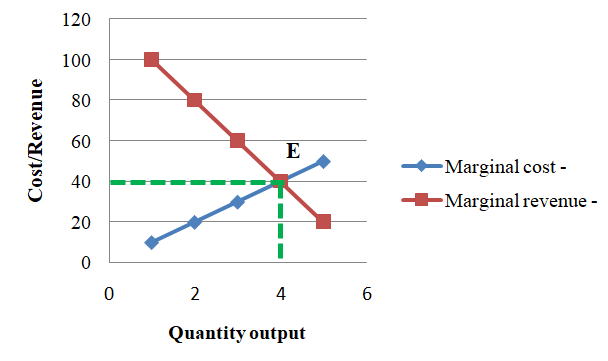
This is the core of it. Every real decision is about a change at the margin, not about the entire system. You do not choose between producing nothing and producing everything. You choose between producing Q and producing Q plus one. The difference is what matters. Marginal cost is the cost of that one additional unit. Marginal revenue is the revenue from selling that one additional unit. When marginal revenue equals marginal cost, you have hit the optimal output level. Producing beyond that point adds more to cost than it does to revenue. Producing less leaves money on the table. The tricky part is that marginal values are rarely constant. In practice, marginal cost tends to rise as output increases because of capacity constraints, worker fatigue, maintenance wear, and the need to bring in higher-priced inputs. Marginal revenue tends to fall as you push more units into the market because you either lower the price to move the extra volume or you run into demand saturation. The intersection of those two curves is your answer, and finding it requires actual data, not intuition. One thing that trips people up constantly is the distinction between average and marginal. Average cost is useful for pricing and reporting, but it is the wrong tool for decision-making. If your average cost per unit is $50 and someone offers to buy ten units at $45, your instinct might say no. But if the marginal cost of those ten units is only $20 because the fixed costs are already covered, then saying no is literally throwing profit away. I saw a manufacturing manager reject a large order on exactly that basis and then watch a competitor take it and make money on it. The lesson was expensive for him.
Another nuance that rarely gets enough attention is time horizon. Marginal analysis looks different depending on whether you are operating in the short run or the long run. In the short run, some inputs are fixed. You can vary labor and materials but not the size of your facility. Marginal cost in the short run can spike sharply because you are pushing against a fixed constraint. In the long run, you can adjust all inputs, so marginal cost behaves differently and is generally smoother. A lot of bad strategic decisions come from applying short-run marginal logic to a long-run problem or vice versa. There is also the issue of measurement. Marginal analysis sounds clean on paper, but in reality, isolating the cost or revenue of one additional unit is often messy. Costs are shared across products. Revenue can be influenced by brand perception, seasonality, and customer behavior that has nothing to do with the unit in question. I worked on a pricing model for a software company where the marginal cost of one additional license was essentially zero, which made the marginal analysis trivially favorable. But the company also had to consider the impact on their existing customer base, support load, and upgrade paths. The pure marginal calculation said yes immediately, but the broader economic picture required a more cautious rollout strategy. Marginal analysis gives you a signal, not a verdict. The biggest limitation of marginal analysis is that it assumes rational actors with perfect information, which is almost never true. People do not always know their marginal costs. They do not always know their marginal revenues. They make decisions based on gut feeling, habit, or incomplete data. Marginal analysis is a framework for thinking clearly, not a crystal ball. It works best when you have decent data and use it as a discipline to challenge your assumptions, not as a command to follow blindly.
Get the Full Details
If you are trying to apply this practically, start by identifying the decision you are facing and isolating what actually changes. List the incremental revenues and incremental costs. Ignore the sunk costs and the fixed allocations that do not move. Do the math. Then check your assumptions against reality. If the marginal cost curve looks suspiciously flat, it probably is not. If the marginal revenue looks too good, it probably is. The framework is only as good as the data you put into it.