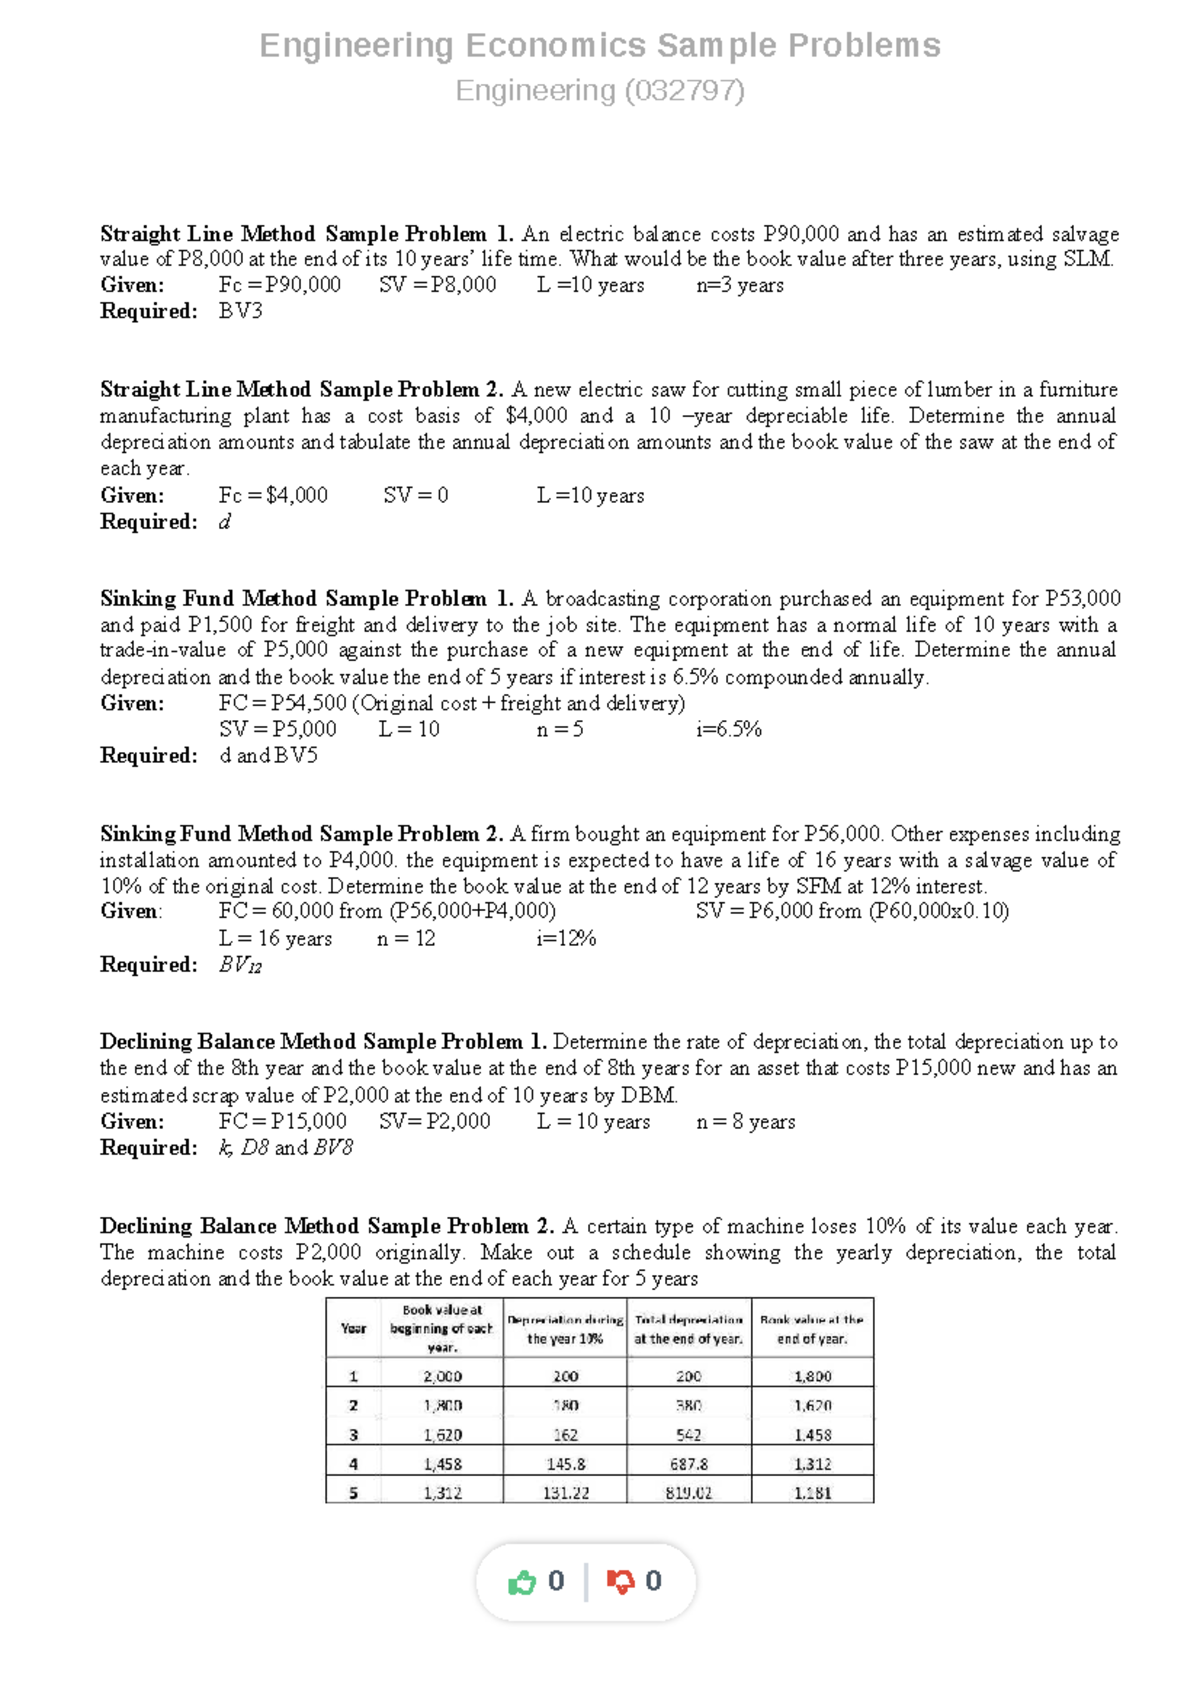
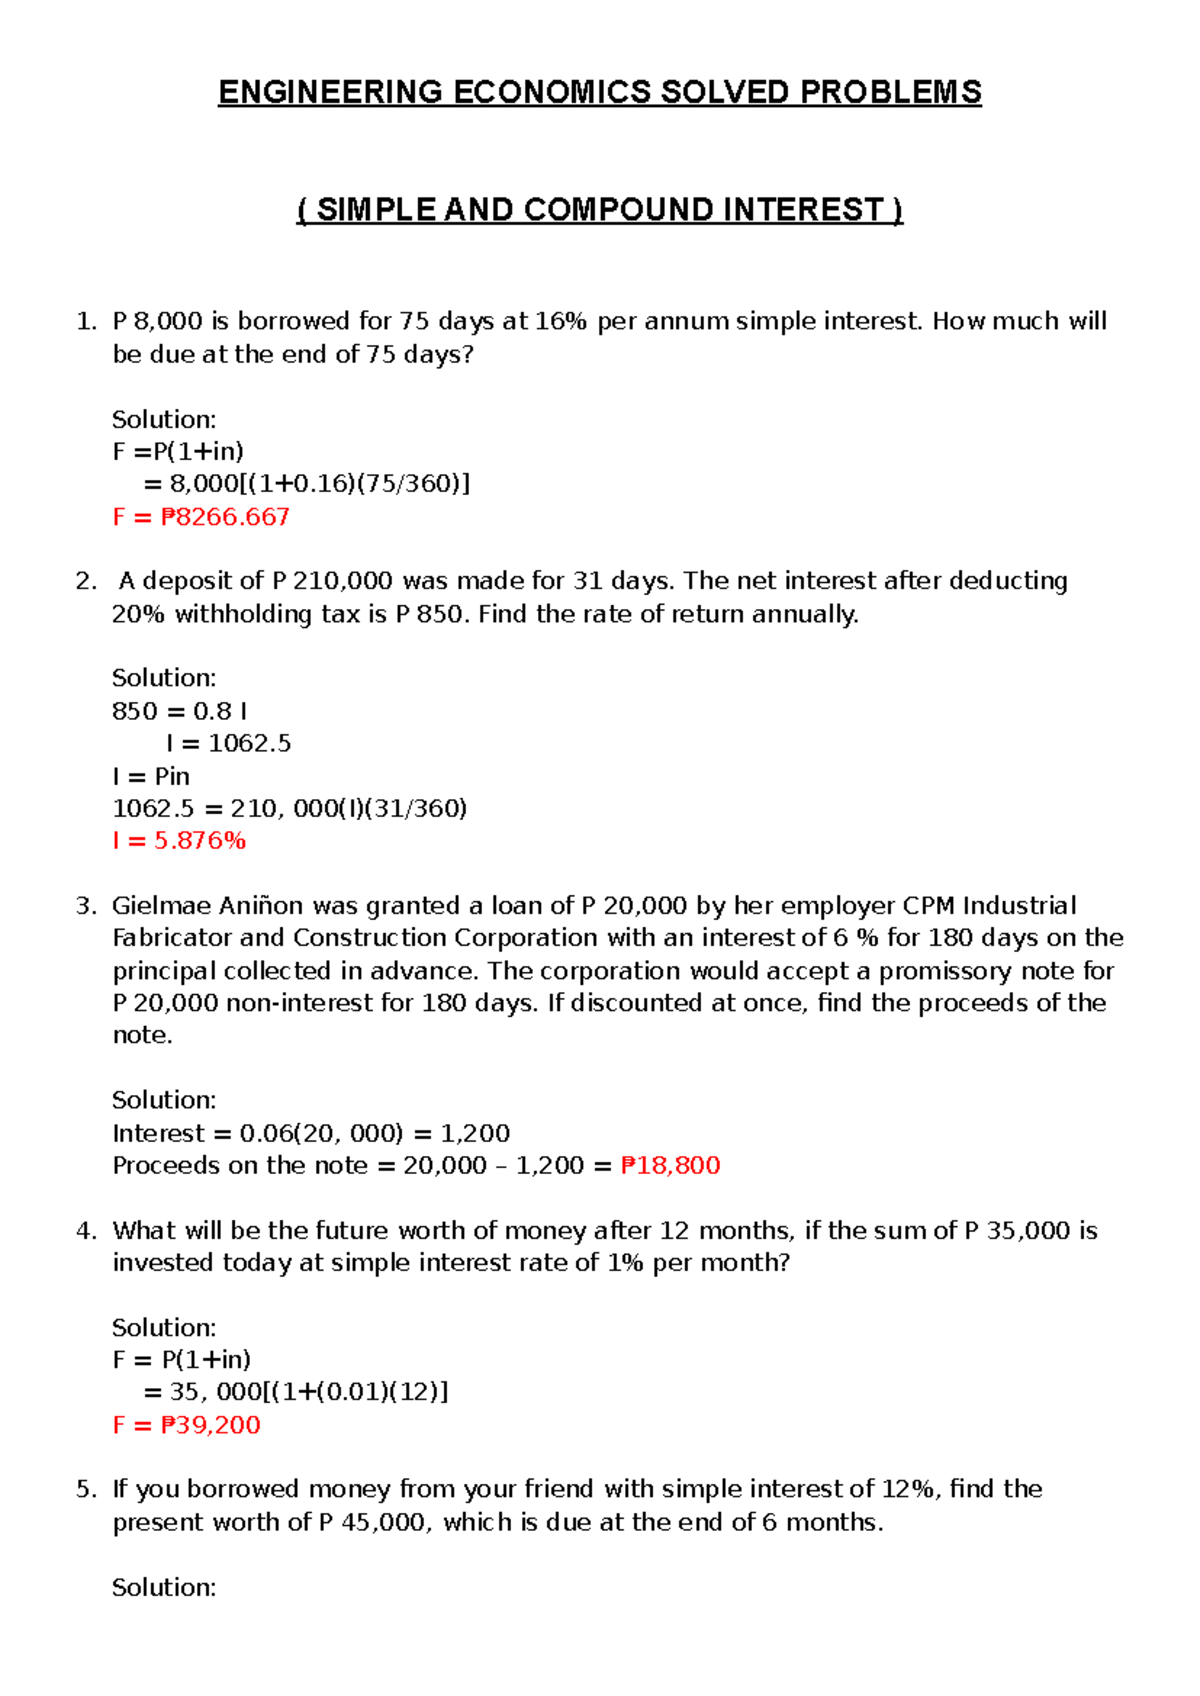
Working Through Engineering Economics Problems by Hand
Most people approach engineering economics problems the same way—open the textbook, find the formula table, plug in the numbers, get the answer. It works fine for homework. The moment you leave academia, the problems stop looking like clean annuities and start looking like spreadsheets with missing data. I learned that the hard way. Here's the thing nobody tells you in class: Engineering Economics Problems becomes frustrating quickly because the standard formulas assume uniform cash flows occurring at exact intervals. Real equipment replacement decisions don't work like that. Salvage value isn't predictable. Operating costs climb every year, not all at once. Inflation hits unevenly across categories. I worked on a project a few years ago where we needed to compare two HVAC systems for a commercial building retrofit. System A had a higher upfront cost but lower maintenance. System B was cheaper to buy but required a major overhaul every seven years. The textbook approach would have been to calculate the equivalent annual cost of each and pick the lower one. Instead, I built a year-by-year cash flow model that accounted for the fact that the overhaul in year seven would hit in Q3, not at the end of the fiscal year, and that labor rates for the repair were escalating at roughly 4% annually while parts were tied to a different inflation index. The difference between the two systems flipped depending on whether we used a 5% or 7% discount rate. That kind of sensitivity doesn't come out of a factor table.
What helped me was breaking the problem into separate cash flow streams rather than trying to force everything into a single equivalence formula. I treated the initial purchase, the annual maintenance, and the mid-life overhaul as three independent components, calculated their present worth separately, and then summed them. It took longer on paper but reduced the chance of making a compounding error when I moved to Excel later.
The Core Techniques You Actually Need
Present worth analysis is the foundation. You take all future cash flows and discount them back to time zero using your minimum attractive rate of return. If the present worth is positive, the project meets your hurdle rate. If it's negative, walk away. That's the basic logic. The complicated part is knowing what to include in the cash flow and what to exclude. Sunk costs are the most common mistake. Money already spent on preliminary studies, environmental assessments, or prototype development doesn't belong in the analysis. People include it because it feels wrong to ignore it, but from an engineering economics standpoint, it's irrelevant. The decision point is now. Everything before now is history. Opportunity cost is the other one people skip. If you use an existing building for a new project, you need to include the forgone revenue from not leasing it out. I've seen this leave millions of dollars on the table in municipal projects where public assets were evaluated without any rental income assumption.
Get the Full Details

When you're comparing alternatives with different lifespans, you can't just compare their present worth directly. A ten-year project will naturally have a higher present worth than a five-year one if they generate similar cash flows, simply because it has more years of income. You need to use the annual worth method or a common analysis period. The annual worth method converts all cash flows into an equivalent uniform annual amount over the asset's life. It handles different lifespans cleanly because it normalizes everything to a per-year basis.
Interest Rate Problems and theIRR Trap
Internal rate of return sounds elegant. It's the discount rate that makes the net present worth equal zero. But it has serious limitations that aren't emphasized enough in introductory courses. First, a project can have multiple IRRs if the cash flow changes sign more than once. A project with an initial investment, a large positive cash flow in year three, and another large negative outflow in year five might spit out two different rates that both make NPV zero. Which one is the "correct" answer? Neither. The math is broken for that cash flow pattern, and you need to fall back on present worth analysis at your actual required rate instead. Second, the IRR method implicitly assumes that intermediate cash flows can be reinvested at the IRR itself. That's almost never realistic. If your project has an IRR of 18%, you shouldn't assume you can reinvest every interim dollar at 18%. The modified internal rate of return fixes this by using a separate reinvestment rate, usually your cost of capital, but most people don't bother because it's one extra calculation step.
For practical work, I default to present worth for single-project evaluation and annual worth for comparing mutually exclusive alternatives. I only use IRR when someone in management specifically asks for it, and even then I always cross-check with NPV at the actual discount rate.

A Working Example I Actually Use
Say you're evaluating a piece of industrial equipment that costs 85,000 dollars, has a useful life of eight years, and will save you 16,000 dollars per year in operating costs. Your MARR is 10 percent. There's no salvage value. You need the present worth factor for a uniform series at 10 percent for eight periods. That factor is 5.3349. Multiply 16,000 by 5.3349 and you get 85,358 dollars. Subtract the initial cost of 85,000 and your net present worth is positive by 358 dollars. Marginal, but positive. The project barely clears the hurdle. Now say the equipment actually has a salvage value of 12,000 dollars at the end of year eight. You need to discount that single future amount back to present value. The factor is 0.4665. Multiply that by 12,000 and you get 5,598 dollars. Add that to the previous present worth and your total NPV jumps to about 5,956 dollars. That changes the decision significantly. A small salvage value assumption made the difference between a marginal pass and a clear go.
This is why getting the salvage value right matters more than the textbook examples suggest. A 10 percent error in salvage value can flip your conclusion on a tight project.
Where This All Breaks Down
Engineering economics problems become unreliable when the discount rate is uncertain or when the project spans more than fifteen to twenty years. Small changes in the assumed rate create massive swings in present worth for long-duration projects. A 1 percent shift in the discount rate can change a present worth calculation by 15 to 20 percent over a twenty-year horizon. At that point, the precise decimal on your NPV is meaningless because your rate assumption is already loose. The method also fails when cash flows are highly irregular and unpredictable. If you're evaluating a research and development project where the payoff comes as a lump sum at an unknown future date, equivalence analysis becomes guesswork. In those cases, real options analysis or scenario-based Monte Carlo simulation gives you more useful information than a single NPV figure. Another practical limitation: engineering economics problems typically treat inflation as a uniform percentage applied to all line items. In reality, some cost categories inflate faster than others. Energy costs, labor rates, material prices—each follows its own trajectory. If you're doing a detailed evaluation, you should apply different escalation rates to different categories rather than using a single blanket inflation factor. It takes more effort but produces a result that's closer to what actually happens.

What I Actually Do Before Sending Numbers Upward
Build a year-by-year cash flow schedule first. Don't jump into formulas. Write out every inflow and outflow for every year of the analysis period. Put it in a table. Check that the signs make sense—outflows negative, inflows positive. Verify that no year is missing data. This alone catches about half the errors I've seen in practice. Then calculate present worth, future worth, and annual worth for the base case. Run a sensitivity check at plus or minus 2 percent on the discount rate and plus or minus 10 percent on the major cost categories. If your recommendation flips under reasonable variations, you don't have a strong case. You have a fragile one, and you should present it that way rather than hiding the uncertainty behind a single precise number. The goal isn't to get the math perfect. It's to give decision makers enough clarity that they understand what assumptions drive the result and where the risk lives. Engineering Economics Problems gives you the structure for that. The structure only works if you respect its limits.