Getting Through Part 1 of the EA Exam
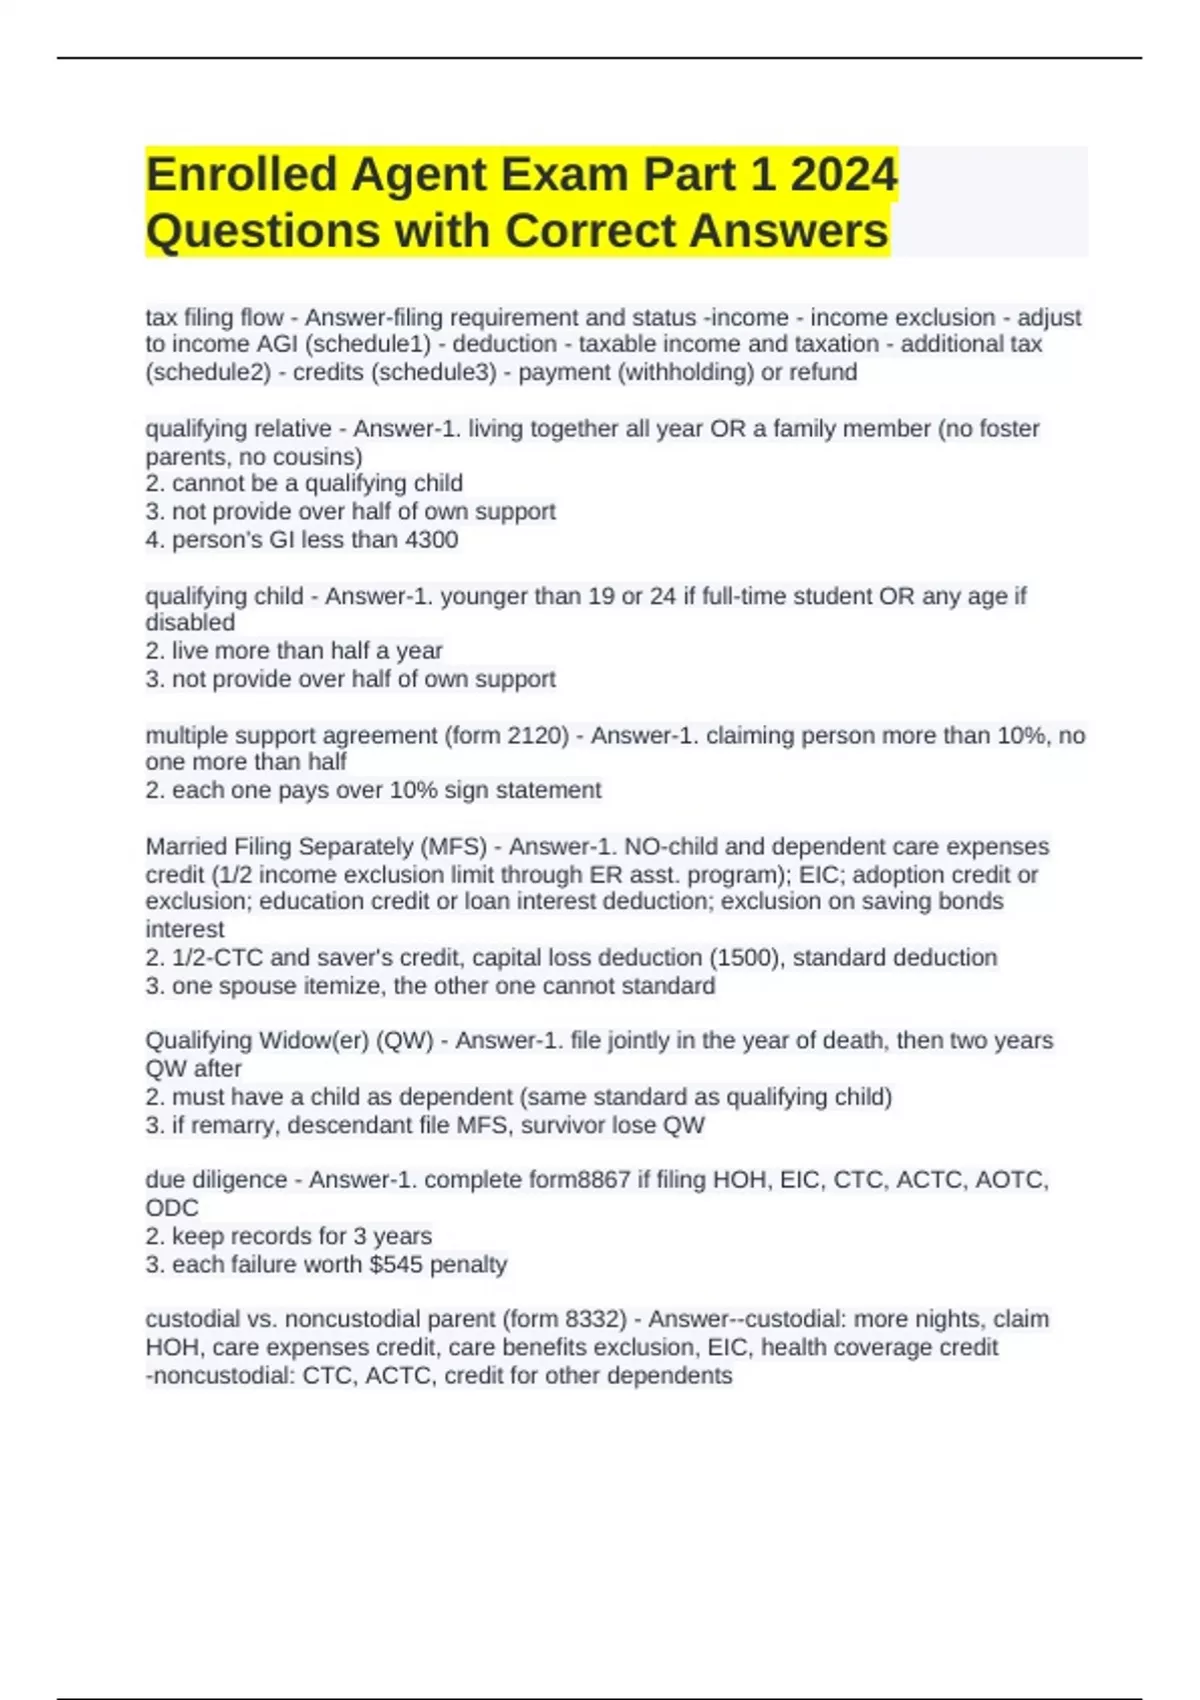
Part 1 of the Enrolled Agent Exam covers Individual Taxation. That means Forms 1040, every schedule attached to it, and the credits and deductions that actually show up on returns for regular people. It is the most straightforward section of the three-part exam, which is both good news and bad news. Good because the material is concrete and practical. Bad because people underestimate it and walk into the testing center thinking they can wing it. The content breaks into a few categories. Filing statuses and dependency rules take up a meaningful chunk. You need to know head of household qualifications cold, not just the basic definition. The tiebreaker rules for dependents when two taxpayers both claim the same child are tested, and people get tripped up on those. Standard deduction amounts change every year and the exam gives you a table, but you still need to know when the additional standard deduction applies for age or blindness. That is a frequent question type. Schedules A, B, D, 1, 2, and 3 all appear. Itemized deductions on Schedule A require knowing the limits on medical expenses, state and local tax deductions capped at ten thousand dollars, and casualty loss rules which are basically nonexistent after the TCJA except for federally declared disasters. Capital gains on Schedule D involve wash sale rules, basis calculations, and the difference between short-term and long-term treatment. Interest and ordinary income on Schedule B includes tax-exempt interest reporting and original issue discount. Income adjustments and IRA penalties on Schedule 1, plus the additional Medicare tax and net investment income tax on Schedule 3.
Credits are where a lot of the exam weight sits. The child tax credit, dependent credit, EITC, American opportunity credit, lifetime learning credit, childcare credit, premium tax credit. You need to know the phaseout ranges, eligibility requirements, and recapture situations. The EITC has its own world of rules around qualifying children, disqualified persons, and foreign address requirements. Get comfortable with Form 8862 requirements for taxpayers who had their EITC denied in a prior year.
How the Exam Actually Works
It is a computer-based test at Prometric. You get about three and a half hours for roughly one hundred scored questions plus ten unscored pretest items. The interface lets you flag questions and come back to them. Use that feature. I took this exam during a period when the IRS was still transitioning to modified standard deduction tables for mid-year legislation changes, and the practice questions in some review courses had not caught up. The actual exam interface displayed current tables, but a couple of review books still had 2022 numbers printed in their examples. It does not matter what your review material says. The exam gives you what you need on screen. One thing nobody tells you about the testing center experience is the noise level. I have sat through Part 1 in a center where the HVAC system cycled on every twelve minutes with a mechanical clunk that sounded like a gunshot. You cannot ask them to fix it without losing testing time. Bring earplugs if you are sensitive to that. The mouse and keyboard are provided but they are generic. If you type with two fingers you will not finish comfortably. The exam uses a four-function calculator within the interface. I never used it. If you are doing basic arithmetic from memory you will move faster. For anything involving installment sales or depreciation calculations you will want scratch paper, which they provide. The scratch paper is collected at the end so you cannot write formulas on it and keep it, but you can reference it during the exam.
Get the Full Details

Common Pitfalls That Keep People from Passing
The biggest mistake I see is treating this like a memorization test. It is not. The questions present scenarios. You might be asked to calculate a taxpayer's adjusted gross income given a list of income items and adjustments, or determine whether a credit is allowed based on a cluster of facts. If you only memorized that the child tax credit is two thousand dollars you will miss the questions about phaseouts at higher AGI levels for married filing separately, which is a specific rule people overlook. Another pitfall is not reading the question all the way through. I once saw a candidate spend two minutes working out a complex EITC calculation only to realize the actual question asked whether the taxpayer was disqualified due to having disqualifying investment income above the threshold. The investment income limit changes annually and you need to know roughly where the cutoff sits. It was eight thousand something in recent years. You do not need to memorize the exact number because it is provided, but you need to know the concept exists and where to find it in the exam interface. People also skip over the pretest questions thinking they are all scored. Ten are unscored and you cannot identify which ones they are. Do not guess that the harder questions at the end are the pretest items and relax. They are randomly distributed throughout the exam. Treat every question as if it counts.
A Practical Workaround I Developed
When I was studying, I hit a wall with the premium tax credit reconciliation on Form 8962. The worksheet calculations involving the second lowest cost silver plan benchmark and the household income percentage were easy to mess up, and the exam liked to throw in edge cases where the taxpayer had a qualifying life event mid-year that changed family size. My workaround was to build a small spreadsheet that walked through the calculation step by step with sample numbers I generated myself. I would create a scenario, work through the form line by line, check my answer against the actual instructions, and then vary one variable at a time to see how the outcome changed. This took about forty-five minutes of focused work but it took the concept from vague to mechanical. You can do something similar without building an actual spreadsheet. Just use paper and walk through at least five different scenarios by hand until the steps feel automatic. Part 1 focuses on individual taxation in a relatively clean, textbook way. It does not test complex multi-state issues, trust and estate taxation, or the kind of messy real-world situations where a taxpayer has unreported cash income and no records. If your goal is to handle complicated individual returns in practice, you will need supplemental study beyond this exam. The exam validates that you know the code as written, not necessarily that you can navigate the gray areas that show up in actual tax preparation work. That is a limitation of the test itself, not a reflection on your abilities. You schedule through Prometric after receiving your Authorization to Test from the IRS. The scheduling window typically opens a few days after authorization is processed. I recommend booking a slot at least two weeks out because popular centers fill up, especially during peak exam months from January through April. Arrive fifteen minutes early. The check-in process involves photo identification verification and palm vein scanning at some locations. Bring a government issued photo ID that has your signature. A passport works. A learner's permit does not if it lacks a signature line.
The exam costs three hundred and seventy-five dollars as of the current fee schedule. Payment is required at scheduling. If you need to cancel or reschedule you must do so at least thirty days before your appointment or you forfeit the fee. Thirty days sounds generous but it passes quickly during tax season.
Bottom Line
Part 1 is manageable if you treat it with the same seriousness you would give Part 2 or Part 3. The material is dense but narrow. Focus your study on the areas that actually appear on the exam rather than trying to master every possible nuance of individual taxation. Practice with questions that mirror the scenario-based format of the real thing. And do not let the reputation of this section as the easiest one make you complacent about preparation time.