Why the epsilon-delta definition feels like pointless torture (and why you actually need it)
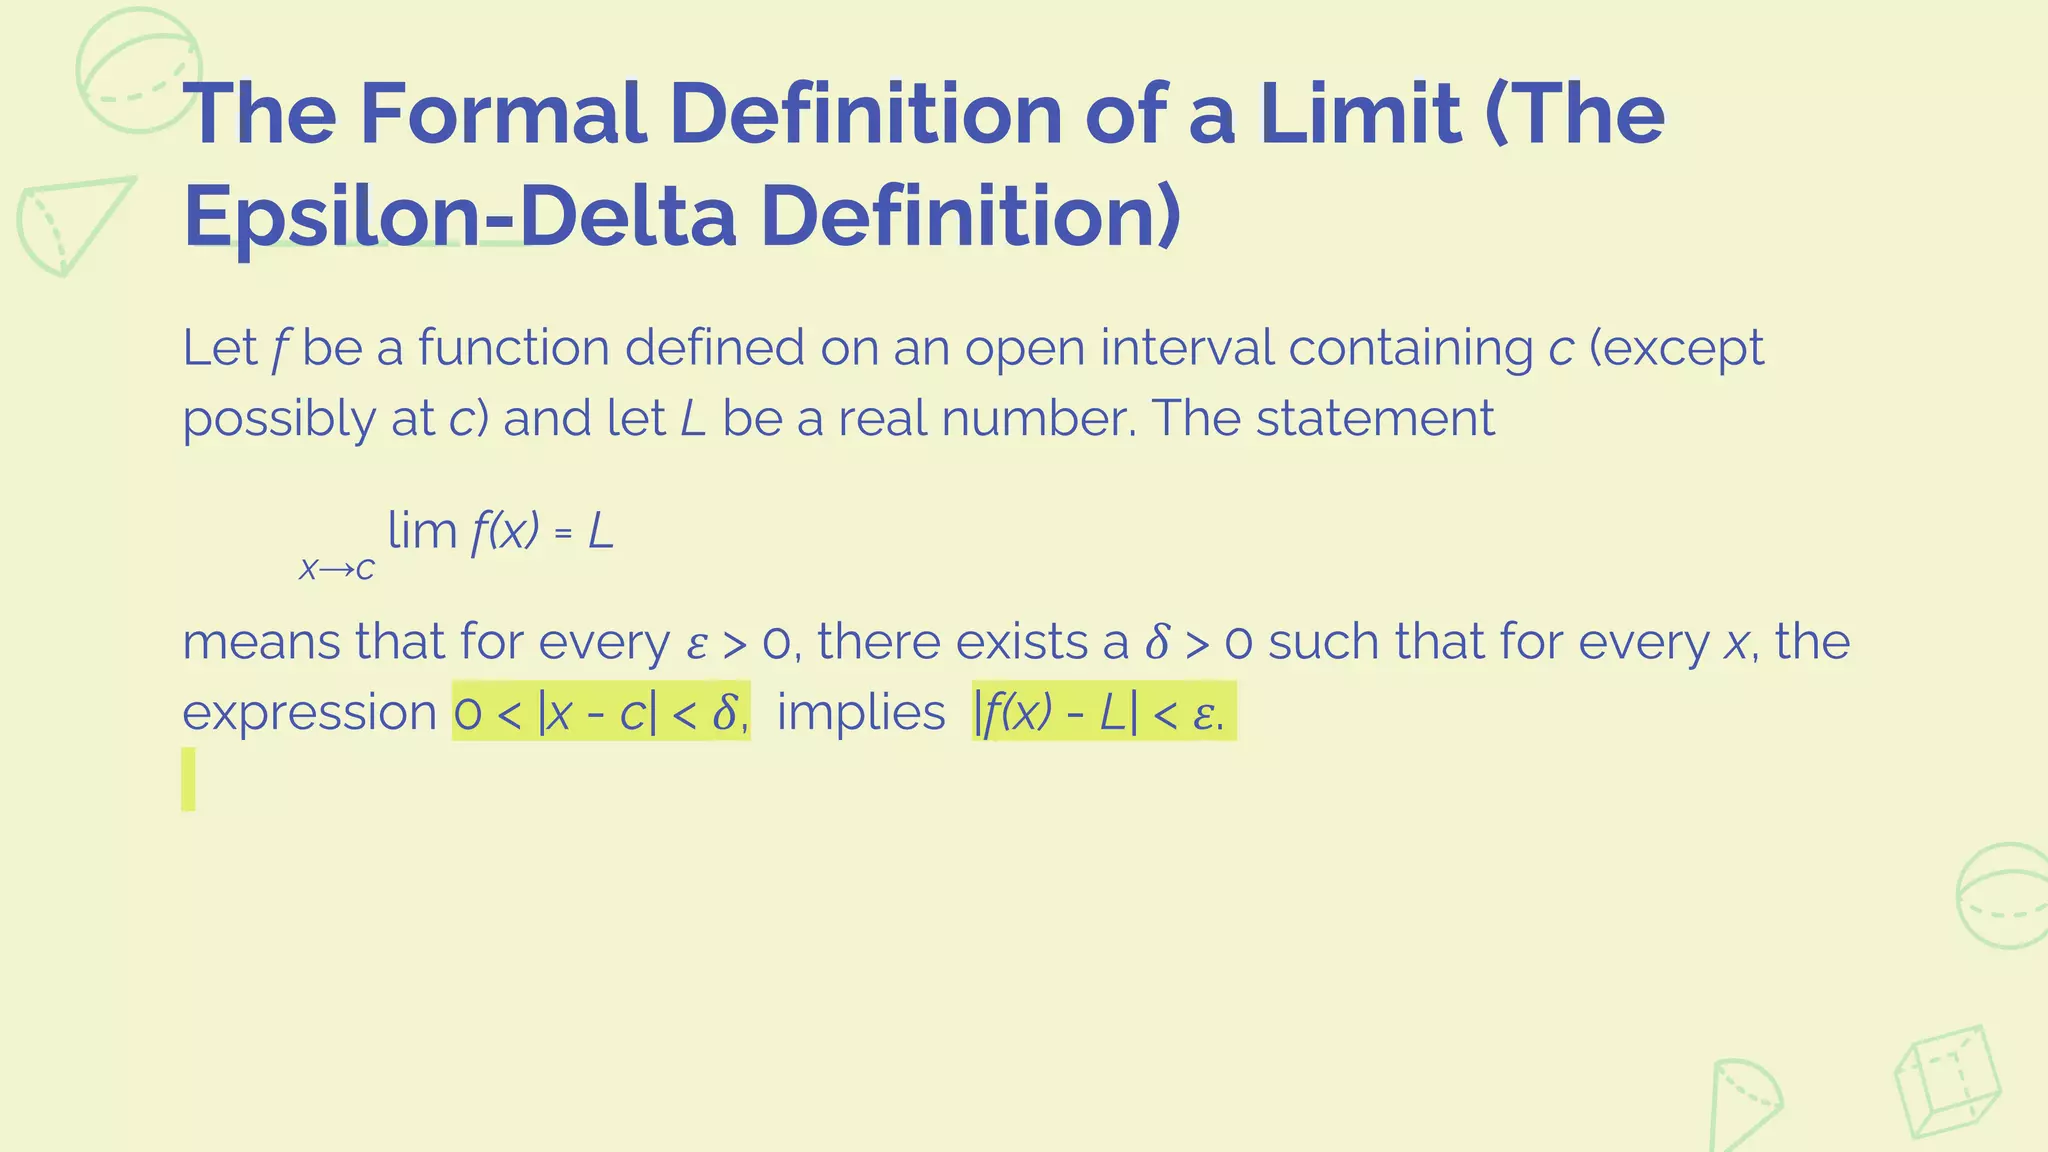
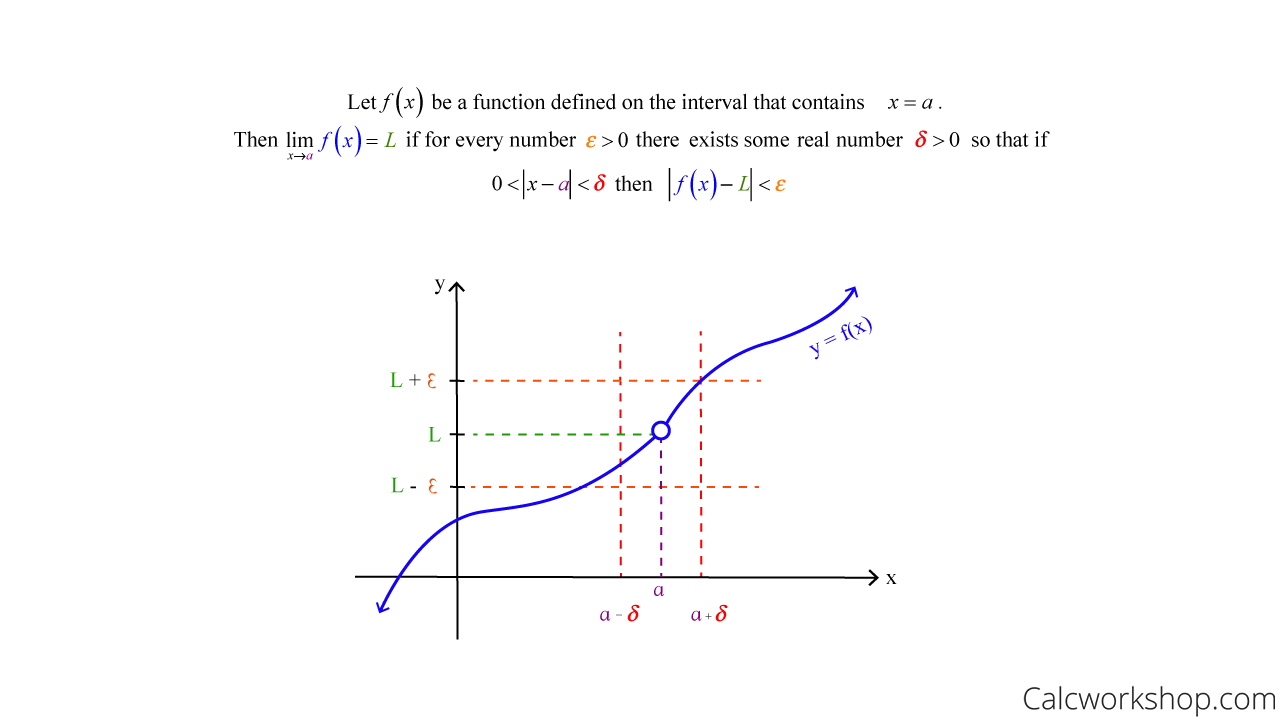
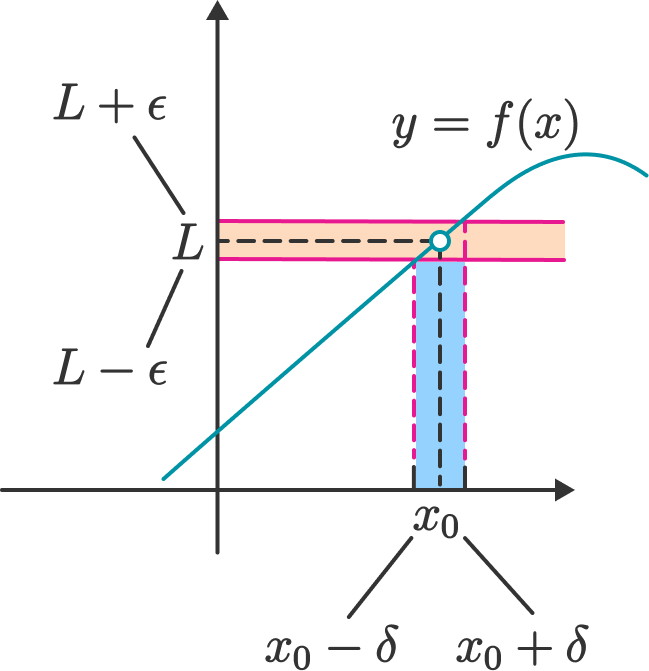
The epsilon-delta definition limit is how calculus actually defines what a limit is. Not how we compute it day to day, but how we prove that our intuition is correct. Most students hit it in their first real analysis class and immediately want to go back to using L'Hopital's rule and call it a day. I get it. Here's the definition first, since people usually learn it backwards. For a function f(x), the limit as x approaches c equals L means this: for every positive number epsilon, no matter how small, there exists a positive number delta such that whenever 0 < |x - c| < delta, then |f(x) - L|
epsilon. In plain terms: you can force f(x) to be as close to L as you want by making x close enough to c. That's it. The technical machinery is just making that sentence mathematically rigorous.
Using the Epsilon Delta Definition Limit to Prove Statements
The method is always the same structure, even though the algebra changes. Start with |f(x) - L| and try to bound it by something involving |x - c|. Then find a delta that makes that bound smaller than epsilon. Let me show you with a concrete example because that's where people get stuck. Prove that lim(x3) (2x + 1) = 7. Work backwards from the conclusion first. I always tell my students to do this. Start with |f(x) - L| < epsilon. That gives |2x + 1 - 7| < epsilon, which simplifies to |2x - 6| < epsilon, which becomes 2|x - 3| < epsilon, and finally |x - 3|
epsilon/2.
So delta equals epsilon over 2. Write it up formally: given epsilon greater than zero, choose delta equal to epsilon over 2. Then if 0 < |x - 3| < delta, we have |2x + 1 - 7| = 2|x - 3|
2*delta = 2*(epsilon/2) = epsilon. Done. QED. That example is trivial because it's a linear function. The algebra unwinds cleanly. The real problems come when you deal with rational functions or anything with x² involved. Those require extra steps that trip people up constantly. I ran into a particularly ugly case once working on a proof for lim(x2) (x² - 4)/(x - 2) = 4. The function simplifies to x + 2 everywhere except at x = 2, but you can't just simplify and call it done because the whole point is handling the undefined point. When I was bounding |x + 2 - 4|, I got |x - 2|, which looked straightforward. But then I had a student try to apply the same logic to lim(x1) (x² + 3x - 4)/(x - 1) and got completely stuck because the simplification gave x + 4 and the bound became |x - 1| directly, but they couldn't figure out how to handle the fact that delta had to work for the original unsimplified expression. The workaround was to explicitly state the domain restriction first, show the simplification is valid for x 1, and then treat it exactly like the linear case. It's a subtle distinction that doesn't show up in textbooks but matters in practice.
Get the Full Details

For quadratic functions, here's what actually happens. You'll end up with something like |x² - 4| and you need to factor it to |x - 2|*|x + 2|. The |x - 2| part becomes your delta candidate, but the |x + 2| part is the problem because it varies with x. You have to bound it by assuming delta is less than or equal to 1, which restricts x to be between 1 and 3, making |x + 2| less than 5. Then delta becomes min(1, epsilon/5). That min function is non-negotiable and shows up in basically every quadratic limit proof. Common pitfall: students forget to actually use the min. They just write delta = epsilon/5 and the proof falls apart because their bound on |x + 2| was never justified. You have to show that your delta choice keeps x in a range where your bound holds. This is the step that separates people who understand the definition from people who just memorized a template. Another thing nobody emphasizes enough: the definition doesn't care about what happens at x = c. That's why we write 0
|x - c|. The function can be completely undefined at c, wildly discontinuous there, whatever. The limit only cares about the neighborhood around c, not c itself. I've seen people lose points on exams for writing proofs that accidentally included the value at c, which defeats the whole point.
Now, some honest limitations. The epsilon-delta approach doesn't scale well for complicated functions. Proving lim(x0) sin(x)/x = 1 using pure epsilon-delta is possible but genuinely painful. You need geometric arguments or the squeeze theorem first, then you build up to epsilon-delta from there. Trying to do it from scratch with just the definition will take you twenty minutes and three pages of inequalities that go nowhere. Also, for piecewise functions or functions defined on discrete domains, the standard epsilon-delta definition either needs modification or doesn't apply at all. If you're working with sequences instead of functions, you switch to the N-epsilon definition, which is structurally identical but uses integers. The underlying logic is the same, but mixing them up in a proof gets you penalized every time. The one advantage this definition has over intuitive approaches is that it catches edge cases that intuition misses. Functions like f(x) = sin(1/x) near x = 0 look like they should have a limit if you're not paying attention. The epsilon-delta definition proves rigorously that they don't, because no matter how small you make delta, the function oscillates through every value between -1 and 1. Intuition fails there. The definition doesn't.
If you want to practice, the best exercises are: prove limits for linear functions (easy), then rational functions that simplify (medium), then polynomial functions requiring the min technique (harder), and finally try one with a square root where you need rationalization. That progression takes most students about two weeks of focused work to get comfortable with. After that, you mostly use the definition to prove theorems about limits rather than computing individual limits from scratch.