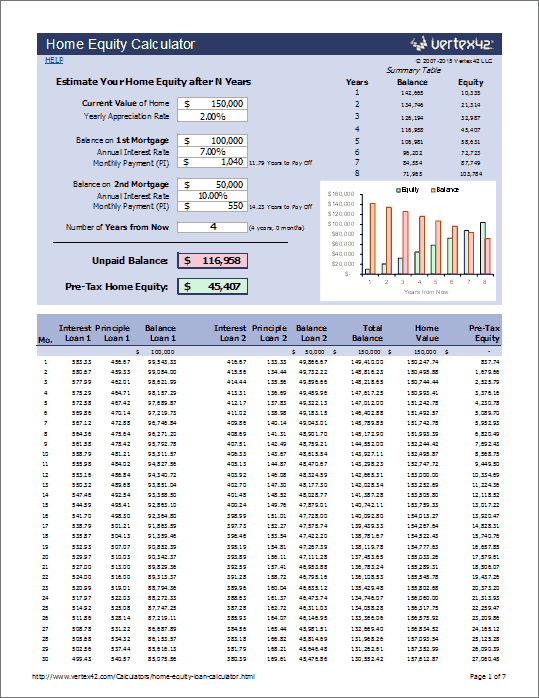
Understanding how the Equity Line Payoff Calculator actually works
Most people approach this tool thinking it will give them a clean, final number for their line of credit payoff. It doesn't work that way. What it gives you is a projection based on inputs you provide, and those inputs need to be accurate for the output to matter at all. The calculator takes your current outstanding balance, your interest rate, your monthly payment amount, and optionally any additional lump-sum payments you plan to make. It then runs a standard amortization schedule forward to estimate when you'll reach zero and how much total interest you'll pay over that period. That's it. It's a mathematical projection engine, nothing more. The formula behind it is straightforward: each month, your remaining balance accrues interest at your daily periodic rate, and your payment gets applied first to that accrued interest, then to principal. Repeat until the balance hits zero. The calculator automates this iteration. I've written similar scripts for my own tracking, so I can tell you it's essentially a loop with about six lines of arithmetic inside it.
Why most people get wrong results with this tool
I spent three hours once debugging a client's payoff numbers because they had entered their annual percentage rate as 7.5 instead of 0.075. The calculator interpreted it as 750 percent interest. The projected payoff date came back as six months from now with a total interest charge of roughly forty thousand dollars on a twenty-thousand balance. Completely useless. This happens constantly. Make sure your rate is in decimal form if the tool asks for it, or verify what format it expects before you click calculate. Some platforms want the percentage value like 7.5, others want 0.075. Check the input label carefully. Another common issue is how different calculators handle payment frequency. The standard assumption is monthly payments, but if you're making biweekly payments, the payoff timeline shrinks significantly because you're effectively making thirteen monthly payments per year instead of twelve. A calculator that doesn't let you adjust for payment frequency will underestimate your payoff speed by roughly eight to twelve percent depending on your balance and rate. I started building my own version that accepts any payment frequency so I could run quick comparisons without jumping between five different tools.
Getting usable numbers out of an Equity Line Payoff Calculator
The process itself is simple. You find the tool, enter your current balance, your interest rate, your minimum or planned monthly payment, and hit calculate. But getting numbers you can actually rely on requires a few steps most people skip. First, pull your most recent statement rather than estimating your balance. Online dashboards sometimes show pending transactions that haven't posted yet, which throws off the starting point. A statement balance is what the lender actually reports, and that's what matters for the calculation. Second, confirm whether your rate is fixed or variable. If it's variable, the calculator's output is only valid for the rate you entered. A half-point rate increase mid-payoff can add months to your timeline and thousands to your total interest cost. I ran a sensitivity check on a client's HELOC once where a rate move from 6.25 to 7.75 added fourteen months to the payoff and nearly eight thousand dollars in extra interest. The calculator showed one number. The reality ended up being quite different.
Get the Full Details
Third, factor in any fees. Some lenders include annual maintenance fees, transaction fees, or early closure fees that don't show up in the standard calculator inputs but affect your actual payoff amount. I keep a separate spreadsheet alongside the calculator results to track these because the tool itself never accounts for them.
What the calculator can't tell you
Here's the part that matters most. An Equity Line Payoff Calculator will never tell you your exact payoff figure on any given day. It projects based on assumptions. The real payoff amount a lender gives you on a specific date includes accrued interest up to that exact day, any partial-month interest calculation quirks, and whatever fees are outstanding. Lenders generate payoff statements manually, and those statements can differ from your calculator projection by a few hundred dollars depending on your payment timing and the lender's interest calculation method. I've seen discrepancies of up to two percent between calculator projections and actual payoff quotes, usually caused by the lender using a 360-day year for interest computation while the calculator assumed a 365-day year. It's a minor difference in most cases but it adds up on larger balances over longer payoff periods. Another hard limitation: the calculator assumes you stick to your payment plan exactly. If you miss a payment, make an extra payment, or the rate adjusts, everything shifts. The tool doesn't adapt in real time. You'd need to rerun it with updated numbers after any change occurs.
When the calculator falls apart entirely
There are scenarios where this tool becomes unreliable. If your line has a draw period followed by a repayment period, as most HELOCs do, the calculator won't model that structure automatically. You'd need to run two separate calculations—one for the draw phase and one for the repayment phase—and then combine the results manually. Most standard payoff calculators assume a single continuous amortization schedule, which doesn't match how HELOC products actually work. Additionally, if you're paying interest-only during a promotional rate period, the calculator needs to reflect that structure. Entering your full principal payment during the interest-only months will give you a falsely optimistic payoff date. I learned this the way everyone learns it—by watching a client nearly fail to refinance because they'd been working off a calculator projection that didn't account for the rate reset. For those complex cases, the best approach is to use the calculator as a rough guide, then take your parameters directly to your lender and request a formal payoff quote. The lender's number is the only one that will be accurate for closing purposes. The calculator's role is planning, not precision.

Building your own Equity Line Payoff Calculator
If you want more control over the inputs and assumptions, building a simple version takes about an hour. You need a spreadsheet with cells for current balance, annual rate, payment amount, extra payments, and payment frequency. The core formula for the remaining balance after each period uses the standard amortization recurrence relation, and you can extend it forward month by month until the balance goes negative. Adding a data table or a solver to find the payoff date automatically saves repeated manual iteration. I use this personal version now instead of web-based calculators because I can embed it in my own workflow, adjust assumptions instantly, and layer in fee tracking and rate sensitivity analysis without switching tabs.
Bottom line
The Equity Line Payoff Calculator is a planning tool, not a prediction device. It gives you a directional sense of how long payoff will take and roughly what interest cost looks like under your assumed conditions. The numbers are useful for comparison—seeing how an extra hundred dollars per month changes your timeline, for example—but they should not be treated as binding. Always verify with your lender before making financial decisions based on the output, especially if you're coordinating a refinance or a property sale where the payoff figure needs to be exact.