Writing a Retirement Letter That Actually Gets Processed
Most people treat a retirement letter like it's some kind of ceremonial speech. It isn't. It's a transactional document that triggers a cascade of HR, payroll, and benefits actions. Get it wrong and you can accidentally delay your last day, lose pension eligibility, or leave money on the table. Get it right and nobody even thinks about it after they file it. I've seen retirement letters do terrible things to otherwise straightforward exits. Two years ago I helped someone whose letter said "I'm retiring effective June 30th" without specifying which year. They'd clearly meant the upcoming one, but their company had a policy that fiscal-year retirements needed 90 days' notice for full benefit vesting. The date landed on a Thursday. The payroll team processed it against the wrong calendar quarter. That person lost about three weeks of vested benefits because the ambiguity made the system auto-route them to the prior cycle. Workaround was a short supplementary email quoting their original intent with the exact date and a direct request to confirm the processing period in writing. Got it the next morning.
Example Of Retirement Letter That Works
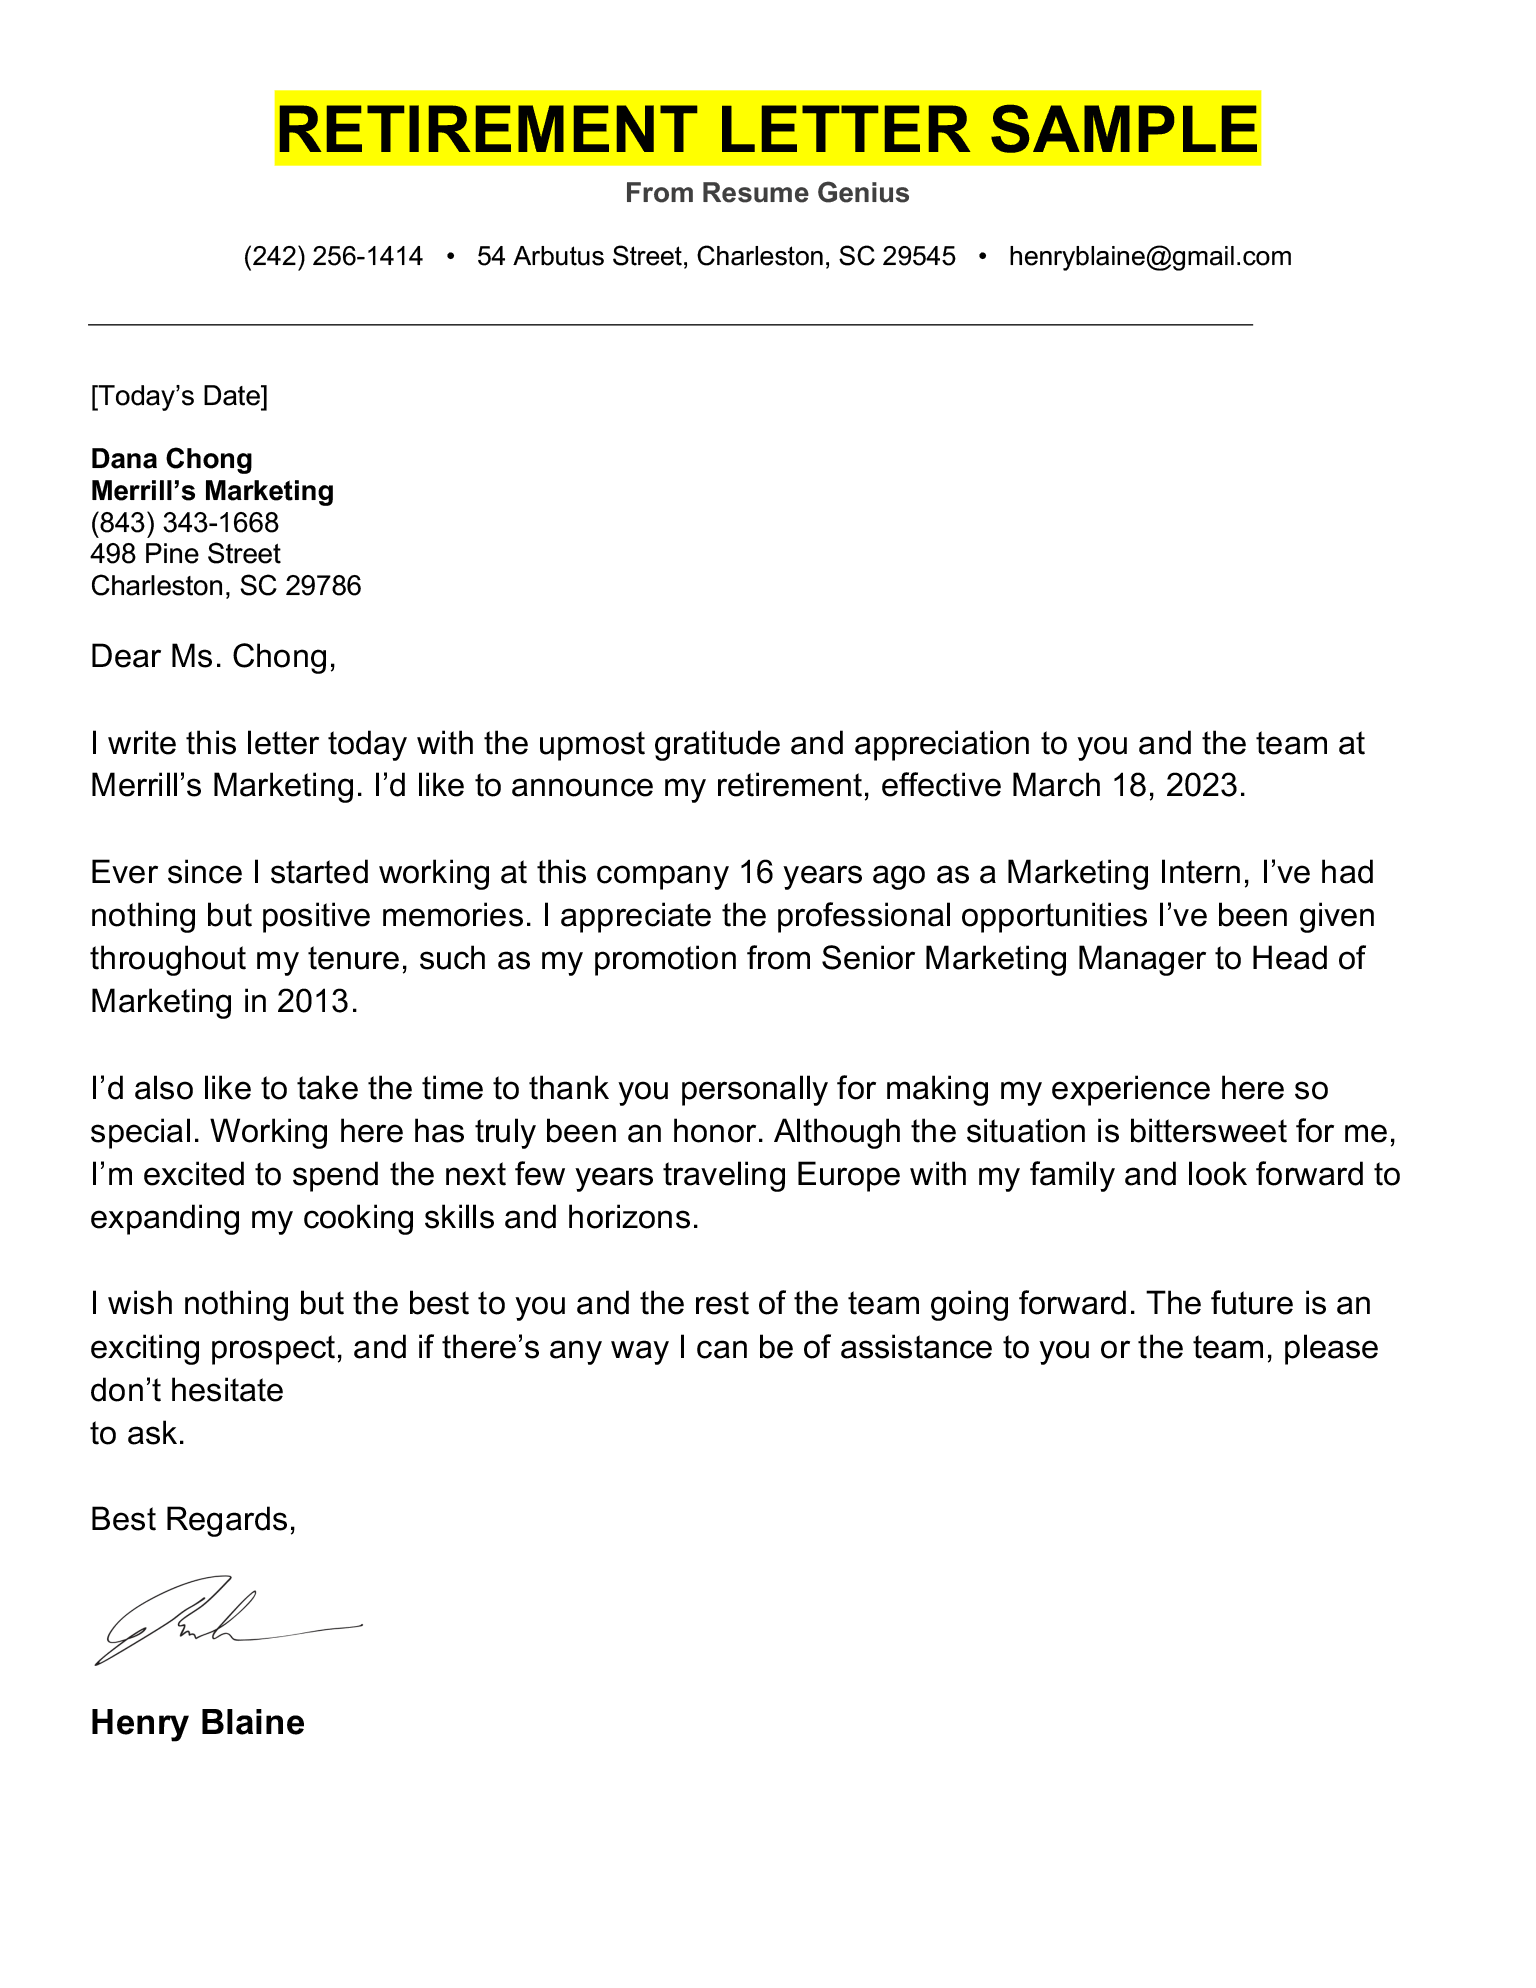
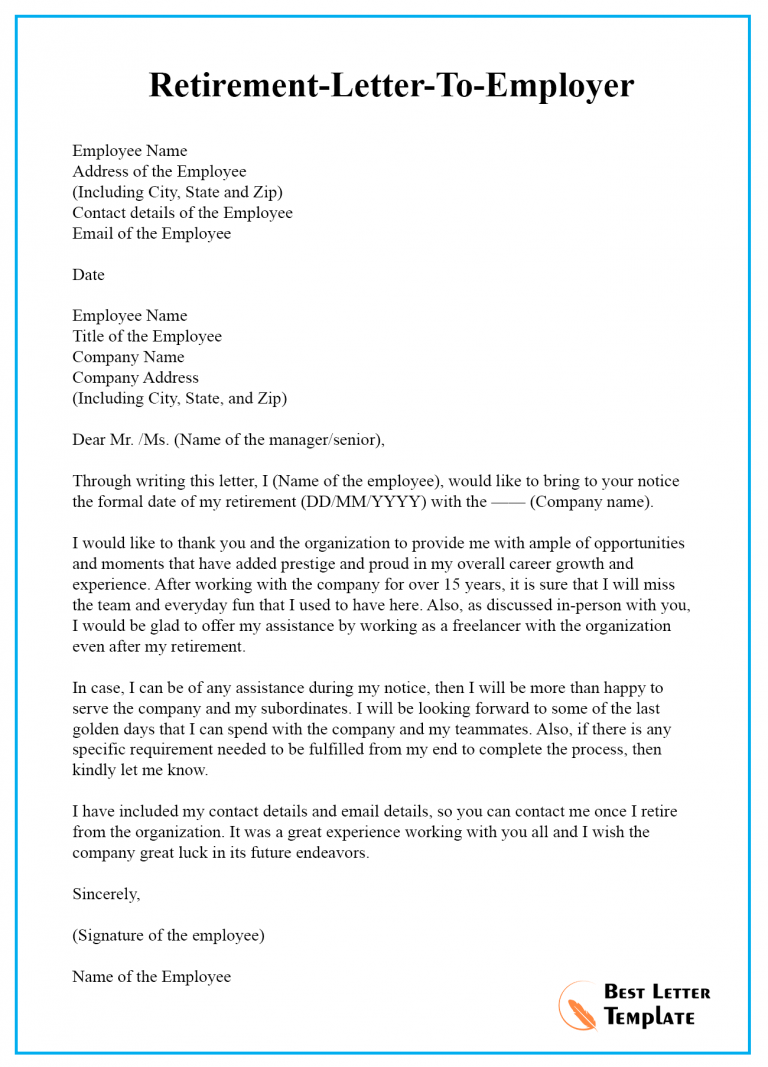
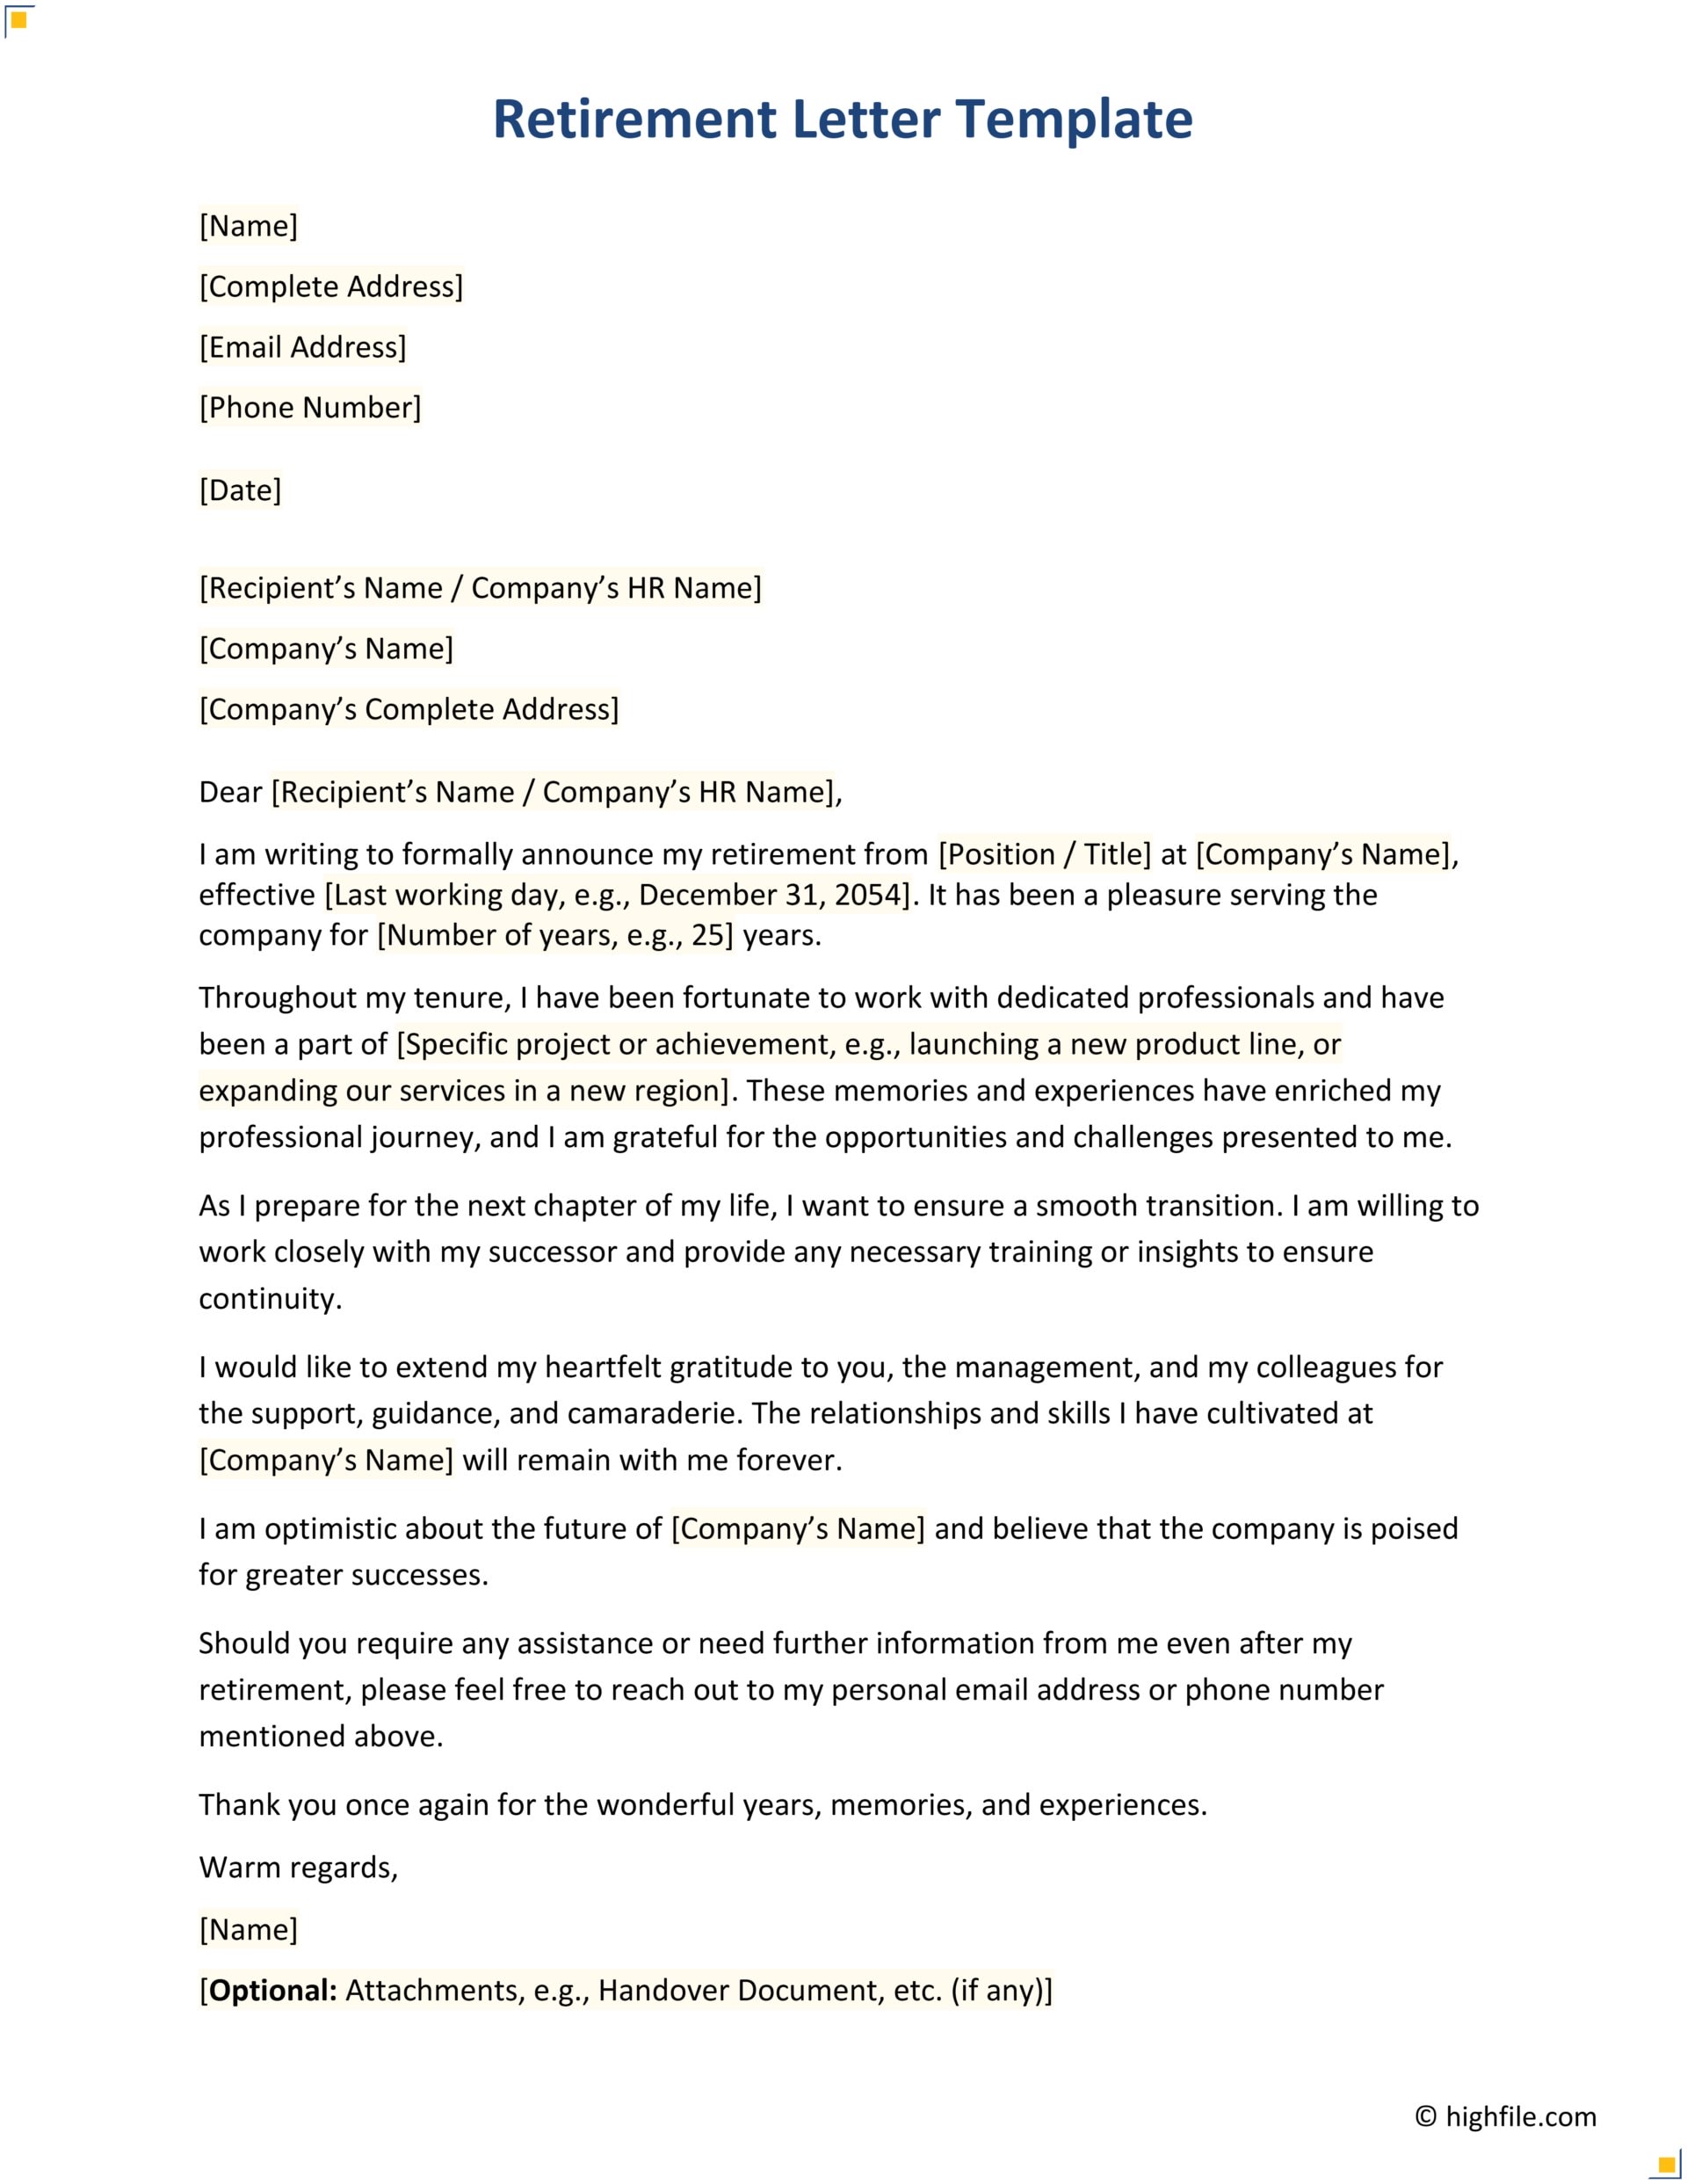
Here's what a solid one looks like. Keep it under 200 words. Anything longer and the reader's attention drifts to filler. Dear [Manager's Name], I am writing to formally notify you of my retirement from [Company], effective [exact date, including year]. My last day of work will be [date].
I want to confirm that this submission satisfies any notice period required under company policy. Please let me know if additional documentation or action is needed from me before my departure. I appreciate the opportunities I've had during my time here and am committed to ensuring a smooth transition over the coming weeks. Sincerely,
Get the Full Details
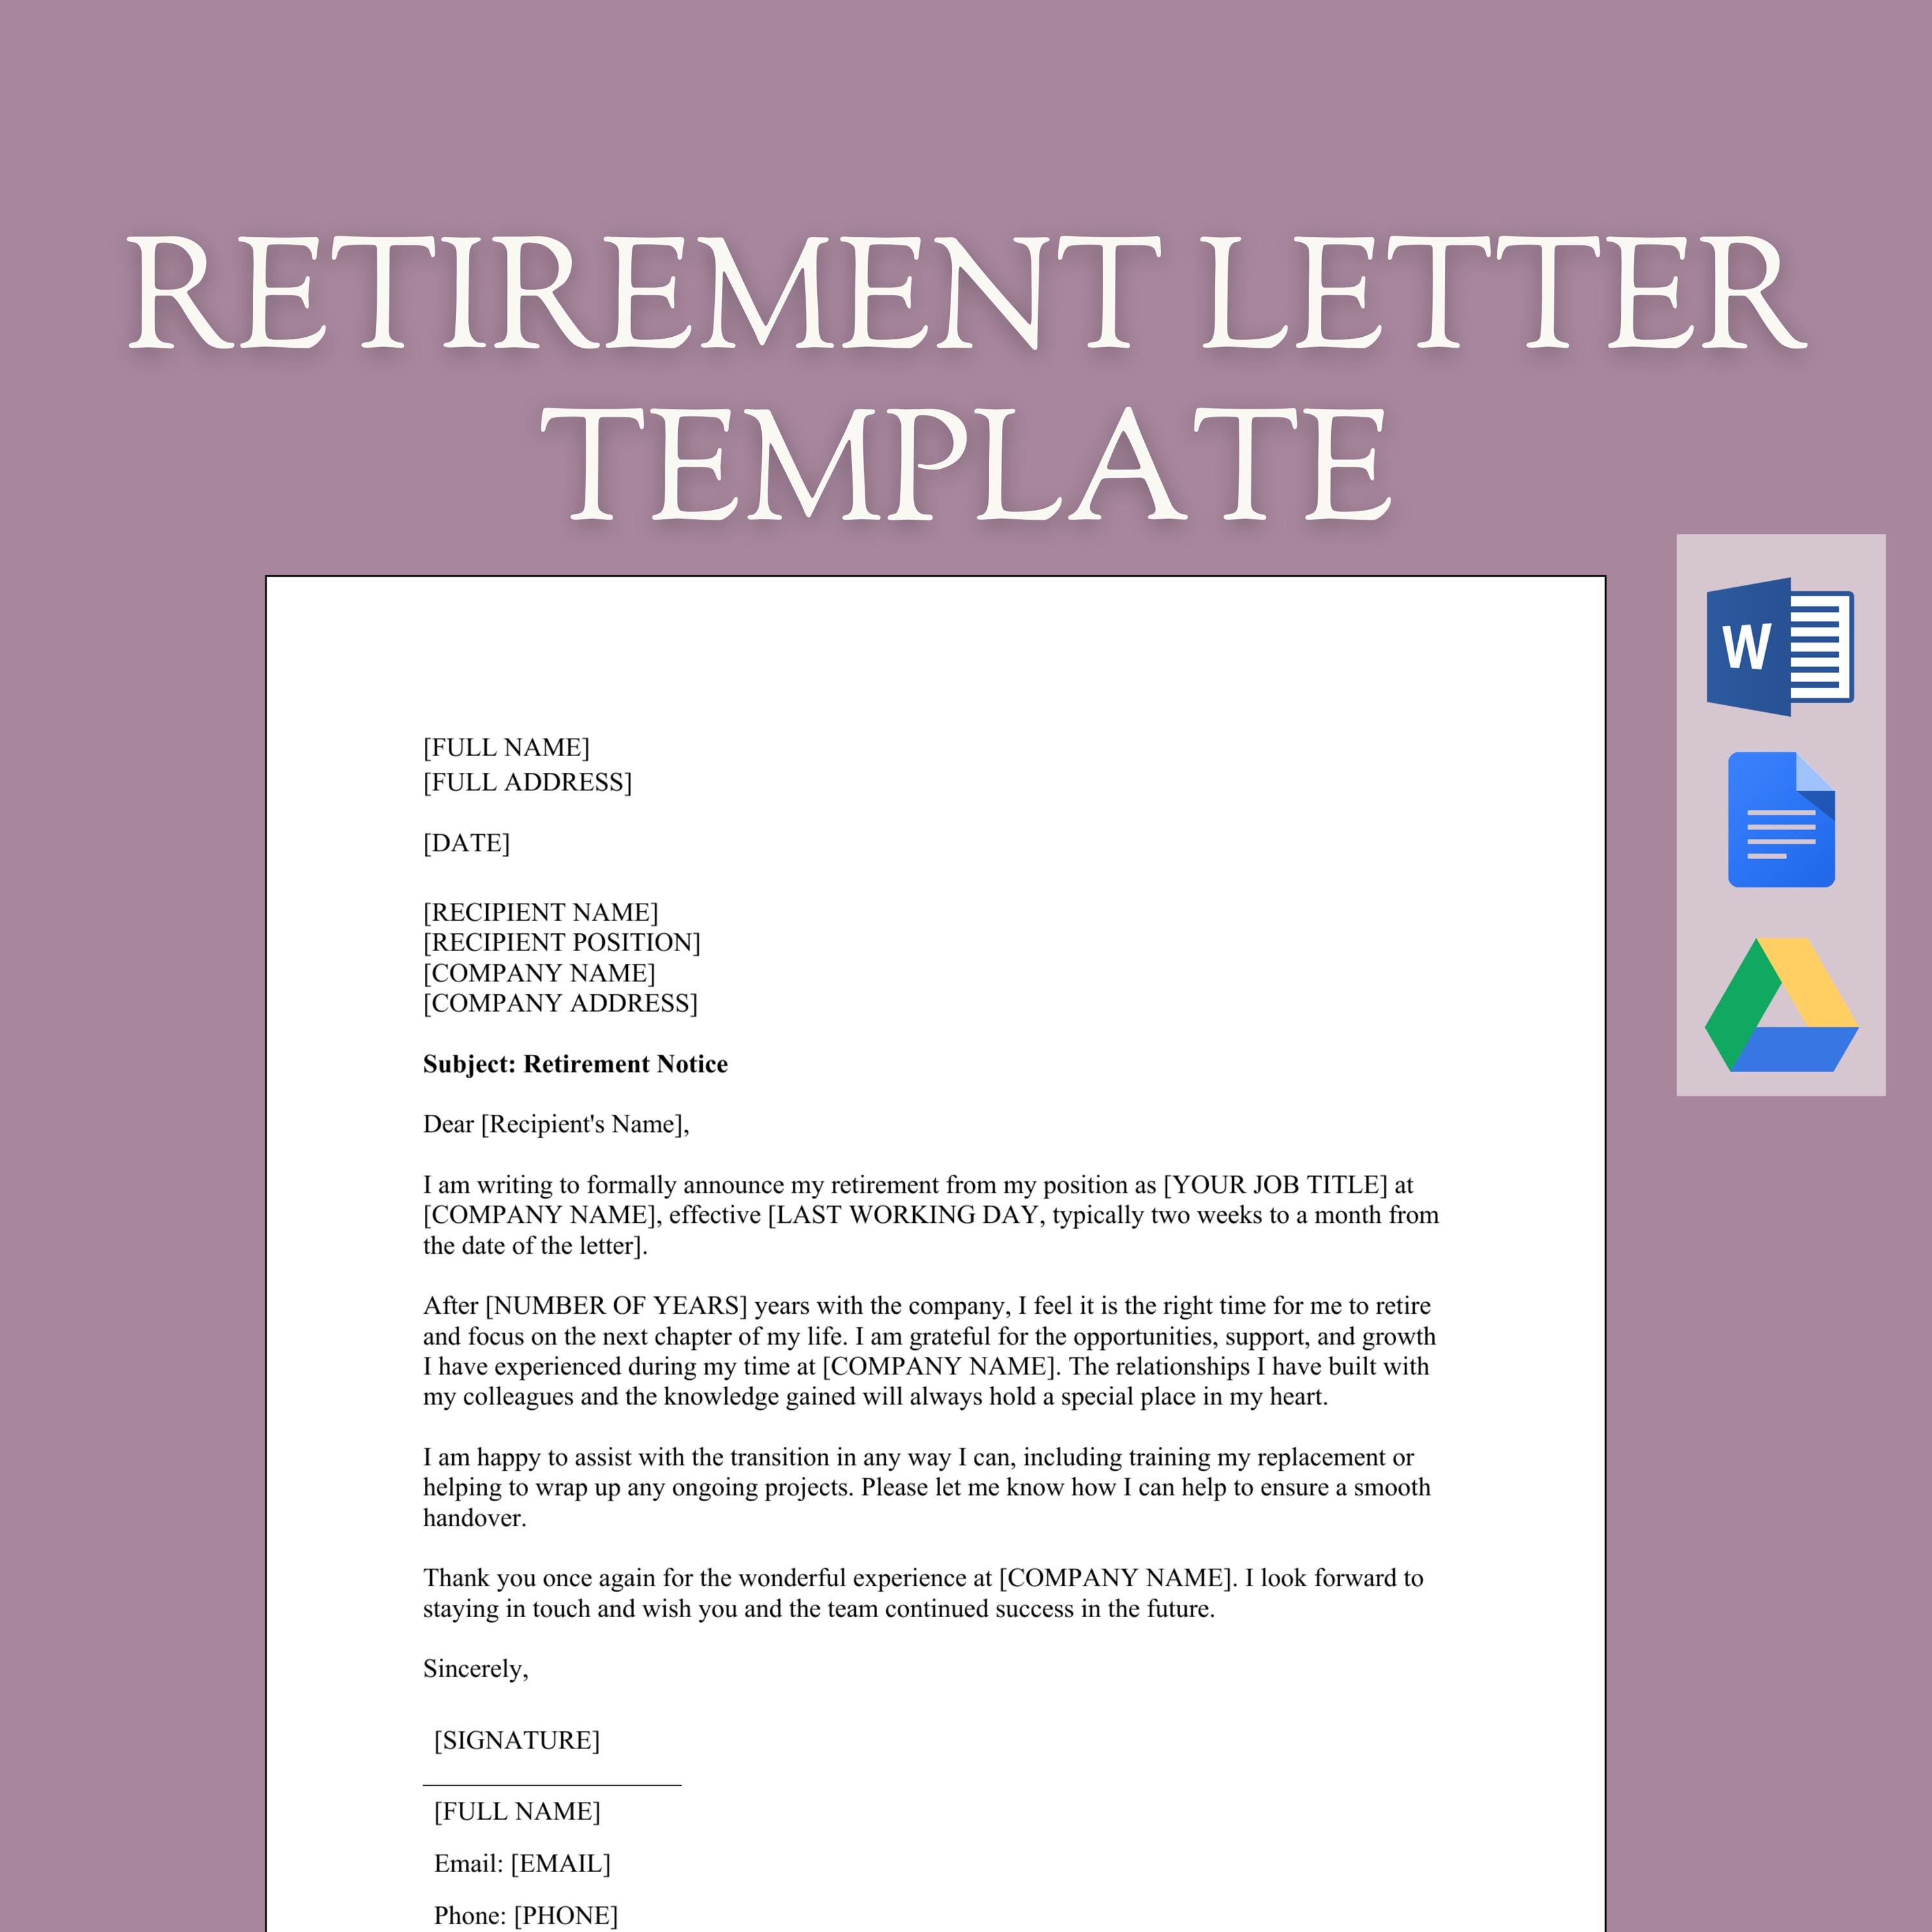
[Your Name] [Employee ID or Badge Number] [Date of Submission]
That's it. Every element above exists for a reason. The employee ID is critical because HR systems match letters to personnel records, and if they can't auto-match, a human has to chase it down. The year in the effective date prevents the exact problem I described earlier. The policy acknowledgement line is defensive writing, but it forces your employer to either confirm compliance or flag an issue immediately rather than discovering it at the back end.
What Happens After You Hit Send
The letter itself is only step one. You'll typically receive an automated acknowledgment within 24 hours. If you don't, follow up in writing. Then watch for three separate things: confirmation from your manager about your final day, confirmation from HR about benefits elections, and confirmation from payroll about your final paycheck composition. These often come from different systems and different people. They don't always align. The most common failure point is the benefits election window. Some companies have a mandatory exit interview or a benefits seminar that you must attend in your final month. Missing it can cost you COBRA discounts or health coverage continuity. The letter should arrive early enough that you can schedule these without crunching everything into your last two weeks.
Counter-Intuitive Things Nobody Tells You
First, a shorter letter is often better. Legal and HR teams prefer concise documents. They're easier to file, easier to audit, and harder to misinterpret. Long letters with gratitude essays create reading fatigue and sometimes get skimmed past important clauses about notice periods or equipment return. Second, the date you put matters more than the date you feel ready to leave. If your pension or stock vesting has a hard cutoff, the letter date determines eligibility. I've seen people hold off writing because they were still unsure about their timing, then submit the letter a week later and miss a quarterly vesting window by four days. Don't wait until you feel completely ready. Submit when you know the date you want. You can adjust later if something changes, but you can't undo a missed deadline. Third, always cc your personal email. Company accounts get deactivated. There's no exception. Once your access goes, you can't retrieve anything, including a copy of the letter you submitted. Keep a copy with the timestamp and the recipient addresses somewhere you'll still have access after you're gone.
When This Approach Fails
The template above works for standard W-2 employees at mid-to-large companies with automated HR systems. It breaks down in a few scenarios. If you work for a small business without dedicated HR, the letter becomes your only paper trail, and the "manager" you write to might forward it to nobody. In that case, send it via certified mail or email with read receipt and keep the proof yourself. If you're in a union position, your collective bargaining agreement likely has specific notice requirements that override a generic letter. Check the CBA first. If you're a contractor or freelance worker, this whole framework doesn't apply — you need a termination of services letter, which is a different document entirely. One more limitation: this approach assumes you have a clear exit date. If you're waiting on pension calculations, disability approvals, or a spouse's visa timeline, the letter locks you into a date. You can submit a letter with a conditional date like "effective on or about June 30th, pending confirmation of [specific event]," but that introduces uncertainty that HR systems don't handle well. Better to pick a firm date and negotiate flexibility separately through your manager or benefits team rather than trying to build conditionality into the letter itself.
The Practical Takeaway
Write the letter. Include the exact date with year. Add your employee ID. Send it with a read receipt or certified delivery. Follow up until you get three confirmations: manager, HR, and payroll. Keep a copy in a personal account. That's the whole process. Everything else is noise.