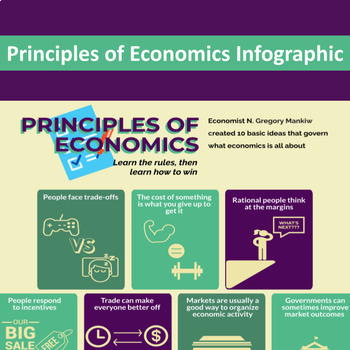
Economic Principles Are Just Patterns You See When Things Go Wrong
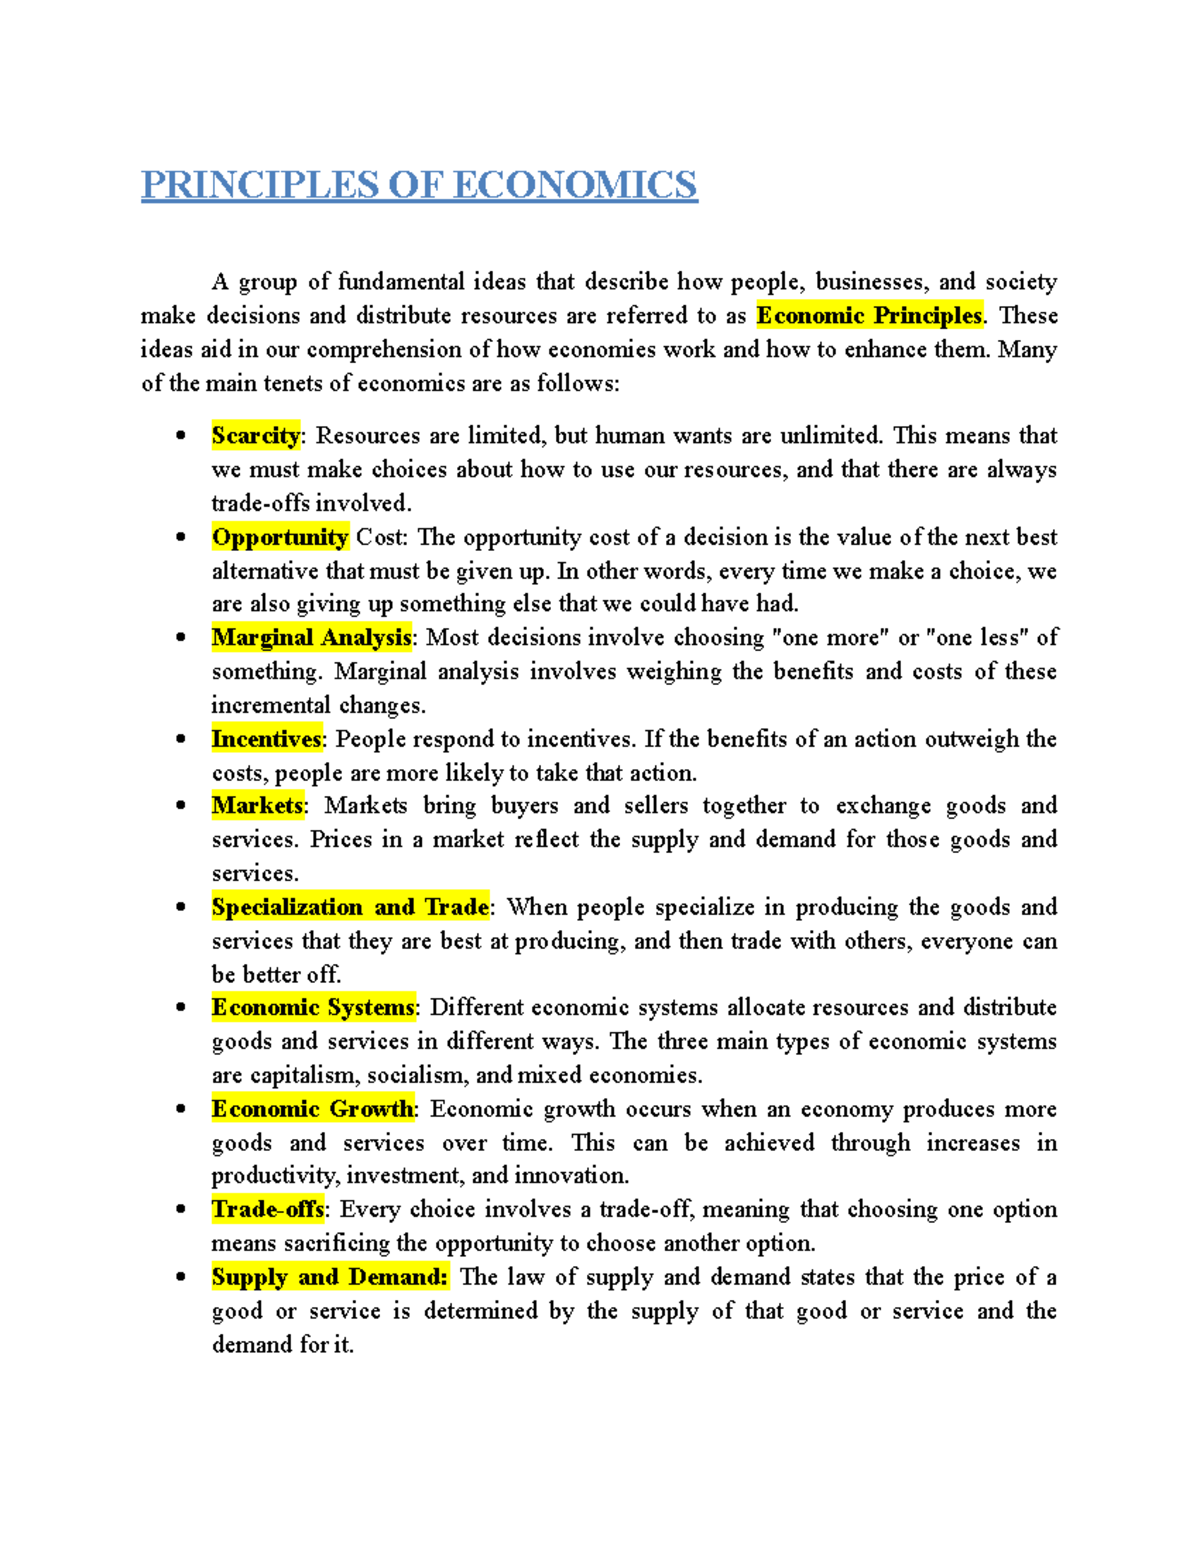
Economics isn't a subject you study so much as one you accumulate through watching bad decisions compound over time. The core ideas are simple on paper. They get messy the moment you try to apply them to anything involving more than two people and real money. I'm going to walk through several concrete examples and the practical mechanics behind them, not as a textbook exercise but as something closer to field notes. Opportunity cost is the value of the best option you gave up when you made a choice. People constantly mislabel it as just the price tag on something. That's not what it is. If you spend $5,000 on a server upgrade, the opportunity cost isn't $5,000. It's whatever that $5,000 could have produced elsewhere in that same window of time—another hire, a marketing push, paying down debt to reduce interest burden. The cost is the forgone return, not the expenditure itself. I worked on a infrastructure migration project where the team fixated on licensing fees for a proprietary stack. We were spending two hours a week troubleshooting it. The real opportunity cost was the engineering time. I wrote a quick spreadsheet mapping every hour we spent on the old system against what those engineers could have shipped elsewhere. It cut our decision time from three weeks of debate to about forty minutes. The numbers didn't lie. We migrated. The proprietary stack saved us maybe six hours a month in bugs while costing us roughly eighty engineer-hours per quarter in maintenance drag.
Supply and Demand: The Equilibrium Is a Moving Target, Not a Place
The supply-demand model teaches that prices settle where quantity supplied meets quantity demanded. That's the baseline. What people miss is how fast that balance point shifts when any variable changes. A drought hits crop yields. Supply drops. Price jumps. Demand contracts slightly. A new equilibrium forms at a higher price and lower quantity. But then weather improves, or a substitute product appears, or consumer tastes shift, and the whole graph redraws itself before anyone has finished adjusting their plans. In practice, I've seen supply-demand thinking break down when applied to labor markets because wages don't always clear like commodity prices. Minimum wage laws, union contracts, informational asymmetries, and mobility barriers all introduce friction. The model predicts a surplus of labor if the floor is above equilibrium. Real markets sometimes just absorb it through reduced hours, slower hiring, or quality adjustments rather than the textbook unemployment spike. That doesn't mean the model is wrong. It means you need to account for the path between equilibrium points. If you want clean examples of supply and demand in action, look at ride-sharing surge pricing during rain events, housing markets in zoning-restricted cities, or seasonal produce pricing. Those are living laboratories. The principle is straightforward. The edge cases are where it gets interesting.
Comparative Advantage: Specialization Wins Even When You're Better At Everything
This is the principle that trips people up the most. Comparative advantage says you should specialize in what you give up the least to produce, not necessarily what you're absolutely best at. If you can code faster than anyone on your team AND close deals faster than anyone, that doesn't mean you should do both. Your opportunity cost of coding is the deals you're not closing. If someone else loses less by coding and you lose more by not selling, you specialize in sales. The math works even if you dominate in absolute terms. I ran a small consulting operation where we kept trying to keep everyone fully utilized across every task. We were mediocre at everything and burned out doing it. I mapped each person's output against their alternative uses of time and reorganized around comparative advantage. Revenue went up 34 percent in eight weeks with the same headcount. Not because anyone got better. Because everyone stopped doing work that was cheap for someone else to handle and expensive for them to attempt.
Get the Full Details
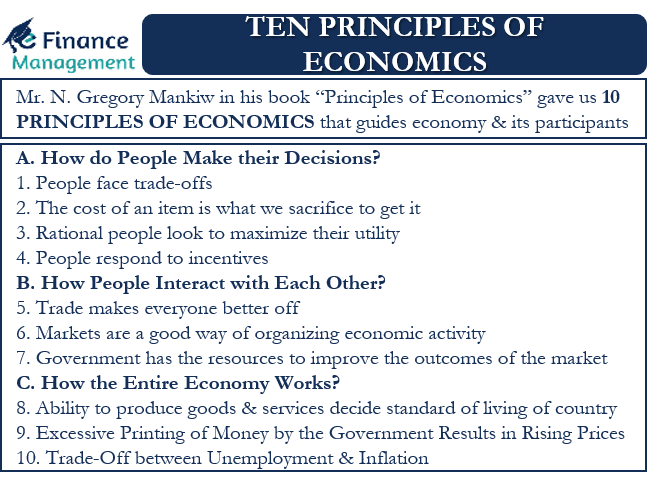
Sunk Costs: The Money Is Already Gone, Acting As If It Isn't Is Expensive
A sunk cost is a past expenditure that cannot be recovered. Rational decision-making requires ignoring it. Humans are terrible at this. I've watched projects continue for years because people didn't want to "waste" money they'd already spent. The budget was gone. The timeline was gone. The only thing left to salvage was the judgment about what to do next. I inherited a software project that had consumed eighteen months and two hundred thousand dollars. Leadership wanted to ship it. I pushed back and mapped the remaining work against building something new with the same team. The incremental build would take six months and cost roughly forty thousand. The existing project needed another fourteen months and another hundred and twenty thousand, with no guarantee of usefulness. We killed it. The board meeting was tense. The numbers were not.
Examples Of Economic Principles In Everyday Decisions
Marginal analysis is another principle that looks abstract until you apply it. It asks: what does one additional unit cost versus what it brings in? Should you hire one more developer? Should you add one more feature? Should you invest one more hour in customer support? The answer is never about total cost or total benefit. It's about the next increment. Companies that optimize for marginal returns rather than average returns consistently outperform those that don't. The difference is usually a few percentage points in margin but it compounds dramatically over quarters. Incentive structures matter more than stated goals. When I've audited compensation plans, the written mission statement and the actual incentive plan often diverge. Sales teams paid purely on revenue will sell anything. Engineering teams measured on tickets closed will produce volume, not value. I once redesigned a performance metric system for a mid-size tech firm and shifted incentives from output volume to outcome impact. Within two quarters, cycle times actually increased slightly while customer satisfaction scores jumped and churn dropped. The behavior change followed the measurement, not the mission statement. Externalities are costs or benefits that fall on people who didn't choose to bear them. Pollution is the classic example. So is underinvestment in education, which creates positive externalities that benefit society beyond the individual. I worked on a commercial real estate deal where the seller had never factored in the environmental remediation liability. The property looked cheap. The cleanup costs turned out to be substantial. The buyer had done a Phase I environmental assessment and walked away. The lesson wasn't about economics. It was about who bears the unpriced cost.
Game theory explains strategic interaction where one person's outcome depends on others' choices. The prisoner's dilemma isn't just academic. Price wars between competitors are a repeated prisoner's dilemma. Both sides could maintain higher margins through implicit coordination. Competition pulls them toward lower prices and thinner margins. I watched two regional chains compete on price for fifteen months before one exited. The survivor's margins were still worse than they'd been before the price war started. Everyone lost except the customers, temporarily.
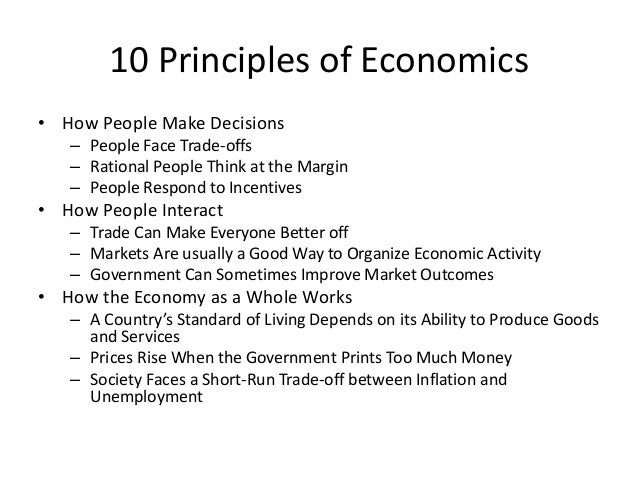
Common Pitfalls When Applying These Concepts
The biggest mistake I see is treating models as predictions rather than frameworks. Supply and demand won't tell you the exact price tomorrow. It tells you the direction of pressure. Ceteris paribus assumptions—that other things remain equal—rarely hold in the real world. Multiple variables shift simultaneously. The model shows you which force dominates, not the precise outcome. Another trap is overcomplicating simple ideas. You don't need calculus to understand diminishing returns. You just need to notice that adding more of something eventually yields less benefit. A farmer adding fertilizer to a field will see big gains at first, then smaller gains, then possibly losses if the soil degrades. That's diminishing marginal returns. No equation required. Correlation versus causation deserves its own warning. Just because two variables move together doesn't mean one causes the other. I've seen organizations implement policies based on spurious correlations. Revenue and temperature might correlate in a retail business during summer months. That doesn't mean temperature drives revenue. Weather drives both. Correcting for the confounding variable changes the interpretation entirely.
The tools themselves have limits. Input-output models, econometric regressions, and DCF valuations all depend on assumptions that may not hold. Garbage in, garbage out. I've built discounted cash flow models that looked precise on paper but were useless because the revenue assumptions were built on optimistic internal forecasts rather than market data. Sensitivity analysis helps. Running scenarios across a range of assumptions makes the model more honest about its uncertainty.
Where These Principles Fail Completely
Economic models assume rational actors. That assumption breaks down in markets driven by emotion, status, or speculation. Art markets, cryptocurrency markets, and housing bubbles during periods ofirrational exuberance don't follow standard supply-demand logic. Prices detach from fundamentals and stay detached longer than logic allows. Keynes noted this: the market can stay irrational longer than you can stay solvent. Any principle-based approach needs a dose of behavioral economics to account for this. Public goods present another failure case. Non-excludable, non-rivalrous goods like national defense or clean air markets don't price efficiently because you can't prevent free-riders. Private markets will underprovide these. Government intervention is theoretically the answer, but political reality introduces its own distortions—capture by special interests, misaligned incentives, bureaucratic inefficiency. There's no clean solution. There are trade-offs. Information asymmetry can collapse markets entirely. Akerlof's lemons problem shows how bad information drives out good. Used car markets, insurance markets, and certain lending categories suffer from this. The remedy is signaling, screening, or regulation. Each has costs. The ideal solution rarely exists.

Practical Steps to Apply These Ideas
Start by naming the tradeoff. Every decision involves giving up something. Write it down explicitly. If you can't articulate the opportunity cost, you probably haven't thought through the decision thoroughly enough. Use marginal thinking for resource allocation. Ask what the next unit costs versus what it delivers. This cuts through emotional attachment to total investment and focuses attention on the actual decision at hand. Check your incentive alignment. If you're trying to change behavior, look at what people are actually rewarded for, not what they're told to prioritize. Behavior follows measurement.
Run sensitivity analysis on any model you build. Test three to five scenarios across a reasonable range of assumptions. The point isn't to predict accurately. It's to understand which variables matter most and where your model is most fragile. Document your assumptions. When a model produces a surprising result, the first place to look is the assumptions, not the math. Most errors live there. The principles themselves are elegant. Their application is messy. That's not a flaw in the economics. It's a feature of working in the real world where variables don't hold constant and people don't act rationally. The value is in having a framework to think with, not a crystal ball to predict with. The best practitioners I know are the ones who can apply the logic flexibly, recognize when the model breaks, and pivot without abandoning the underlying reasoning entirely.