Understanding What You're Actually Paying on an FHA Loan
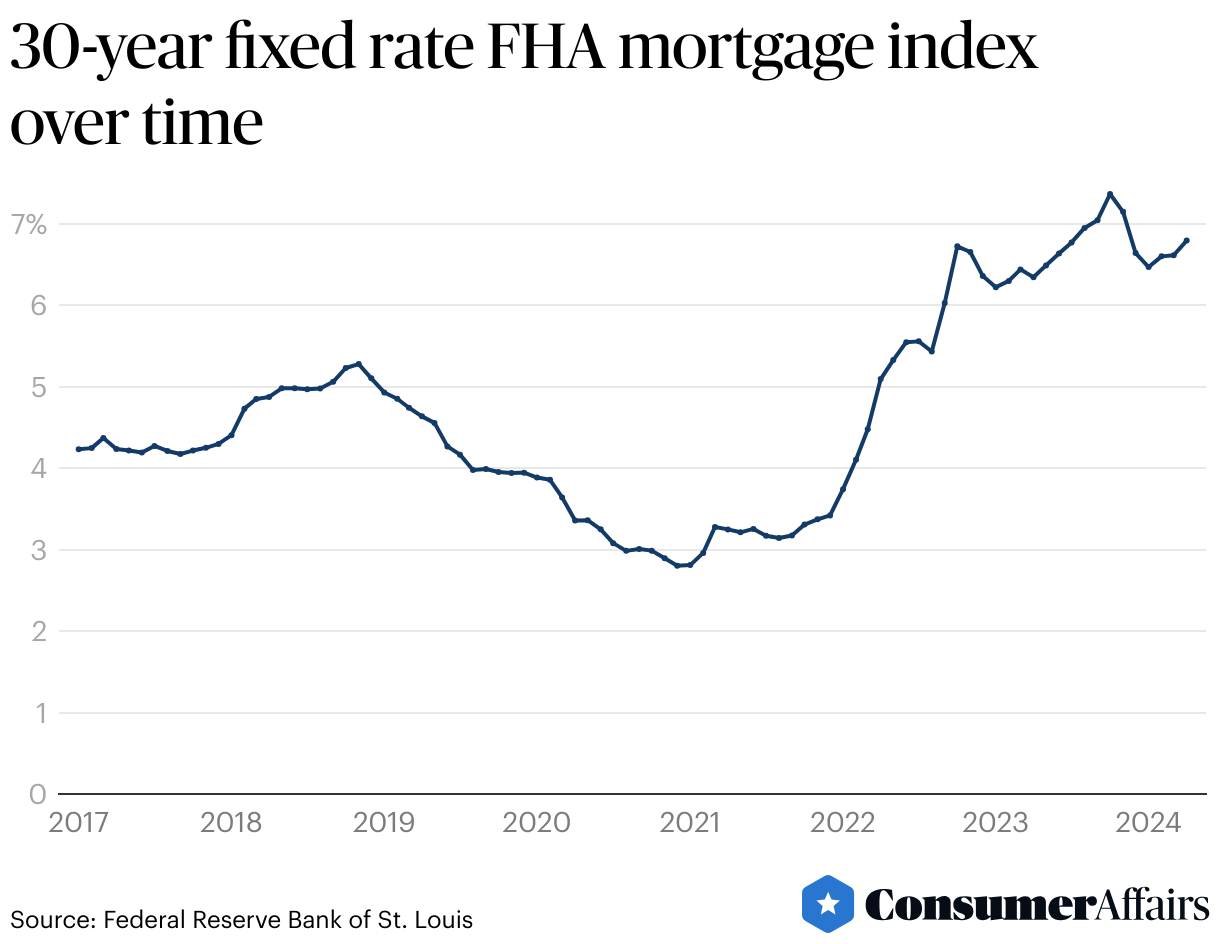
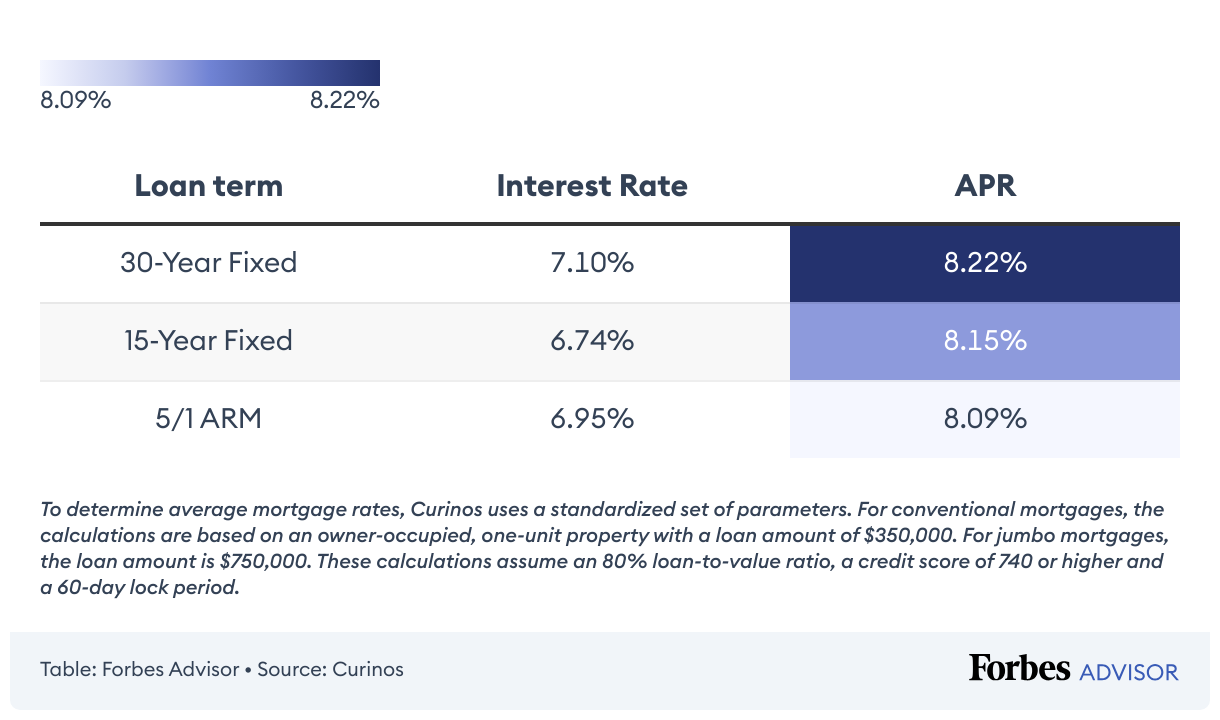
The Fha Loan Interest Rate is just one component of your monthly payment. Most people focus entirely on that single number and miss everything else that inflates the actual cost of the loan. Mortgage insurance, points, lender credits, and the funding fee all interact with the rate in ways that change your total payment dramatically. Here is how it actually works. FHA does not set interest rates. The Federal Housing Administration guarantees a portion of the loan, which reduces lender risk, but the actual rate comes from the secondary market. It moves with the Treasury yield curve and bond market conditions. On any given day, two borrowers with identical credit scores, debt-to-income ratios, and loan amounts will receive different rate quotes from different lenders. This is because each lender prices their own risk tolerance and their own profit margin into the quote. There is no FHA-mandated rate table. The baseline FHA rate you see advertised is typically a par rate, meaning no discount points are paid upfront. If you pay one point, you might drop the rate by 0.25 percent. If you pay two points, maybe 0.50 percent. But those points are usually 1 to 2 percent of the loan amount in upfront cash. The math only works in your favor if you stay in the loan long enough to recoup the point cost through lower monthly payments. On a 30-year FHA loan at $300,000, one point costs $3,000. At a 0.25 percent rate reduction, you save roughly $55 per month. That is a breakeven of over 54 months. If you sell or refinance before then, you lost money buying the point.
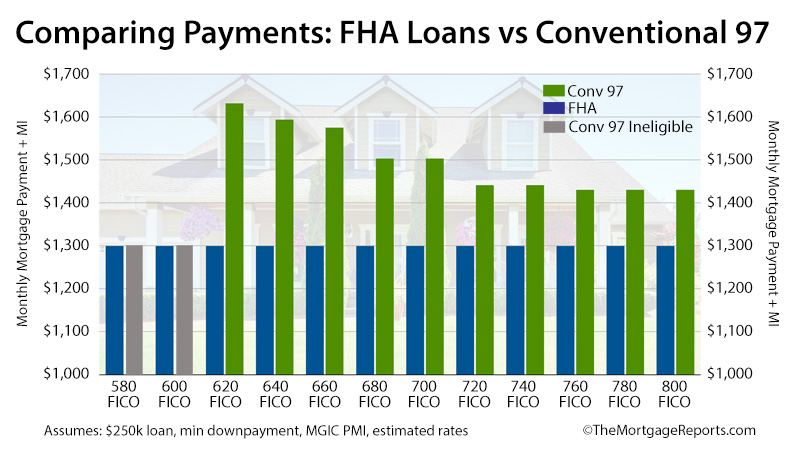
I ran into this exact problem with a borrower last year. He was quoted a par rate of 6.875 percent and another lender offered 6.625 percent with one discount point. On paper, the second option looked better. But when I calculated the break-even, he was planning to move in three years for a job transfer. Paying the point would have cost him about $1,400 in net losses after accounting for the lower monthly payment over just 36 months. I advised him to take the par rate and save the cash. He did. He was still ahead compared to locking the higher point option. Here is something most borrowers do not understand. The FHA mortgage insurance premium interacts directly with your effective rate. The upfront MIP is 1.75 percent of the base loan amount, and it gets rolled into the loan balance. On a $300,000 purchase, that adds $5,250 to your principal. Then there is the annual MIP, which for most FHA loans is 0.55 percent of the original principal, billed monthly. That 0.55 percent is not interest. It is insurance. But it shows up in your monthly payment the same way. When a lender gives you a quote, ask them to separate the interest rate from the MIP charge. Some brokers bundle them into what they call an "effective rate," which sounds lower than it actually is. Another thing people overlook is the credit score threshold. FHA technically allows 580 for the 3.5 percent minimum down payment. But many lenders require 620 or higher just to offer competitive rates. A borrower at 620 might get quoted 6.75 percent while a borrower at 740 with the same loan features gets 6.25 percent. That half-point difference on a $300,000 loan is roughly $200 per month over the life of the loan. The credit score impact on FHA rates is steeper than on conventional loans because FHA lenders see lower-score borrowers as higher risk despite the government guarantee. They price accordingly.
Reading the Loan Estimate Correctly
When you get a Loan Estimate from a lender, page one shows the interest rate, the monthly principal and interest, and the estimated total monthly payment. Page two breaks down the closing costs. Look specifically at the origination charges and the mortgage insurance line. The origination fee for FHA loans is capped by HUD at 1 percent of the loan amount. If a lender charges more, that is a red flag. The MIP lines should show both the upfront premium and the annual premium separated out. Some lenders offer lender credits that buy down the rate. This means they give you money at closing to reduce your interest rate. It sounds good until you realize the credit is offset by higher fees elsewhere on the Loan Estimate. A lender might give you a 0.5 percent rate buydown but charge $4,000 in application fees or higher title insurance. The net effect is neutral or worse. Always compare the total closing costs alongside the rate, not the rate in isolation. The APR on a Loan Estimate is supposed to reflect the true cost of the loan including points, fees, and mortgage insurance. But it has limitations. For FHA loans, the APR calculation includes the upfront MIP but not the ongoing annual MIP if it is paid monthly. So the APR might show 6.95 percent while your actual all-in cost including monthly insurance is closer to 7.2 percent. Do not treat the APR as the final word. Use it as a comparison tool between two otherwise similar loans from the same type of lender.
Get the Full Details
I had a borrower once who was quoted an APR of 6.80 percent from a big national lender and 7.05 percent from a local credit union. The national lender looked cheaper. But when I traced through the numbers, the national lender was charging higher appraisal and processing fees that inflated their APR artificially. The credit union had a simpler fee structure. Over five years, the credit union's loan ended up costing about $1,800 less in total. The APR comparison was misleading because the fee structures were so different. This happens more often than you would think. Big lenders load fees onto products where borrowers rarely look closely enough to notice.
When FHA Rates Are Not the Right Move
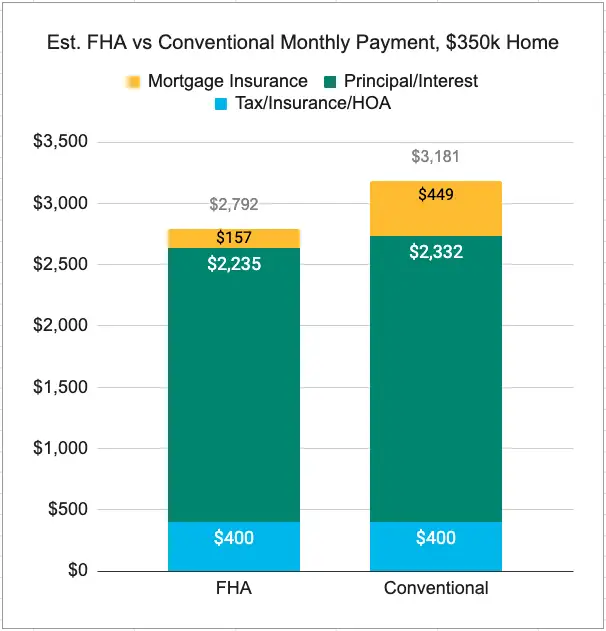
FHA loans are not universally advantageous. If you have a credit score above 720 and can put down at least 10 percent, a conventional loan with private mortgage insurance will likely cost you less over the life of the loan. Conventional PMI drops off automatically once you reach 20 percent equity. FHA annual MIP stays for the life of the loan if your amortization term is 11 years or longer, which covers most standard 30-year FHA loans. That means you are paying mortgage insurance for 30 years regardless of how much equity you build. On a $300,000 loan, that is roughly $137 per month in annual MIP for three decades, or about $49,000 total in insurance premiums that never go away. If you are using an FHA loan primarily because of a lower down payment requirement and your credit is already solid, run the numbers on a conventional loan side by side. The difference in total cost can be substantial. I once had a client with a 710 credit score who was convinced she needed an FHA loan because she could only put 5 percent down. She was wrong. A conventional loan at 5 percent down with PMI cost her $89 per month in PMI versus $137 per month in FHA MIP. Plus she would eventually drop the PMI. She saved roughly $48 per month and thousands over the loan term by going conventional. The timing of when you lock your rate matters more than most people realize. FHA rates follow the same bond market patterns as conventional rates. If the Federal Reserve signals a pause in rate hikes, FHA rates often drop within a week. If inflation data comes in hotter than expected, rates jump. A rate lock typically costs between 0.25 and 0.50 percent of the loan amount in points. A 60-day lock is standard. Extending it costs more. If your closing date is uncertain, consider a float-down option, which allows you to take a lower rate if the market improves before closing, usually for a small additional fee. This is useful in volatile rate environments.
One final detail that nobody talks about. The FHA funding fee can sometimes be negotiated around. While the 1.75 percent upfront MIP is fixed by the government, some lenders will absorb a portion of it as a concession on jumbo-sized FHA loans or for repeat FHA borrowers. This is not common, but it happens. Asking about it costs nothing and might save you a few thousand dollars. I always mention it to borrowers who have previously owned and sold an FHA loan successfully. They do not need to know they have that leverage until they are in the negotiation phase.