How to Actually Use an Fha Mortgage Qualification Calculator
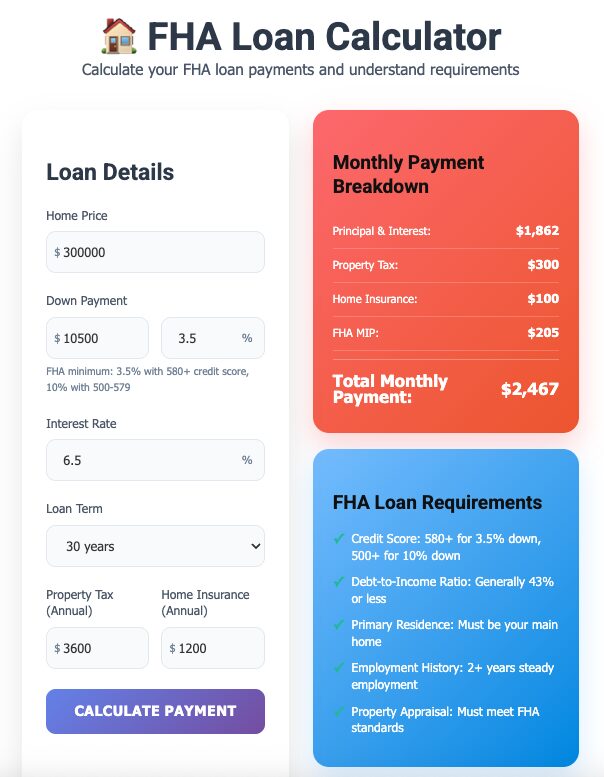
The biggest problem I see with these tools is that most people treat them like a yes-or-no box. They plug in their numbers, get a result, and either celebrate or panic. An Fha Mortgage Qualification Calculator is more useful when you think of it as a way to reverse-engineer your situation. You're not just checking if you qualify. You're figuring out what you need to change so you do. FHA loans are backed by the Federal Housing Administration, which means they come with lower down payment requirements and more forgiving credit standards than conventional loans. The standard minimum is 580 for the 3.5 percent down payment tier, but lenders can go lower with additional overlays. That's the first thing to understand: the FHA sets guidelines, but individual lenders set their own floors. The calculator pulls in your income, debts, credit score, the property price, and your down payment. From there it runs two ratios. The front-end ratio, which is your housing expenses divided by gross monthly income. The back-end ratio, which includes everything else. FHA typically requires a combined ratio up to around 43 percent, though some approved lenders will stretch to 50 or 56 percent depending on the rest of your profile.
I've seen people hit a wall with their calculator results and immediately conclude they don't qualify. What they're usually missing is that the tool doesn't know about compensating factors. Strong reserves, a letter of explanation for a past credit issue, or a co-borrower with solid income can all shift the outcome in your favor. These don't always show up in basic online calculators.
Running the Numbers
Start by gathering the actual documents, not the estimates. Lenders will verify everything anyway, so there's no point in feeding the calculator guesswork. Pull your most recent pay stubs, W-2s from the last two years, tax returns if you're self-employed, and your credit report. Check your credit report yourself before running the numbers. Disputing errors takes time, and you need to know your real score before you trust any calculator output. Input your gross monthly income. If you're salaried, that's straightforward. If you're hourly or commission-based, lenders average your income over the past two years. That can bring your calculated number down significantly compared to what you think you make right now. Include all income sources that will appear on the application: spousal income, alimony, disability, social security, rental income if you have a tenant. For debts, include everything. Car payments, student loans, credit cards, personal loans, child support, alimony. Even if you pay off a card, the minimum required payment goes into the calculation. A lot of people forget the minimums on their utility bills don't count, but the line on the credit card absolutely does.
Get the Full Details
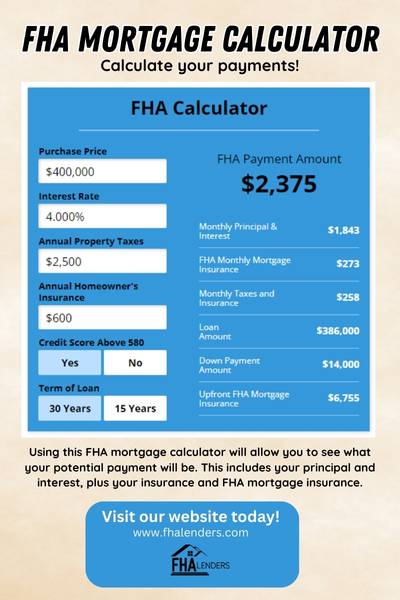
The property price and down payment are where things get specific to FHA. You need to account for mortgage insurance premiums. There's an upfront MIP of 1.75 percent of the base loan amount, which typically gets rolled into the loan balance. Then there's the annual MIP, split into monthly payments, which lasts the life of the loan on most FHA terms unless you put down 10 percent or more. That 10 percent threshold matters because the MIP drops off after eleven years with a smaller down payment, but it's gone immediately with 10 percent down. Calculators often miss this distinction, so verify what the tool is showing you.
A Specific Problem I Ran Into
A borrower came to me with a credit score of 590, which put him right at the edge of the 580 minimum that many lenders claim to accept. The calculator showed he barely qualified, but when I actually pulled the numbers, there was a complication. He had a collection account from three years ago that hadn't been resolved. Most FHA-approved lenders require that all Collections and Charge-offs be satisfied before closing, and the calculator tool didn't account for that requirement. The workaround was finding a lender willing to allow the collection to remain unpaid if it was older than two years and under a certain dollar threshold. Not all of them will do this, and it's not written into the FHA handbook explicitly. It's a lender-level overlay decision. I found one community bank that did it, and the borrower closed with a score of 590 and that collection still on his report. The calculator gave him a false sense of what was actually going to happen. If you're working near the margins, don't trust the tool alone. Call a lender directly and ask about their specific stance on collections and charge-offs before you get your hopes up.
Counter-Intuitive Things People Miss
One thing that catches people off guard: FHA allows gifts for the down payment. Any source, really, as long as it's properly documented with a gift letter. This matters because the calculator assumes you're using your own money, but if you're working with the FHA maximum loan limits for your county, a gift of even $5,000 can change whether you qualify at all. Run the calculator twice, once with the gift and once without, and compare the results. Another thing: FHA has strict debt-to-income limits, but the way income is calculated can work in your favor. If you have a part-time job in addition to your main employment, that income counts toward qualification. Two jobs, sometimes called dual income, can dramatically improve your ratios. I've had borrowers go from disqualified to approved simply by adding their spouse's part-time income to the application, something most basic calculators don't account for well.
Where the Calculator Falls Short
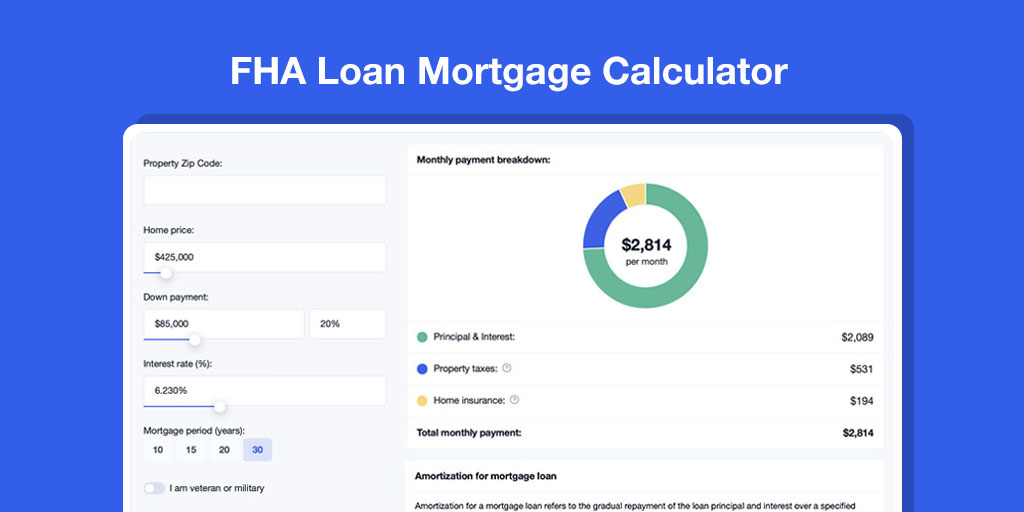
Here's the honest part. An Fha Mortgage Qualification Calculator can tell you roughly whether you meet the baseline requirements, but it cannot predict whether a specific lender will approve your application. Lender overlays vary widely. Some won't touch credit scores below 600. Others ignore the 580 minimum entirely and use 560. Some require two years of consistent employment history, while others accept less. None of that shows up in the calculator. It also doesn't tell you about the property itself. FHA has minimum property requirements. If the house you're buying needs a new roof, has foundation issues, or doesn't meet safety standards, the loan can't close until those items are fixed. The calculator doesn't know anything about the property condition. That's a separate inspection process entirely. Another limitation: these tools rarely factor in VA funding fees, USDA loan specifics, or state-specific assistance programs that could change your numbers. If you're looking at a VA loan instead, the qualification process is different enough that an FHA calculator gives you misleading information. Same for USDA, which has income limits based on your county and household size.
If you're serious about applying, use the calculator as a starting point, then get pre-approved with a lender who actually underwrites FHA loans. Pre-approval in this context means they've pulled your credit, verified your income and assets, and given you a conditional commitment. That process takes about one to three business days. It's the only way to know your real status, because the calculator is doing its best with incomplete data and blind spots.
Using the Fha Mortgage Qualification Calculator Effectively
Treat the output as a directional signal, not a verdict. If it says you qualify, call three lenders and ask for their specific underwriting guidelines. If it says you don't, look at which variable is pulling you under, adjust that one variable, and recalculate. Changing your down payment by a few thousand dollars or paying down a single credit card can shift you from rejected to approved. Run the numbers again with the new inputs and see the difference. The calculator is a tool, not a gatekeeper. The real gatekeeper is the underwriter. Know the difference and you'll save yourself a lot of frustration.