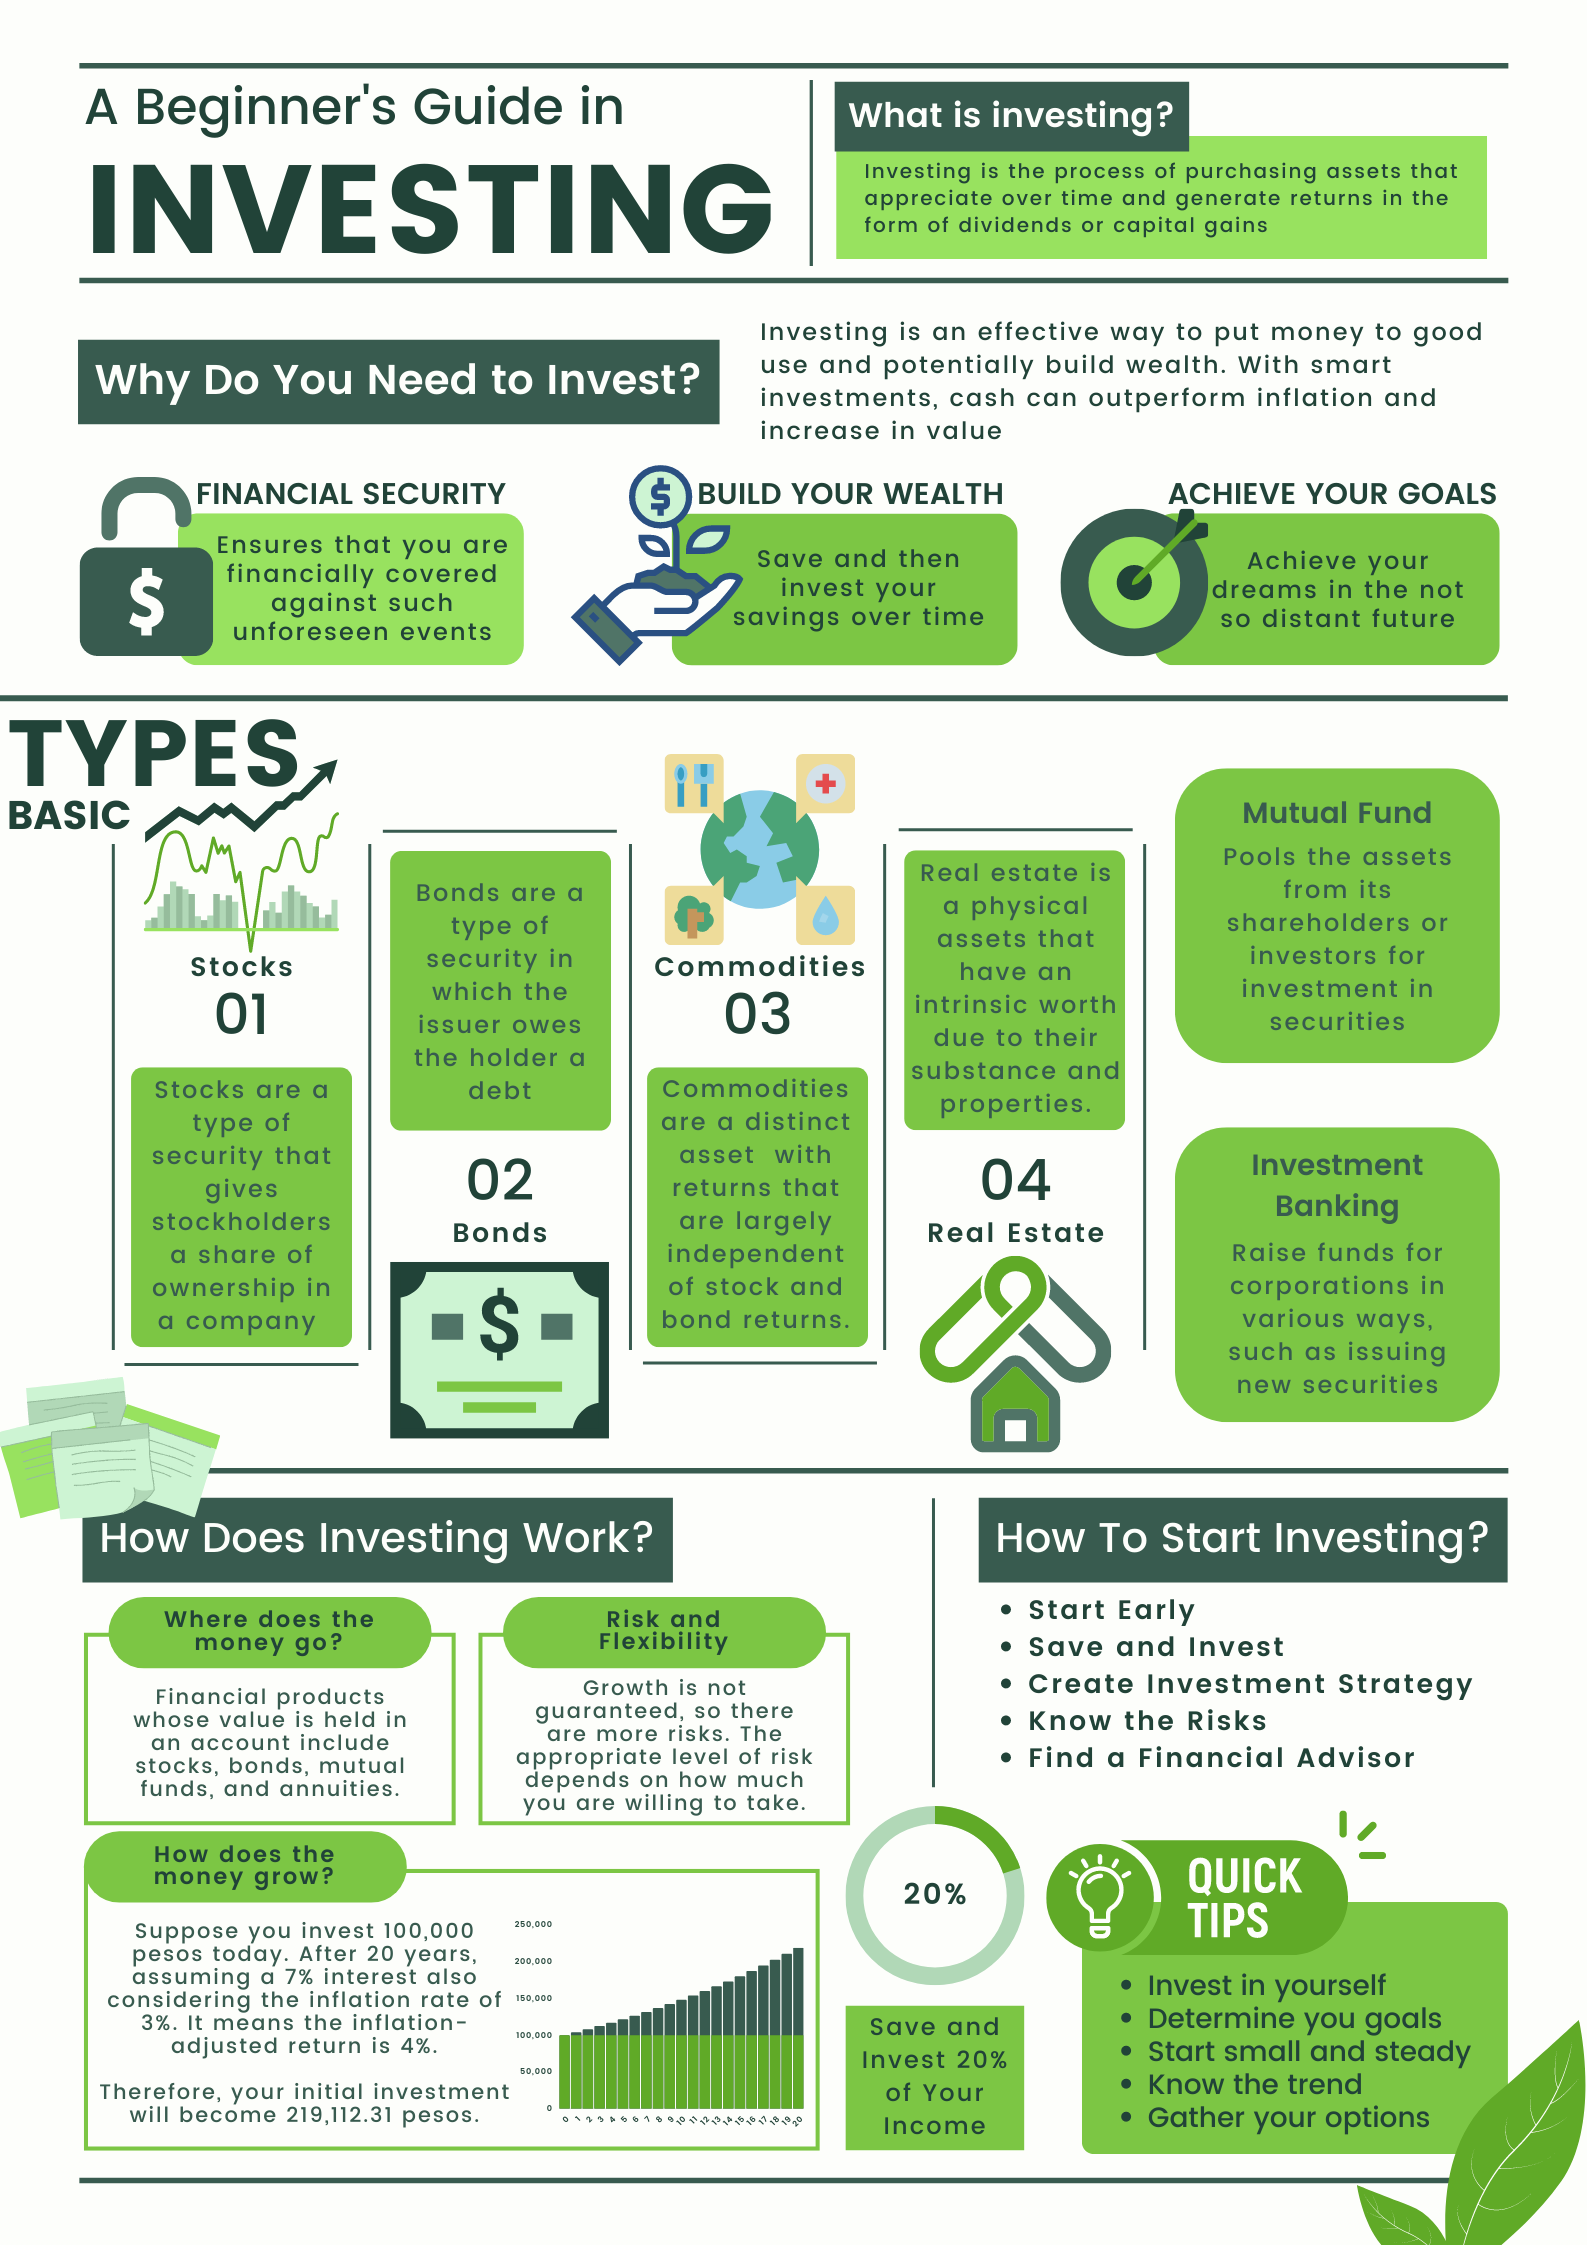
Investing isn't a puzzle you solve with the right infographic
I spent eight years tracking my own portfolio returns against benchmarks, and the only thing that actually moved the needle was not what most people think it was. The charts online make it look like there is a secret set of indicators or a timing trick that separates the people who win from the people who lose. It doesn't work that way. What works is building a system that removes emotion from the equation and then having the discipline to let it run for a decade without checking it.
The real Field Guide For Investing Tips And Tricks is a collection of habits, not strategies. Most of the people who try to find a shortcut end up overtrading, which compounds into fees and taxes that destroy compounding before it ever gets a chance to work. I watch this happen all the time in the forums where people post their daily trades like they are playing a video game. Markets are not a game. They are a slow grind of decisions that add up, and the winners are the ones who do the least harmful things most consistently.
What the Field Guide For Investing Tips And Tricks Actually Covers
It covers three things: asset allocation, tax efficiency, and behavioral control. That is it. People want fourteen bullet points and a checklist they can screenshot. I give them those three. If you nail asset allocation, the other two mostly take care of themselves. If you ignore asset allocation, no amount of tax hacking or mindset coaching will save you from underperformance.
Asset allocation is the percentage of your portfolio that sits in different asset classes. Stocks, bonds, real estate, commodities. The mix determines your risk profile more than anything else. A common mistake I see is people picking individual stocks because they read about a company online, without adjusting the broader allocation. You can be right about a stock and still lose money because your overall portfolio is overconcentrated in one sector. That happened to me in 2021 when I had too much tech exposure and watched a twenty percent drawdown that took fourteen months to recover from. I learned to rebalance annually, selling the winners and buying the losers, which feels wrong emotionally but keeps your risk level stable.
Tax efficiency is the second pillar. Most investors ignore it until tax season, and by then the damage is done. The difference between a taxable account and a tax-advantaged account like an IRA or 401k is not subtle. Over thirty years, the tax drag on a taxable account can reduce your final return by two to four percent annually, depending on your turnover rate. I switched most of my trading to Roth accounts about five years ago, and the tax-free growth has already added thousands compared to where I would be with a standard brokerage account. The exact number depends on your bracket, but the math is straightforward.
Behavioral control is the hardest part, and the one most people skip. You will want to sell when the market drops. You will want to buy when everything is going up. That is human nature, and it is also the exact opposite of what makes money. I keep a written rule sheet that says I never trade more than twice a month outside of rebalancing windows. That rule has saved me from myself multiple times. When the market crashed in early 2022, I felt the urge to move everything to cash. I did not. I followed the rule, kept dollar-cost averaging into index funds, and came out ahead.
The mechanics of a working system
A practical setup looks like this: sixty percent total stock market index fund, twenty percent bond index fund, ten percent international developed markets, ten percent real estate or commodities through REITs or commodity ETFs. Rebalance once a year in January. Put new money into the underweighted categories automatically. Use tax-advantaged accounts first, then taxable. That is the baseline. You can adjust the percentages based on your age and risk tolerance, but the structure stays the same.
The rebalancing part is where people get stuck. You do not need to sell everything and start over. You just need to sell the assets that have grown above their target percentage and buy the ones below. A simple spreadsheet with your target allocations and current values will show you exactly what to do in three minutes. I use a free tool called Portfolio Visualizer to backtest different allocations, and it takes about twenty minutes to set up. The results usually confirm what the math already says: a balanced portfolio with annual rebalancing outperforms most individual stock picks over fifteen year periods after costs are included.
One edge case that trips people up is the wash sale rule in the United States. If you sell a security at a loss and buy the same or substantially identical security within thirty days, the loss is disallowed for tax purposes. I learned this the hard way in 2019 when I tried to harvest losses on an ETF I had owned for three years and accidentally triggered a wash sale by repurchasing it a week later. The IRS notice came two months after filing, and I owed additional taxes plus a small penalty. Now I keep a calendar reminder thirty days before any planned sale, and I never repurchase the same fund within the wash sale window. It is a minor hassle that prevents a major headache.
Another practical detail is the difference between expense ratios and actual costs. An expense ratio of zero point zero five percent sounds tiny, but on a hundred thousand dollar portfolio it adds up to fifty dollars a year. Over thirty years at seven percent returns, that fifty dollars a year becomes roughly three thousand dollars in foregone compounding. I switched from a fund with a zero point five percent expense ratio to one with zero point zero three percent, and the difference was about eight hundred dollars annually on my balance. It does not sound like much until you multiply it across multiple accounts and decades.
Where this approach breaks down
The balanced index fund method does not work if you have a high income that pushes you into backdoor Roth territory, or if you are trying to time market entries based on economic indicators. No one can reliably predict recessions or peaks, and anyone who claims otherwise is selling something. I stopped following macro forecasts around 2016 after realizing that every prediction I had acted on turned out wrong within six months. The data is noisy, the models are flawed, and the media amplifies both.
Another limitation is that this approach requires a long time horizon. If you need the money within five years, equities are too volatile to be safe. I keep my emergency fund in a high yield savings account, not in the market, because I learned that lesson when I had to withdraw from a brokerage account during a downturn in 2020 and locked in losses. The rule is simple: only invest money you will not need for at least seven years. If you cannot follow that rule, keep your investments in short term bonds or CDs instead.
Dollar cost averaging also has a downside. You will always buy at higher prices than if you had timed the market perfectly, but you will also buy at lower prices than if you had stayed in cash. The average is somewhere in the middle, and over long periods that middle tends to be where the money is made. I tried lump sum investing once and regretted it when the market dropped ten percent two weeks later. I went back to monthly contributions and stopped second guessing the timing.
Final notes from someone who has watched this work and fail
The Field Guide For Investing Tips And Tricks is not exciting. It does not involve charts, indicators, or secret knowledge. It involves reading a book, setting up automatic contributions, rebalancing once a year, and ignoring the news. I have seen people lose money chasing trends and win by doing nothing at all. The latter is harder because it feels like you are missing out, but it is also the only strategy that has consistent empirical support across every market cycle I have lived through.
If you want to dig deeper, the Bogleheads forum is the best free resource available, and the three fund portfolio is a well tested starting point. Do not pay a financial advisor to tell you to buy index funds. Do not buy courses on market timing. Do not follow influencers who post daily trade ideas. The best investment decision you will make is the one that keeps you from making a bad one. I still make mistakes, but they are smaller now because the system absorbs the emotion before it reaches my hands.
Gallery Field Guide For Investing Tips And Tricks
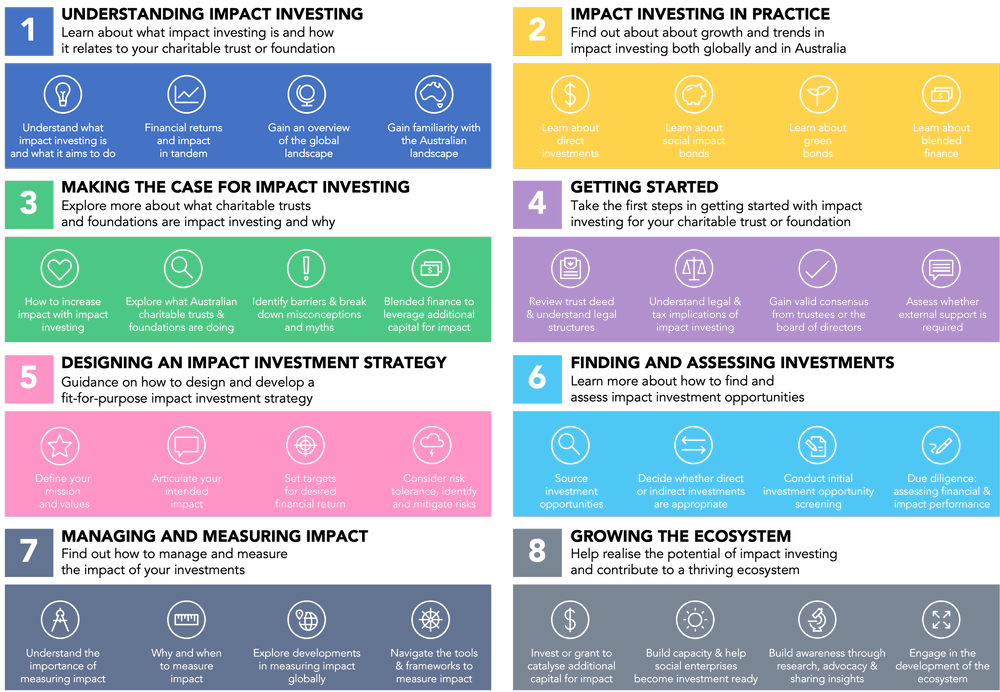
Impact Investing Field Guide — Impact Investing Hub
Investing Guide For Beginners. 100% Practical Tips to Start - CONTENTCLAP
Basic Guide: Investing Tips for Beginners | Deposit Talk
How to Start Investing: The Ultimate Beginner's Guide (2023 ...
A Beginner’s Guide in Investing 2022 | Diary Ni Gracia