Why Most Finance Checklists Fail Before They Start
I spent three years building what I thought was the definitive Finance Checklist Top 10 for a mid-market CFO's office. The first version took 47 items down to exactly ten by cutting everything subjective. What remained was a list that looked clean on paper and fell apart the first time someone actually tried to use it. The problem wasn't the content. It was the order.
Here is what actually works when you sit down to build a practical checklist for personal or business finance management.
The Finance Checklist Top 10 That Actually Holds Up
1. Map your cash flow before you allocate it. People skip this. They go straight to budgeting categories, which is backward. Cash flow tells you how much money actually moves through the account in a given period. Budgeting tells you where it should go. If your inflows and outflows don't align on paper, every subsequent category is just a guess. I once had a client whose business appeared profitable at $82,000 a month until I pulled their bank statements for the actual timing of deposits. Their biggest client paid net-60. The cash was there, just not when they needed it. That changed the entire shape of the checklist.
2. Define what "enough" means for each category. A budget line item without a ceiling is just a suggestion. "Spend less on marketing" is useless. "Marketing stays under $4,200 this quarter" is actionable. The second one forces a decision when the decision actually matters.
3. Separate fixed obligations from discretionary spending. This is the most overlooked step. Rent, loan payments, insurance premiums, subscription services that auto-renew — those are fixed. Dining, entertainment, ad-hoc purchases, impulse buys — those are discretionary. When you merge them into one big bucket, you lose visibility into what can actually be cut. I learned this the hard way during a cash crunch at my old firm. We thought we had $12,000 in breathing room. We didn't. $9,400 of it was tied up in fixed commitments I hadn't properly separated out. Fixing the spreadsheet took about 45 minutes and eliminated that particular panic.
4. Build in a buffer that isn't an afterthought. Most people add a 5% cushion at the end like an apology. That doesn't work. A proper buffer is 10–15% of total monthly outflows, sitting in a separate account, untouched unless something unexpected happens. Not for "nice to have" purchases. Actual emergencies.
5. Track debt in two dimensions: rate and payoff date. Listing debts alphabetically or by balance tells you nothing useful. Group them by interest rate descending first. Then map the payoff schedule against your cash flow. The debt with the highest APR is not always the one that should be destroyed first if it has a prepayment penalty or a balloon payment coming due. That's an edge case most checklists ignore.
6. Do a quarterly reconciliation, not an annual one. Annual reviews are where small errors compound into structural problems. I've seen discrepancies of $3,000 to $8,000 creep into business accounts over 12 months because nobody was comparing the ledger against the actual bank statement. Doing it every quarter keeps those numbers under $200 and usually resolves to zero within an afternoon.
7. Automate the mechanical stuff. Keep the judgment calls manual. Bill payments, transfers to savings, investment contributions — automate those. Categories, allocations, spending limits — those require human judgment. If you automate the judgment calls, you'll automate yourself into paying for things you shouldn't.
8. Document the decisions, not just the numbers. A checklist entry that says "reduced travel budget by 20%" is incomplete. Write down why. "Reduced travel budget because Q3 revenue missed target by 8% and we're preserving cash for payroll." Three months later, when you need to justify either reversing or maintaining that decision, you won't have to guess.
9. Review one item per week, not the whole list at once. Going through a ten-item finance checklist all at once takes about 90 minutes and most people quit after item four. Split it. One item per week. Fifteen minutes. You stay consistent because the effort is small.
10. Prune items that stop being relevant after 90 days. Checklists rot. A line item about "Q1 tax estimated payments" loses meaning in April. A reminder about "back-to-school supply budget" is noise in September. Mark items as completed and archive them. Don't let dead categories clutter the active list. It creates false signals about your financial discipline.
Where This Approach Breaks Down
This framework assumes you have at least basic access to your financial data. If you're working with cash-only transactions, paper receipts only, or a business that doesn't keep regular bank records, the cash flow mapping step (item one) becomes significantly harder and may require hiring someone to reconstruct the records first. The quarterly reconciliation step also falls apart if you're not the one handling the books — which is common in small family-run operations where one person controls everything.
There is no version of this that replaces professional advice for complex situations like business acquisitions, estate planning, or multi-entity structures. The checklist is a maintenance tool, not a diagnostic one.
A Practical Example
Let me walk through a real scenario. A consulting firm with three employees, roughly $140,000 in monthly revenue, irregular payment cycles from clients. The first pass through the checklist took us about three hours. We mapped cash flow and discovered the revenue was lumpy — six months above average, six months below. That meant the budget categories had to be structured around the low months, not the average. Every category was set at the lower bound. The surplus during high months went straight to the buffer account defined in item four.
The second pass, done one week later to catch omissions, took forty minutes. We found two auto-renewing subscriptions we'd forgotten about ($340/year combined) and misclassified one vendor payment as a one-time expense when it was actually monthly. Those two fixes alone changed the monthly surplus by $1,280.
How to Get Started
Print the ten items. Write them on index cards. Pick one. Work through it for the current month. Come back next week for the next. Do not attempt to implement all ten simultaneously. The cognitive load will cause you to skip the documentation step (item eight), and without documentation, the checklist loses its utility within two months.
There is no downloadable template I recommend. The act of writing the list out yourself is where the actual understanding happens. A pre-made PDF is just decoration at that point. What matters is that you've forced yourself to confront each item and decide what it means for your specific situation.
Gallery Finance Checklist Top 10
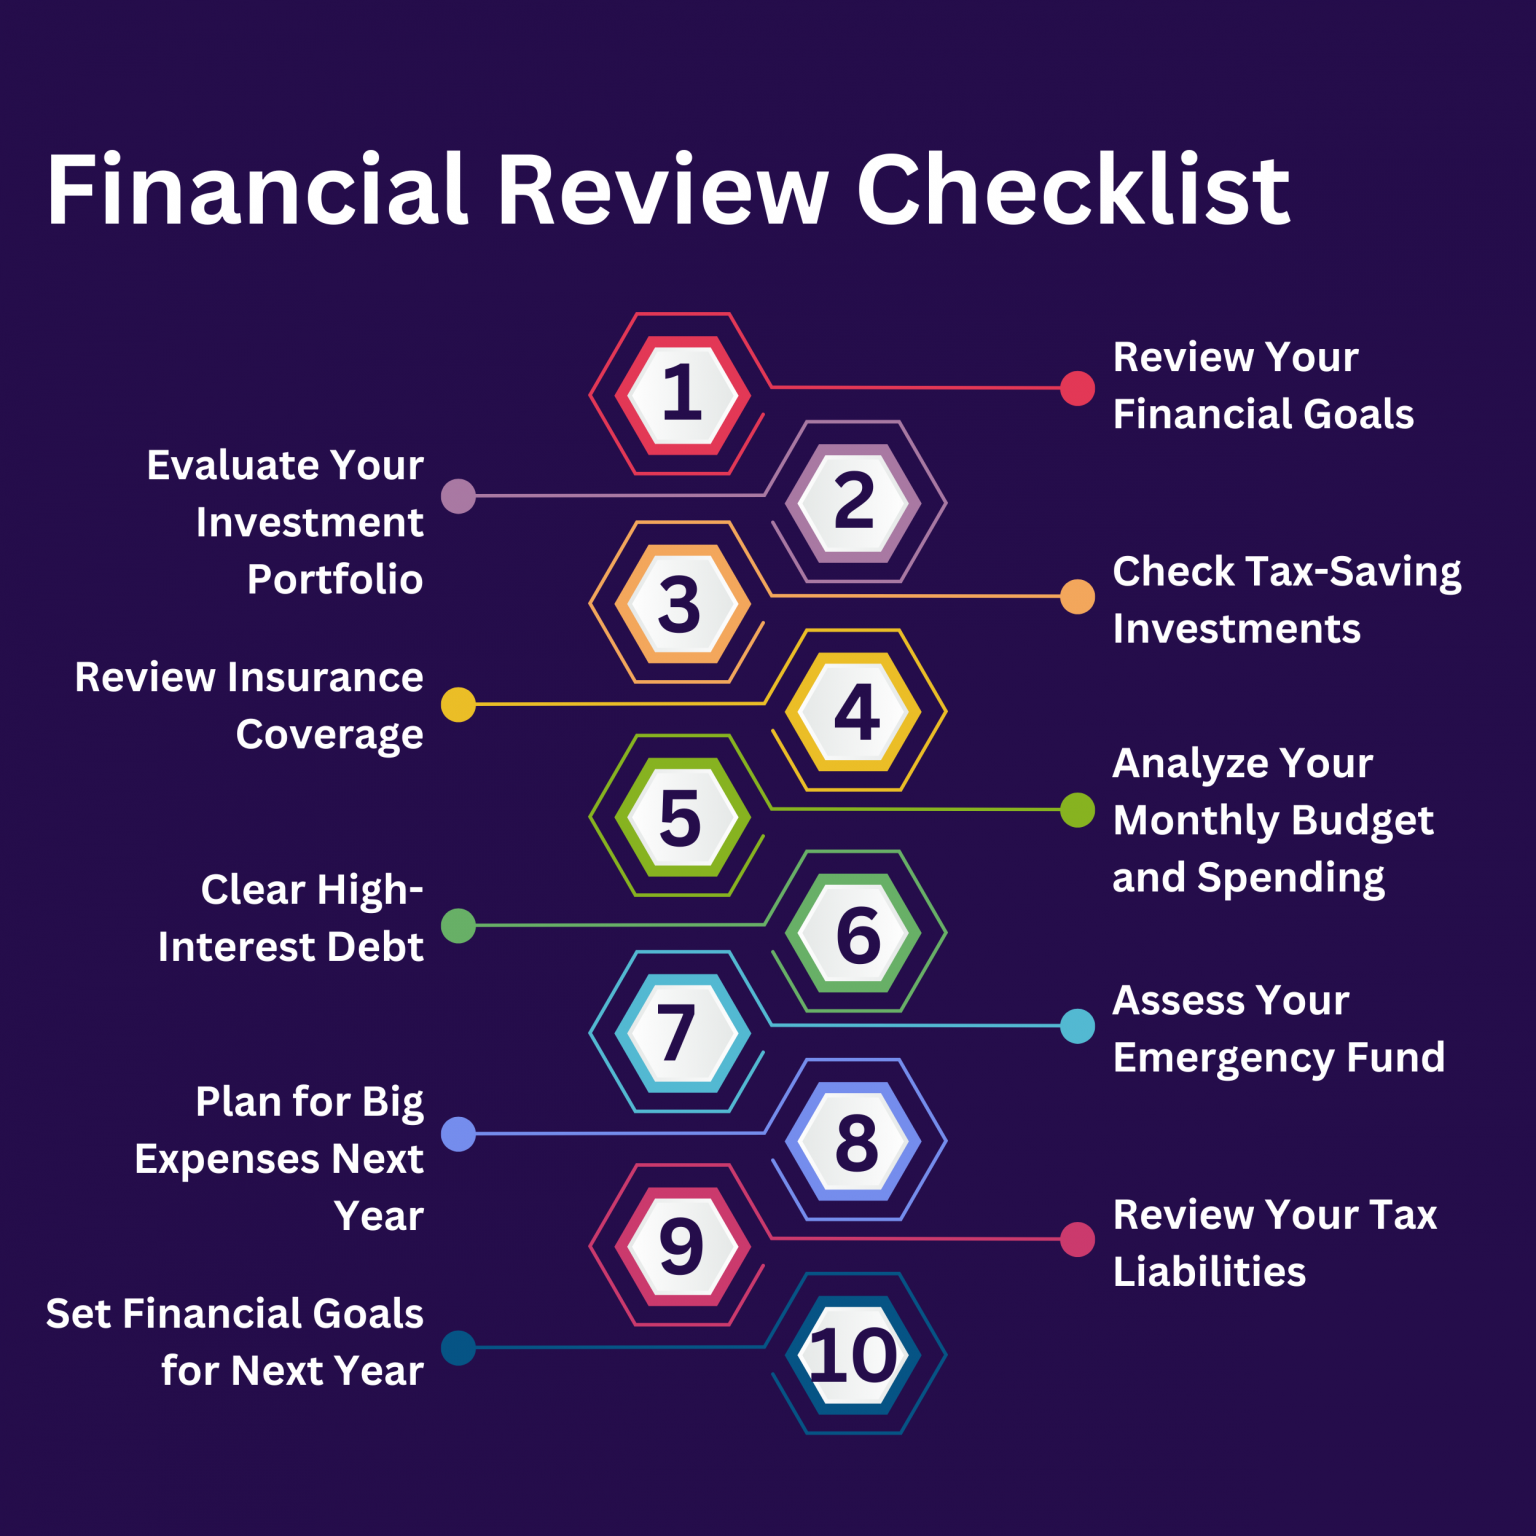
End-of-Year Financial Checklist: 10 Must-Do Reviews
10-Step Financial Checklist to Get on Track Financially | Financial checklist, Financial ...
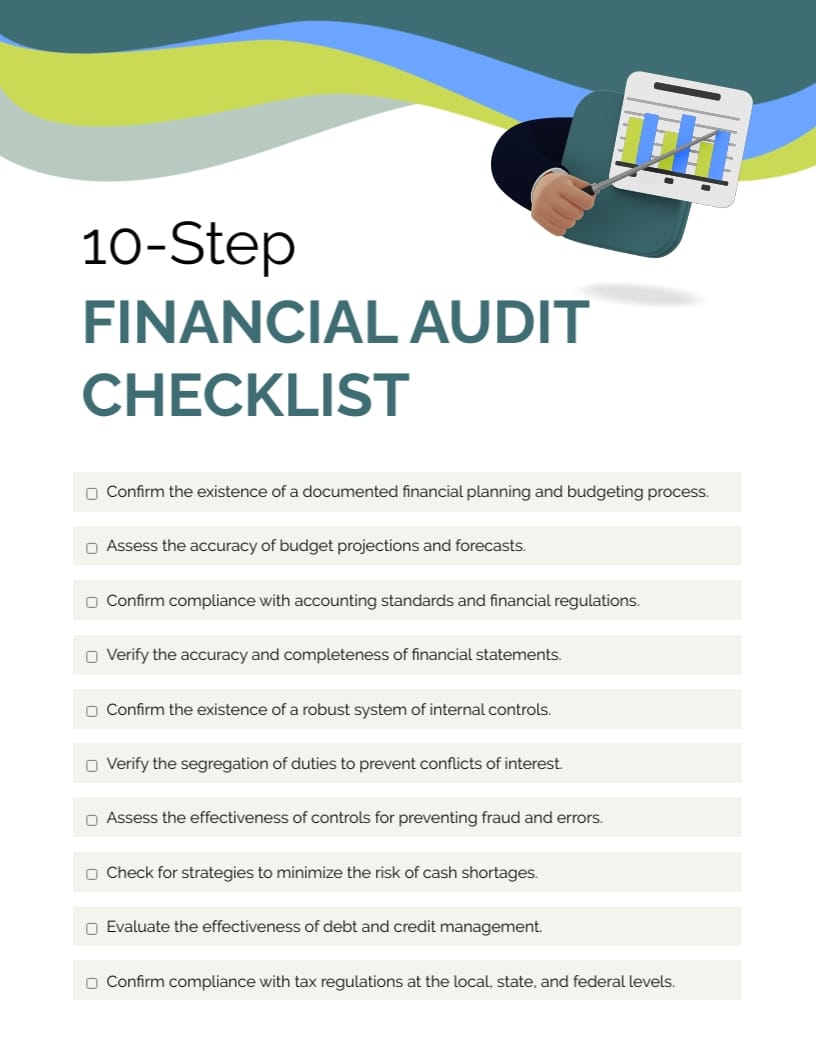
10 Step Financial Audit Checklist Template | Visme
Your Ultimate Finance Checklist
Finance Checklist