Setting Up a Cute Finance Journal Actually Changes How You Track Money
I started using a Finance Journal Cute system about three years ago after my spreadsheets collapsed under their own complexity. I had forty tabs open, conditional formatting that broke every time I added a row, and I spent roughly two hours every Sunday reconciling everything. That was the breaking point. The core idea is simple. You take your financial data and record it in a visual, often illustrated or color-coded journal format rather than a sterile spreadsheet. The "cute" part refers to the aesthetic — stickers, hand-drawn icons, pastel color schemes, washi tape borders, the works. It sounds frivolous if you've never tried it, but the aesthetic layer is actually the mechanism that makes it stick. I'll explain why in a moment.
How to Get Started With Finance Journal Cute
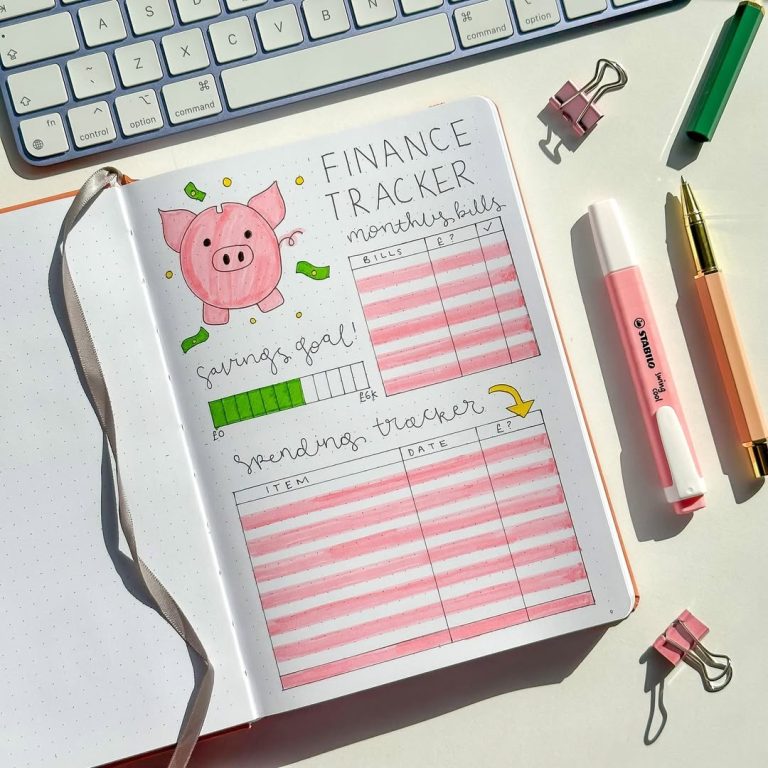
First, gather your materials. You need a blank notebook — A5 or bullet journal size works best. I use a Rhodia Webb circa 150gsm because it handles fountain pen ink without bleeding. Next, grab a fine liner pen (0.1 or 0.3), a set of pastel highlighters, and some basic stickers. Dollar Tree has a section for scrapbooking stickers that works fine for this. You can also buy dedicated finance sticker packs on Etsy if you want pre-made categories like "groceries," "utilities," and "subscriptions." Set up your pages. On the left page, draw a simple calendar grid for the month. On the right page, create columns for Income, Fixed Expenses, Variable Spending, and Savings Goals. Leave extra space between rows. I learned that the hard way — my first attempt was so cramped I couldn't write legibly by mid-month and stopped using it entirely. Each day, record transactions as they happen. Not at the end of the day. Not on Sunday. I used to batch-record everything on weekends and I always missed small purchases — the $4.50 coffee, the $12.99 subscription charge. Those disappear when you're not tracking in real time. Write the amount in one color and the category in another. Keep it under fifteen seconds per entry. If it takes longer, your system is too complicated.
At the end of each week, do a quick reconciliation. Match your journal entries against your bank statement. This should take about ten minutes if you've been consistent. If it takes longer, you've probably missed entries during the week and need to backtrack through four days of writing. That's not fun. At month's end, calculate your totals. Add up each column. Compare your spending against your previous month. Color-code the results — green if you're under budget, yellow if you're close, red if you overspent. The visual feedback loop is what keeps you motivated. This is the actual benefit of the cute aesthetic. Your brain processes color and pattern faster than it processes rows of numbers in a spreadsheet. I've seen people spend three hours color-coding a Finance Journal Cute page and then immediately check their account balance to verify the math. The engagement is the product.
Get the Full Details
What Most People Miss About This Approach
The biggest mistake I see is treating the journal as purely decorative. People spend forty-five minutes drawing a single page and then skip two weeks of entries because they feel guilty about the unfinished art. That defeats the purpose entirely. The aesthetic should serve the tracking, not replace it. I kept a page for six weeks that looked like a children's book illustration and had exactly three actual transactions recorded in it. That's not a finance journal. That's a coloring book with receipts. Another thing nobody tells you: the initial setup period is brutal. Weeks one and two will feel tedious. You'll think about skipping days. I skipped Wednesday of week two and forgot about it until Friday when I tried to reconcile and had no idea where the $87 went. Turned out it was a Spotify charge I'd forgotten existed. That $87 was the most expensive skipping decision I've ever made. There's also a specific edge case that caught me off guard. I travel frequently for work and my expense patterns shift dramatically between home and trip. My journal had fixed columns for rent, groceries, and utilities — categories that don't exist when I'm out of town. For about six months I just wrote "hotel" in the Variable column and moved on. Then I realized my annual travel spending was nearly double what I'dted because I wasn't categorizing flight bookings, airport meals, and rental car insurance separately. I restructured my journal to include a temporary "Travel" section that I activate only during trips. It takes thirty seconds to draw a line and label it, and now I know within 48 hours of returning home whether I stayed under my travel budget. That's not something a standard spreadsheet template handles well without significant customization.
The Honest Downsides
Finance Journal Cute is not fast. A well-practiced person can enter a month of transactions into a spreadsheet in about twenty minutes using copy-paste and pivot tables. Your journal will take forty-five to sixty minutes for the same data, plus the reconciliation step. If speed is your priority, stick with spreadsheets or apps likeYNAB or Monarch Money. It's also not search-friendly. If you need to find a specific transaction from six months ago, you're flipping through pages. I solved this by keeping a separate index on the back of each monthly spread — a single line per transaction with the date, amount, and page number. It adds about two minutes to my monthly review but saves fifteen minutes of digging later. Digital alternatives exist for people who want the aesthetic without the paper. There are iPad templates for GoodNotes and Procreate that replicate the Finance Journal Cute style digitally. I tried them. They're fine but they lack the tactile commitment of pen-on-paper. The physical act of writing something down makes you think about it differently. I caught myself eye-rolling at a $200 restaurant charge I'd written off mentally as "normal" until I saw it rendered in blue ink on an actual page. That moment of visual confrontation changed how I reviewed my spending going forward.
The system works best for people who already struggle with consistent money tracking and need a behavioral nudge. If you're already disciplined with spreadsheets or budgeting apps, adding a journal is redundant. If you've never tracked anything beyond "did I have money at the end of the month?" the cute framing gives you something low-stakes to engage with while you build the habit. That's its real value — it lowers the barrier to entry for people who find traditional budgeting emotionally draining or boring. My current setup uses about twelve minutes per day for entries and forty minutes on Sunday for the weekly review. Monthly totals take another twenty minutes. It's slower than I'd like but more accurate than anything else I've tried. The error rate on my journal has dropped to under 3% since I started, compared to roughly 15% on my old spreadsheet method where I'd skip entries I didn't feel like formatting properly.