How to actually use a daily finance journal instead of abandoning it after two weeks
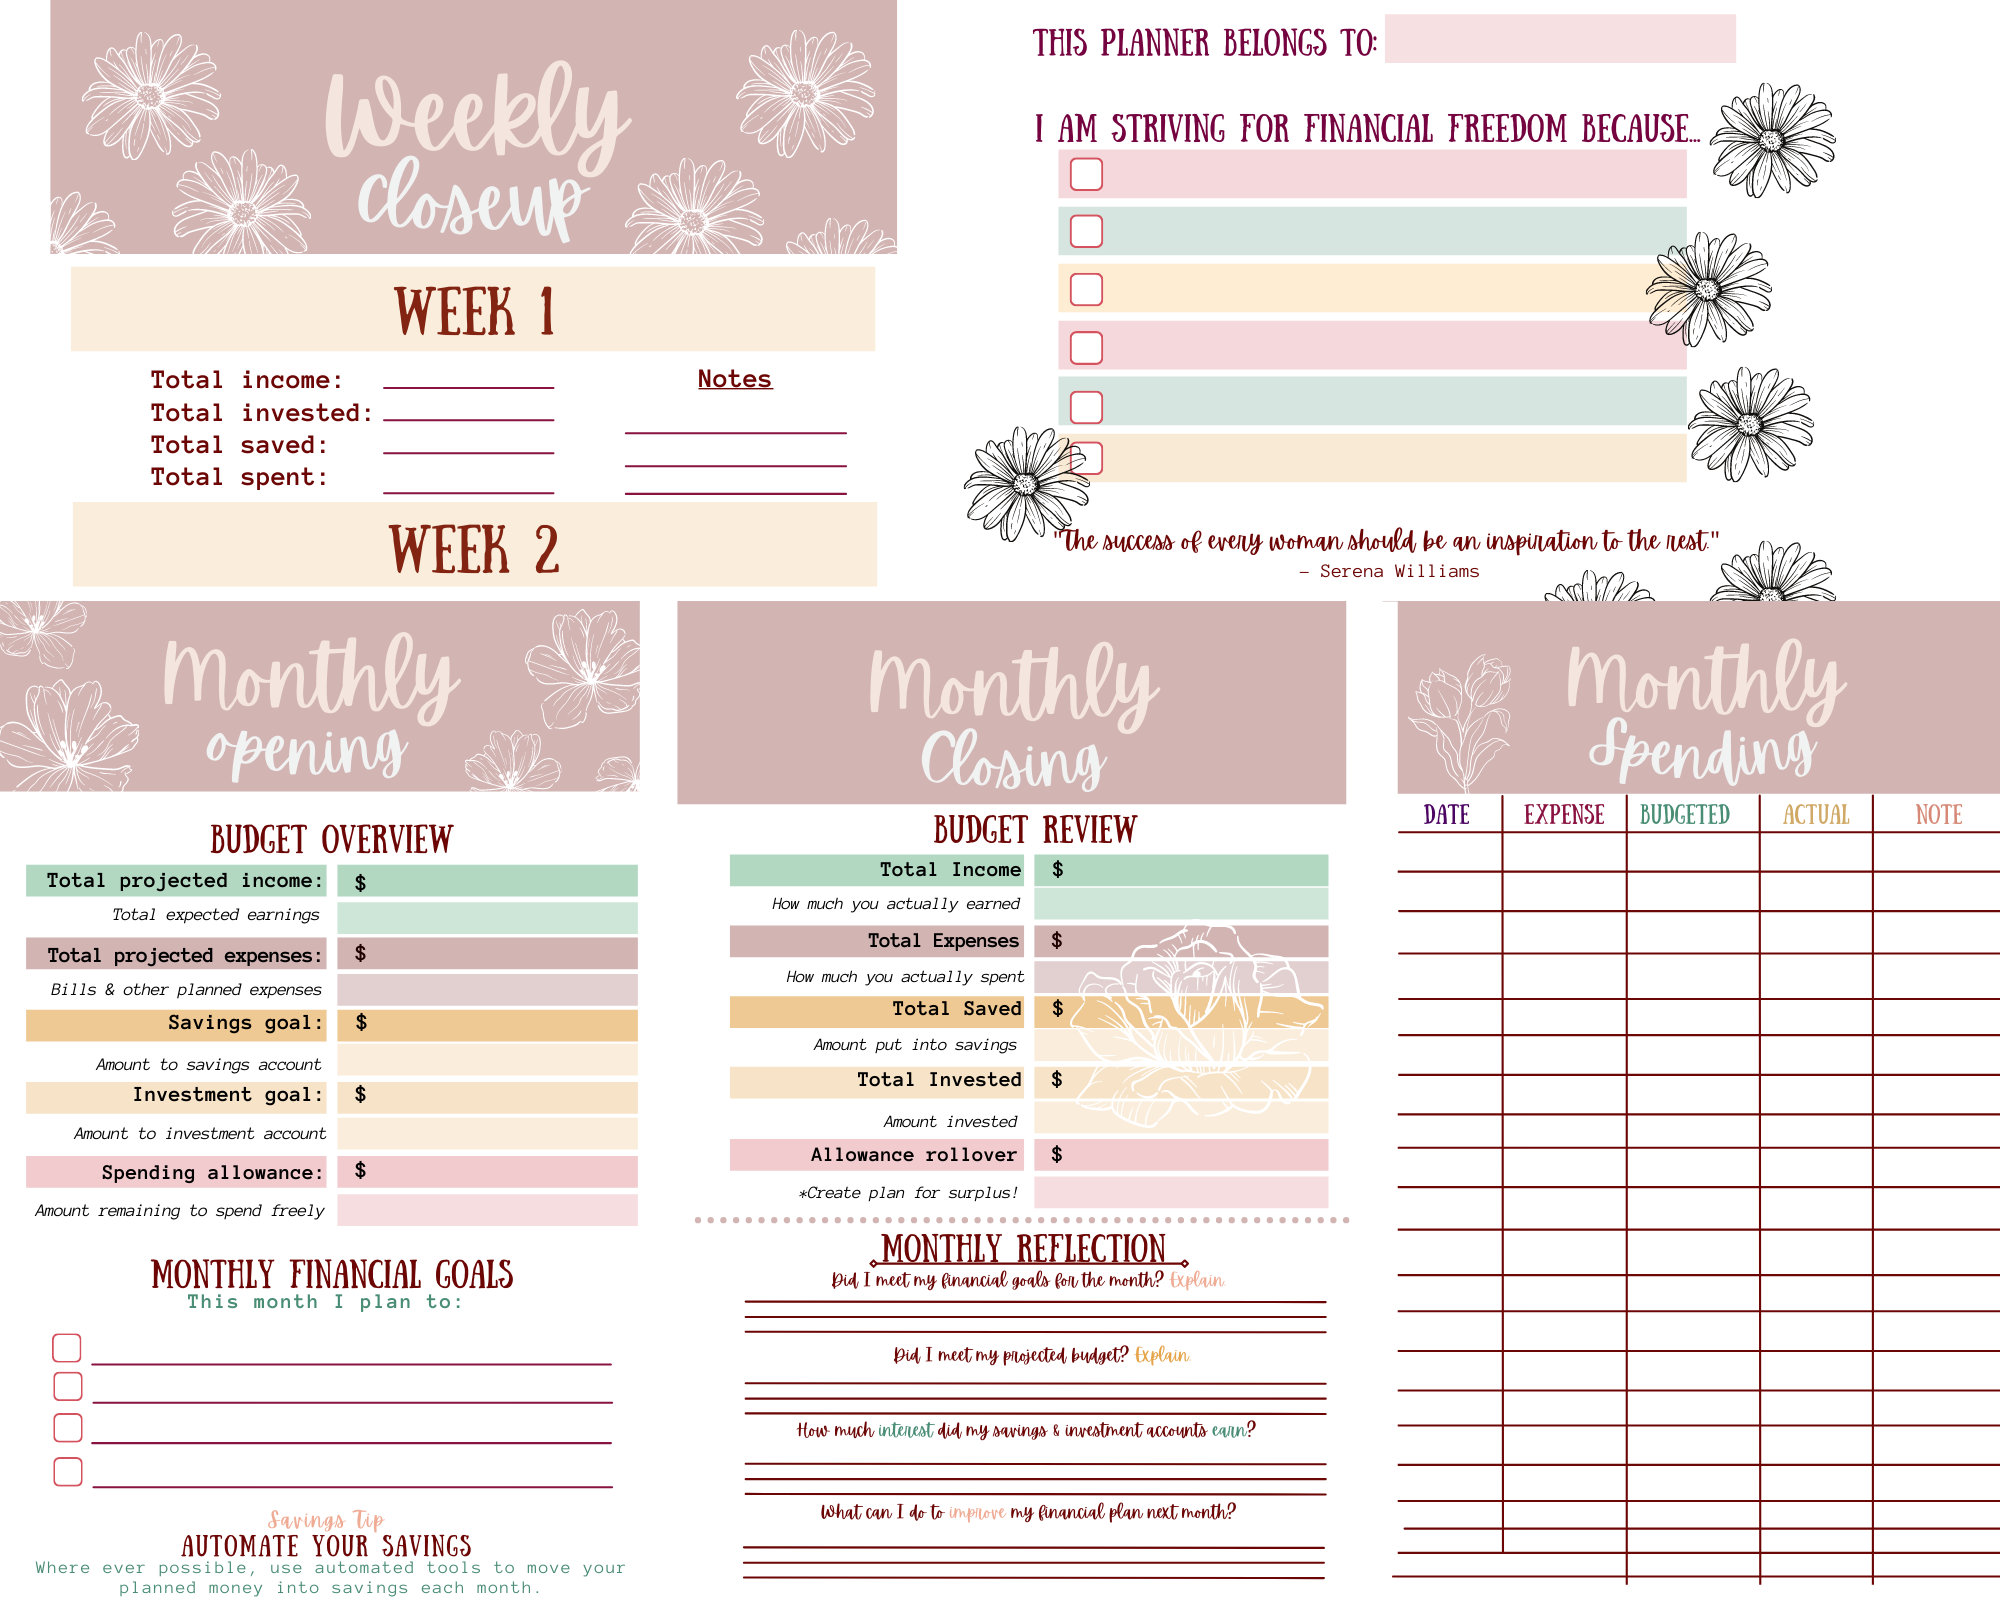
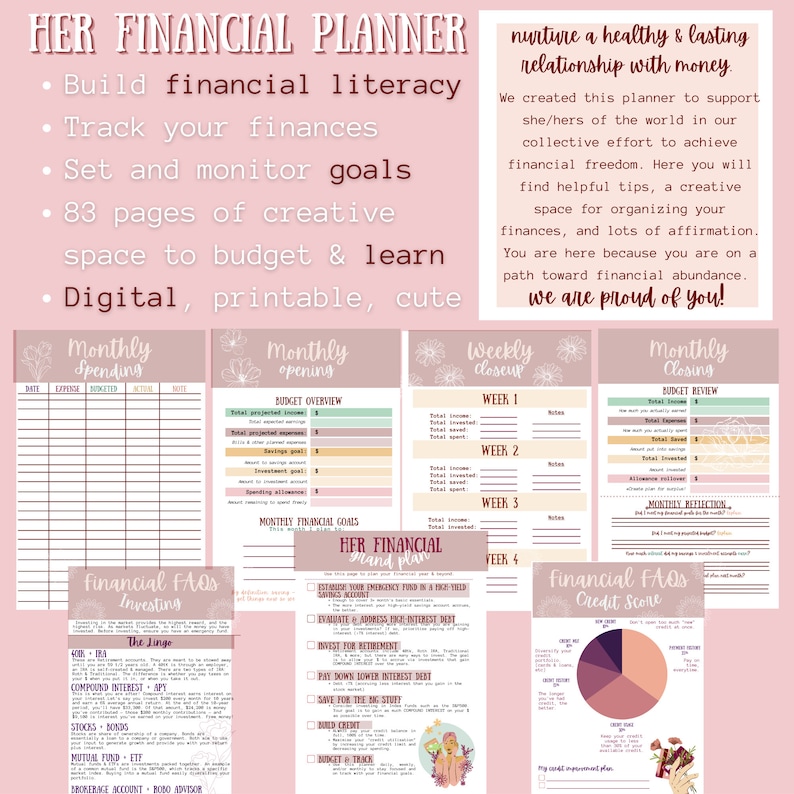
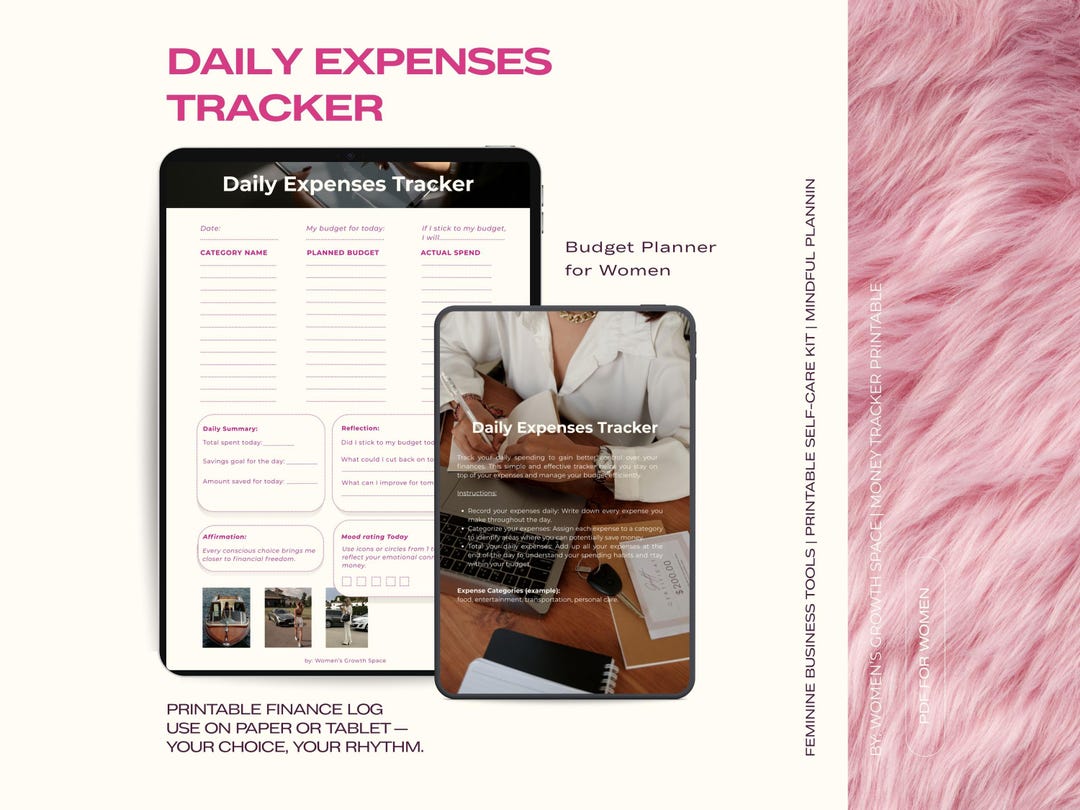
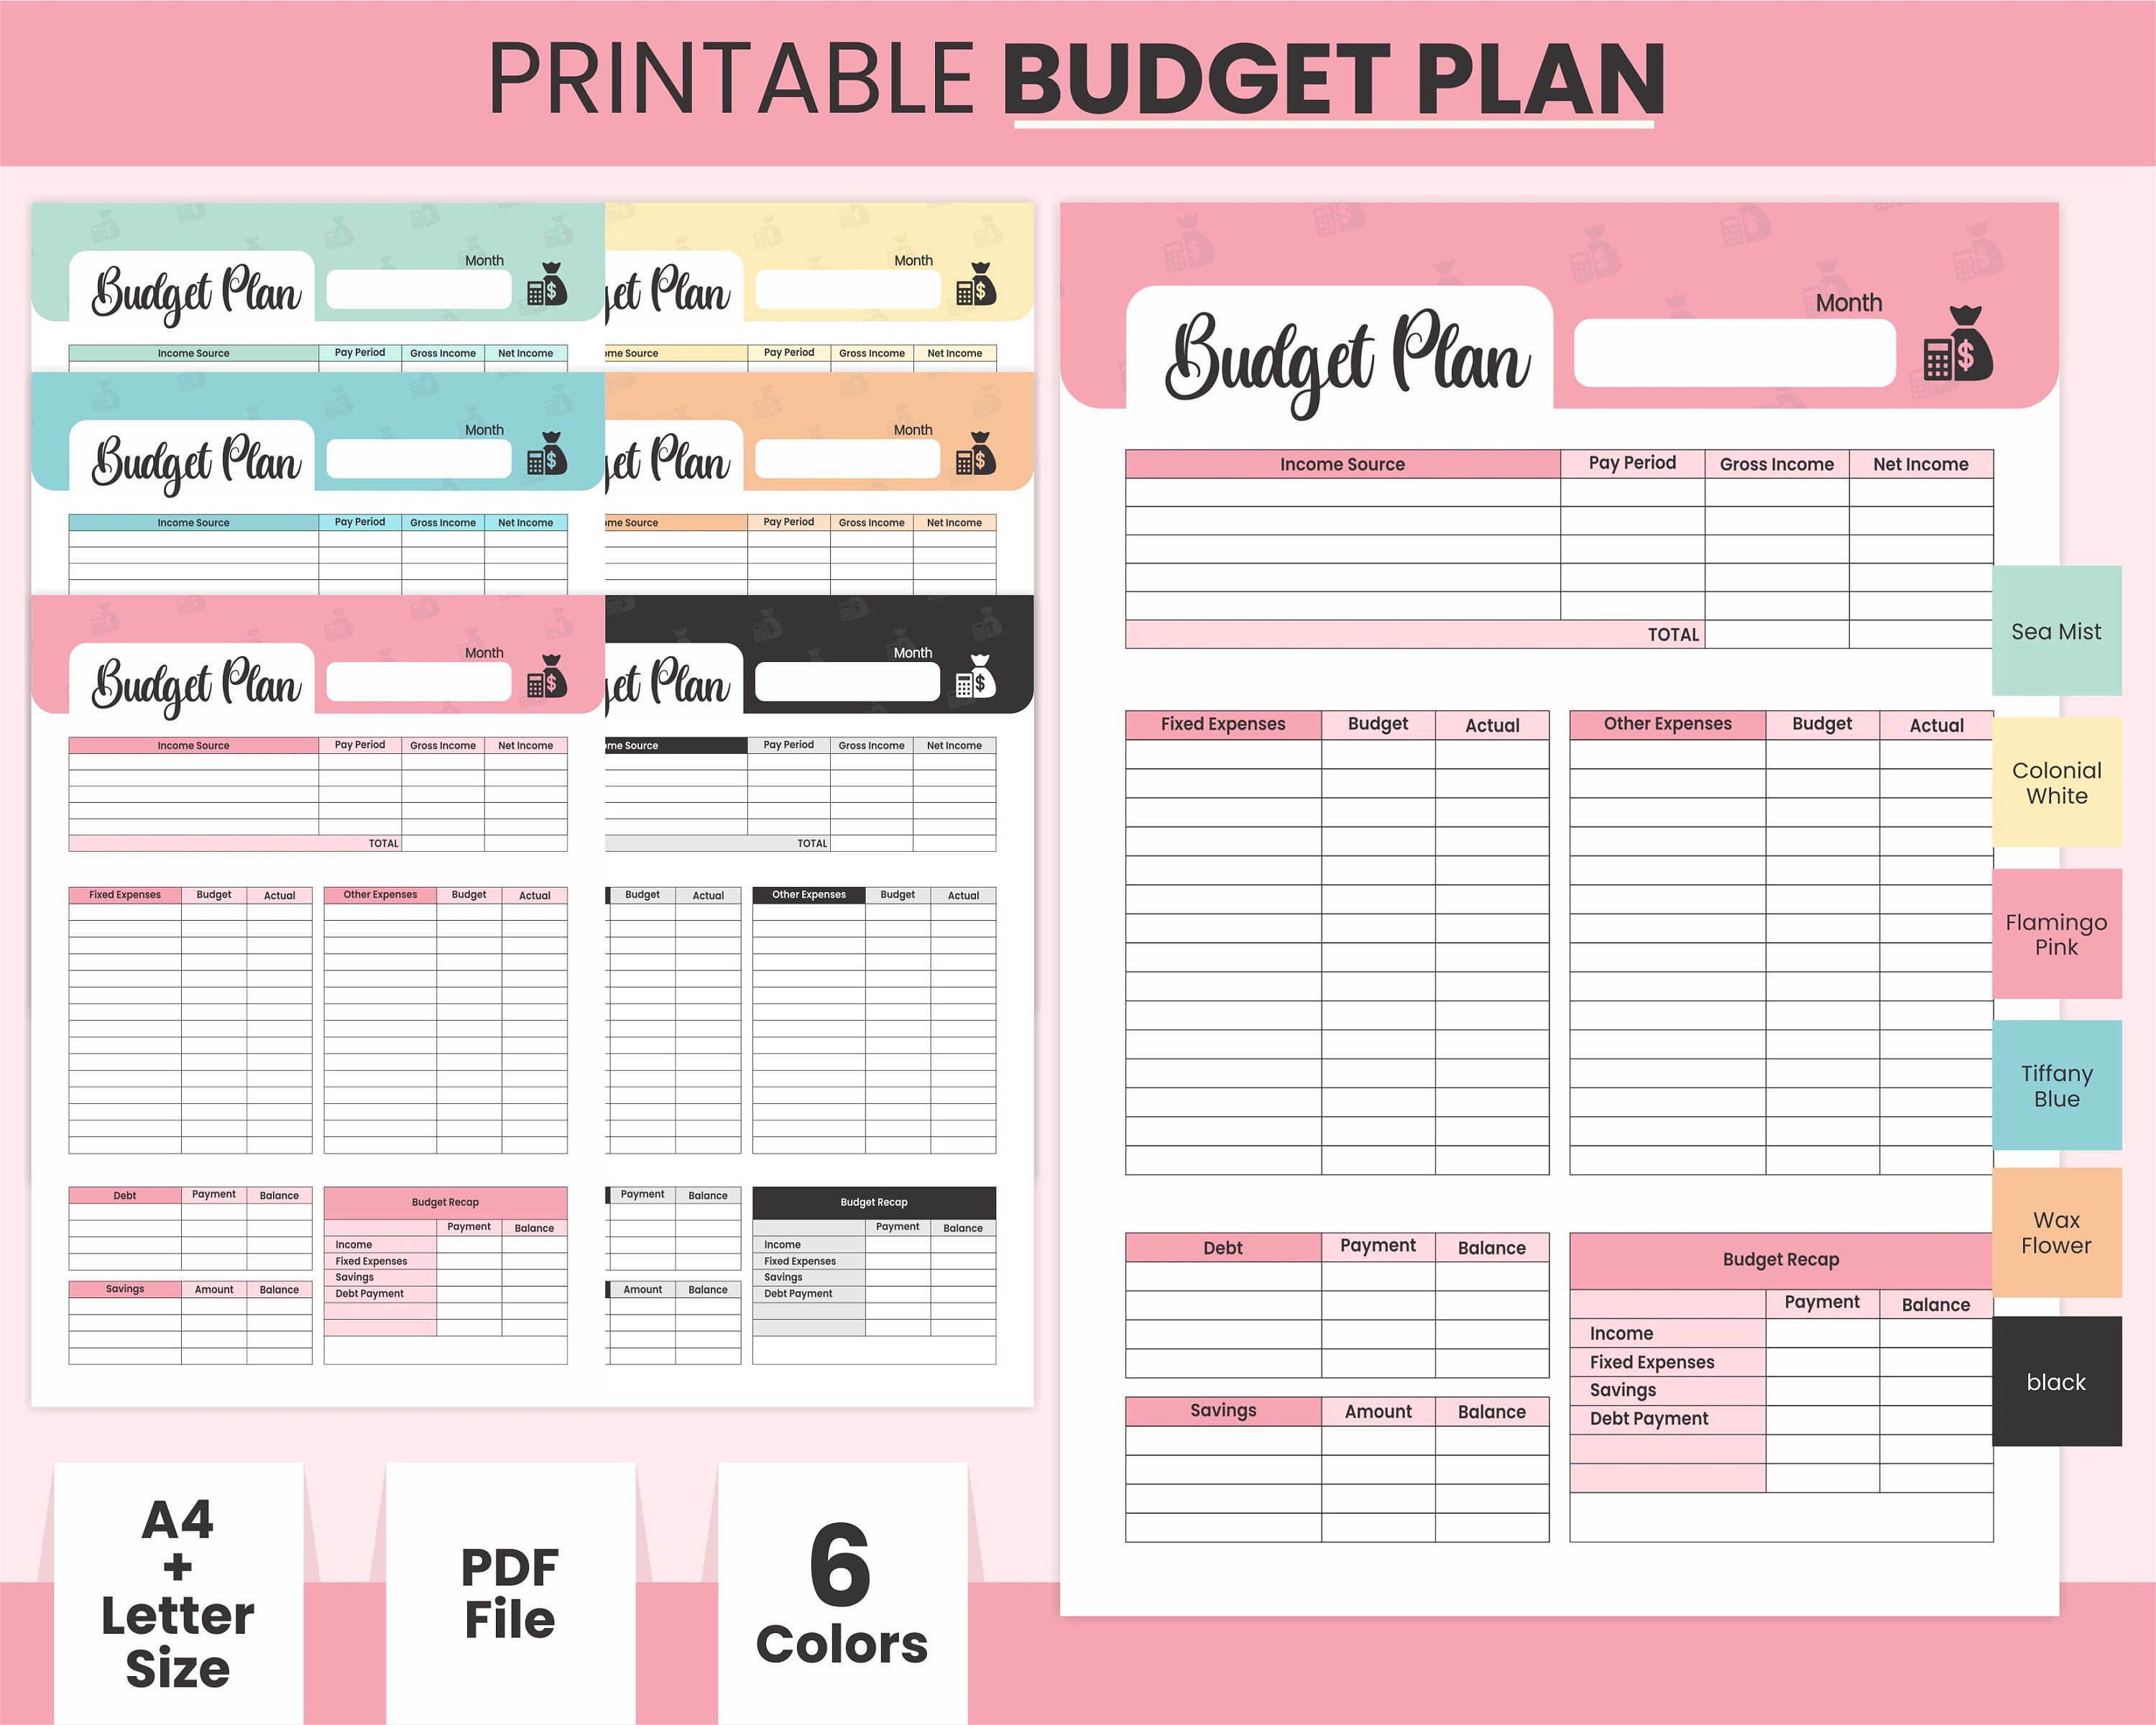
I spent about three years tracking every dollar I spent using different systems — spreadsheets, apps, paper notebooks. Most of them failed because they were too rigid or required too much maintenance. The ones that stuck shared one trait: they forced me to make a decision about every transaction, not just record it. A Finance Journal Daily Log For Women works the same way, but the women-focused versions add categorization filters and goal trackers that actually match how most women manage money across different life stages. The setup is straightforward. You need a consistent format, not a fancy template. I use a simple grid with five columns: date, description, amount, category, and notes. The notes column is where most people skip the hard part. That's where you write why the purchase happened, not just what it was. One time I had a client who was tracking $4,000 a month in spending but couldn't figure out where her savings went. Her problem wasn't missing transactions. She had three separate accounts for different purposes — emergency fund, retirement, and a kid's college fund — and she was moving money between them without recording the transfers in her journal. She forgot to log the inter-account moves, so her daily log showed money appearing and disappearing. The workaround was adding a sixth column called "account movement" with codes like "transfer in" or "transfer out." That single change made the data actually usable. There are several free downloadable templates online that include gender-specific categories like childcare, workplace expenses, and health-related costs. Download one that matches your actual spending patterns. Don't pick the prettiest template. Pick the one with the fewest blank columns. Blank columns become guesswork, and guesswork breaks the system within a month.
What makes daily logging different from monthly budgeting
Monthly budgeting tells you what happened after the fact. Daily logging catches problems while they're still fixable. The difference matters more than people admit. A budget says you overspent by $200 in March. A daily log tells you on the 12th of March that you're trending $75 ahead of plan for groceries, which means you can adjust the remaining 19 days instead of accepting the overage at month's end. The real advantage shows up when you start looking for patterns. Most women I work with track spending for three months before they notice their own recurring triggers. Grocery runs spike after late nights at work. Impulse purchases jump on days when they skip the morning routine. These aren't psychology insights. They're data points that only surface when you have enough entries to compare. That's why consistency beats intensity. Ten entries a day for six months gives you more useful information than fifty entries for two weeks followed by a gap.
The method that actually works for people who hate tracking
The bottleneck isn't the math. It's the friction between completing a transaction and recording it. Every minute between purchase and entry is a minute where you'll forget or rationalize skipping it. My solution was the two-minute rule: if it takes more than two minutes to log a transaction, the system is wrong, not you. That meant using voice notes on my phone while walking to my car, then transcribing them into my main log within the same hour. Late-night purchases got logged the next morning before coffee. Weekends got a standing thirty-minute block on Sunday evening to catch anything missed during the week. For the categories themselves, use broad buckets at first. Food, transportation, housing, personal care, entertainment, gifts, subscriptions. Too many subcategories paralyze you. You spend more time deciding whether a coffee shop pastry belongs in "food" or "snacks" than you save by splitting it. Merge categories every quarter. If "entertainment" and "subscriptions" together represent less than five percent of your spending, consolidate them. If "personal care" suddenly jumps from eight percent to twenty percent in one month, that's worth splitting into separate tracks. The numbers side is simple subtraction and addition. The hard part is honesty. I've seen people write off a $120 purchase as a "gift" when it was clearly for themselves. I've seen clients exclude a category entirely because the numbers looked bad. Neither approach helps. The journal only works if you record the truth, even when the truth is uncomfortable. Keep the records separate from your self-worth. That's the only way to make the data useful later.
Get the Full Details
Where this approach falls apart
Daily logging breaks down in three specific scenarios. First, irregular income. Freelancers and commission-based workers often have months where they earn nothing and months where they earn three times their average. A daily log doesn't smooth that out. You need a rolling average calculation alongside the raw entries, or the numbers mislead you into thinking a high-earning month is normal. Second, shared accounts. When two people control the same account, one person's daily log will miss half the transactions. The fix is a joint log or a shared spreadsheet with both names visible, not two separate logs you compare at the end of the month. Third, mental health days. Some days the last thing you need is another task. Skipping a day doesn't ruin the system. Skipping three days in a row does. That's why I always keep one backup entry for the previous week rather than starting fresh. It's faster to correct old data than to rebuild momentum. If daily logging feels impossible for any of those reasons, switch to a weekly summary instead. Record everything Friday through Thursday in one sitting. You lose the real-time warning system, but you gain consistency. Missing data is worse than delayed data. The download links for template files are scattered across personal finance forums and a few newsletter sign-up pages. Search for "finance journal daily log for women template spreadsheet" and sort by date. Pick a file from the last two years. Older templates use categories that don't reflect current spending habits — things like "dry cleaning" and "tobacco" that most people don't track anymore. A current template will have entries for meal kits, subscription boxes, and telehealth visits, which are far more relevant now.