The Simplest Way to Actually Track Where Your Money Goes
I spent four years trying different budgeting systems before landing on something that actually stuck. The Finance Journal Minimalist For Self Improvement approach stripped away everything I found unnecessary and left just the core mechanism: write down what you spent, see where it went, adjust. Here is how I set it up and what I changed after three months of daily use.
Setting Up Your Finance Journal Minimalist For Self Improvement System
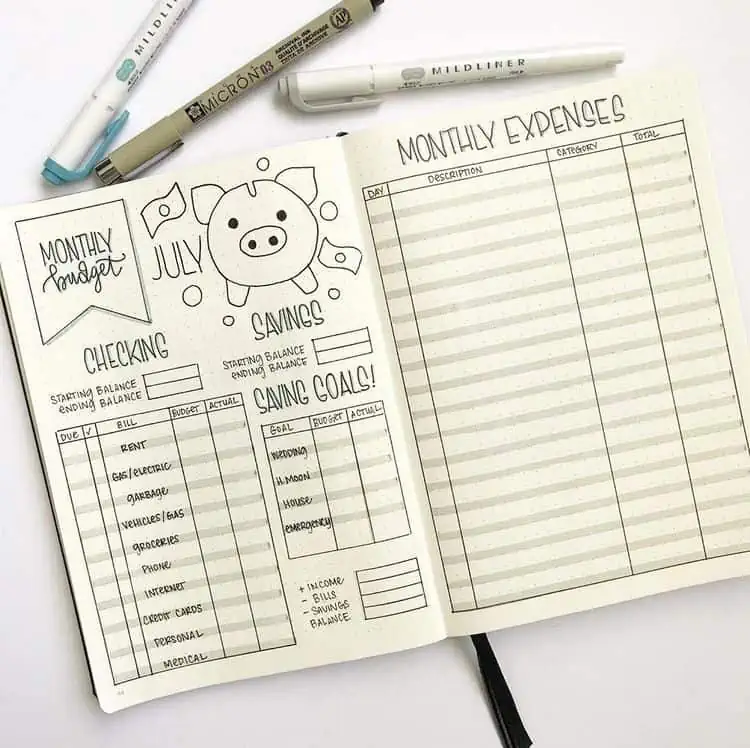
You do not need fancy software. I use a Google Sheet with four columns: Date, Description, Amount, Category. That is it. Every entry takes roughly 30 seconds. Monthly review takes about 15 minutes if you stayed consistent. If you skipped days like I did in month two, it jumps to about 40 minutes because you are reconstructing memory instead of reading recorded data. Categorization is where people either commit or quit. I recommend starting with five broad buckets: Housing, Food, Transportation, Personal/Entertainment, and Savings/Debt Payments. You can refine later. The initial goal is simply catching everything. A missed category is worse than a messy one. I initially tried using the YNAB envelope system, then EveryDollar, then a custom Excel spreadsheet with conditional formatting that took longer to maintain than my actual spending. The minimalist journal beat all of them because friction was nearly zero. Open sheet, type number, close sheet.
The One Trick That Actually Changed My Behavior
Most people track spending but never change anything. The difference between my three years of flatlined saving and the single year I finally built a six-month emergency fund came down to one rule: I reviewed the previous month's total spending every Sunday evening before I did anything else. Not during the month. Not at tax time. Sunday. Ten minutes. Just look at the numbers. This timing matters because you have the full picture of the past month and the full weekend ahead to make adjustments before new spending accumulates. Checking mid-month feels too late. Checking quarterly is academic. I also learned the hard way that cash expenses are the biggest blind spot. Card transactions auto-populate. Cash disappears. I started carrying a small notebook in my pocket for cash purchases and transferred those entries to my sheet within 24 hours. This eliminated roughly $200 a month in previously invisible spending that I discovered in the first two weeks.
Get the Full Details

What This Approach Does Not Do Well
Be honest about the limitations. A minimalist finance journal will not automate categorization. It will not reconcile against your bank statement. It will not alert you to subscription creep or negotiate lower rates. If you have complex finances with multiple accounts, investments, and debt structures across institutions, this system alone will feel inadequate within six months. I hit that wall myself. My simple journal worked perfectly for two years of straightforward salary and rent. Then I started freelancing with irregular income, and suddenly I needed cash flow forecasting, which the sheet did not provide. I added a separate tab for that. The core journal stayed minimal; I built lightweight extensions only where the gaps appeared. Another real problem: the enthusiasm decay. Weeks four through six always feel pointless because you have been tracking everything and your behavior has not visibly changed yet. The data only becomes useful in retrospect. Most people abandon the system during this window. I kept going because I knew the insight would come in month three, and it did. The pattern I spotted was that 60 percent of my discretionary spending happened on Thursday and Friday nights between 7 PM and 10 PM. That single insight alone saved me about $400 monthly once I started setting a hard cutoff.
Practical Setup Walkthrough
Create a new Google Sheet. Label the columns A through E: Date, Description, Amount, Category, Notes. Use Data Validation on the Category column to create a dropdown list from your five buckets. Format the Amount column as currency. Freeze the top row so headers stay visible. That is the entire tool. Download my current template structure at this link and adapt it to your own categories. No premium features, no subscriptions attached. Just a clean sheet that I have used since March 2024 and revised twice based on what actually worked in practice.
Common Mistakes Beginners Make With a Finance Journal Minimalist For Self Improvement Routine
First, over-categorizing early on. I created twenty categories in my first week and spent more time debating whether a grocery run counted as Food or Personal. Two weeks later I had 147 uncategorized items and quit. BROAD categories first. Precision comes from analysis, not from setup. Second, treating the journal as a punishment tool. If you log every coffee purchase with guilt, you will stop logging. I reframed it as data collection. A number is not a moral judgment. It is just information. This mental shift mattered more than any spreadsheet tweak. Third, ignoring the notes column entirely. I started adding a short note when spending felt unusual. Those notes became the most valuable part of the entire system. Looking back, I could see exactly why October was 40 percent above average: my car broke down twice and I ordered replacement parts online instead of going to a shop. The note told the story the numbers alone could not.
When to Upgrade Beyond the Minimalist Journal
If your monthly spend exceeds five figure discretionary categories, or you manage money for a household with multiple income streams, a basic journal will eventually slow you down. At that point I moved to a hybrid approach: keep the minimalist journal for quick daily entries, then export the data quarterly into a more detailed budgeting tool for deeper analysis. The journal captured the raw data faster than any app I could manually configure. The system is not glamorous. It does not predict your financial future or motivate you with streaks and badges. It gives you one thing: a clear record of where money went, reviewed consistently, adjusted deliberately. That is enough if you actually use it.