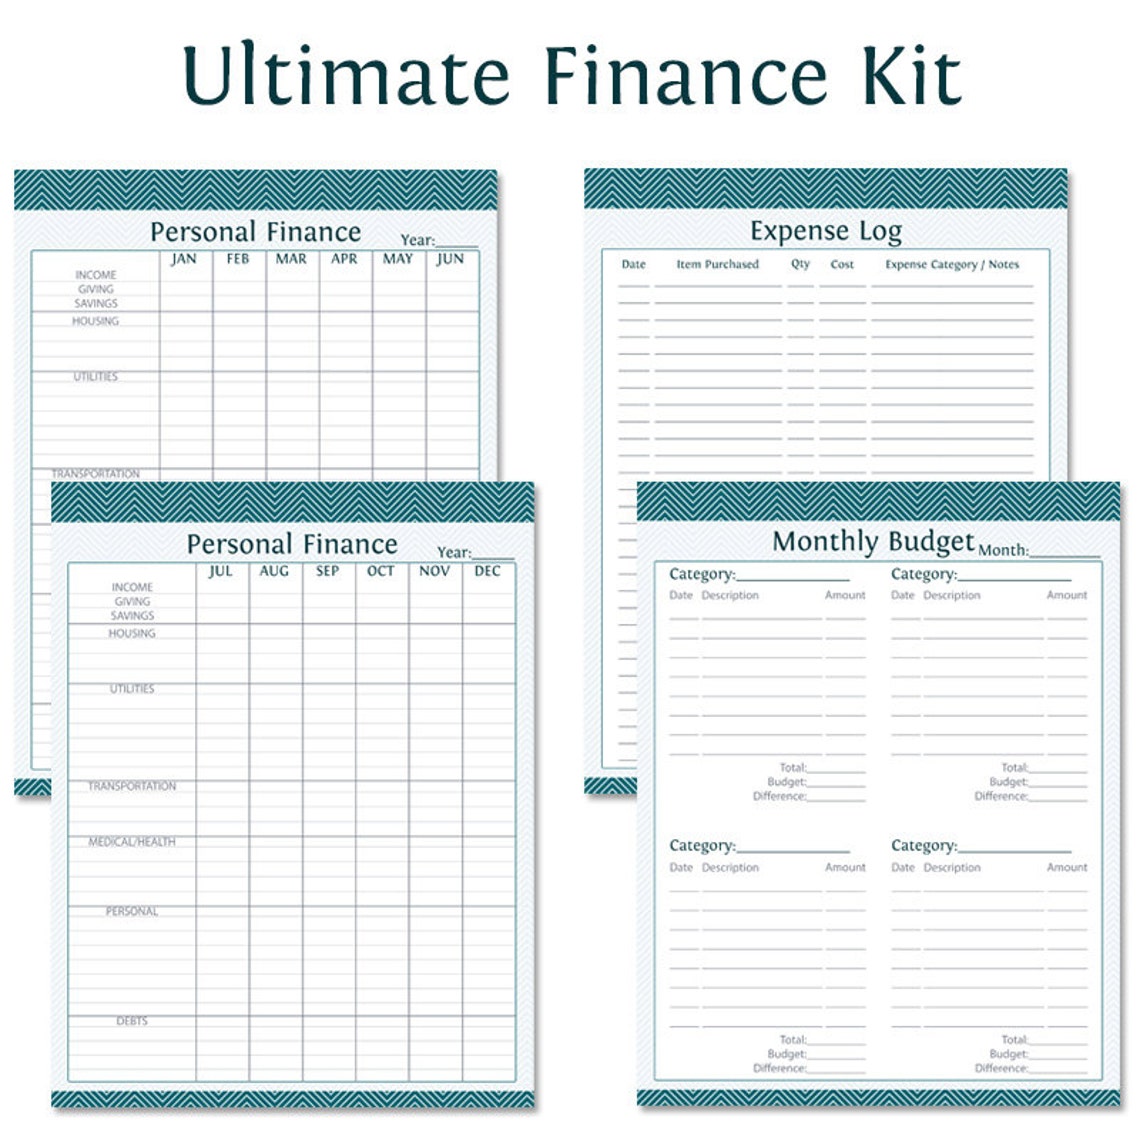
Getting Started With Finance Printable Essential
A finance printable is just a structured sheet you print and fill out by hand, designed to track spending, budgets, savings goals, debt payoff, or monthly financial reviews. The Finance Printable Essential you find online is usually a bundle of these sheets formatted for letter-size paper. They range from simple expense logs to detailed monthly budget planners with columns for income, fixed costs, variable spending, and savings targets. I spent years wrestling with spreadsheets before switching to a physical system because my screen time was already through the roof and I kept forgetting to open the budget file. A binder with fresh printables every month ended up working better than anything digital for my habits. Here is how I actually do it. You need a three-ring binder, sheet protectors or just loose-leaf pages, a hole punch, and the printable itself. I print each sheet on standard 8.5 by 11 paper using a laser printer because ink smears if you write over it quickly with a gel pen. The cost per sheet is basically nothing. I keep two months of printed pages in the binder at all times so I am not constantly reprinting.
The setup process is straightforward. You download the printable, open it in any PDF viewer, and print. Some templates have multiple pages for different sections like a monthly budget overview, a weekly spending log, a debt tracker, and a savings goal sheet. I print all of them at once and sort them into the binder in the order I actually use them. My preferred order is the monthly budget first, then the weekly tracker, then debt and savings pages at the back. One thing nobody mentions when they talk about these printables: the lines are often too narrow for people who write larger. I learned this the hard way on my first month. I used a fine-tip pen and the numbers bled into the next row. My workaround was simple. I set the printer to fit-to-page at 95 percent instead of actual size. That added just enough spacing between rows that my handwriting stopped fighting the grid. It also makes it easier to write percentages or notes in the margin columns.
What to Track When You Start
Most people skip the step of deciding what to track and just start filling in boxes blindly. That wastes a month. Before you print anything, sit down and list your actual income sources and your top five recurring expenses. Write those numbers down on a scrap of paper. Then look at the printable template and see if it has sections for both. If it does not, you will need to create a custom insert or accept that the template will not cover your situation fully. When I started using a Finance Printable Essential for real, I discovered that my variable expenses were wildly inconsistent. Grocery spending ranged from two hundred dollars to nine hundred depending on the month. The standard template had a flat grocery line item with no room for that kind of swing. I solved it by adding a secondary column labeled actual versus estimated and writing both numbers in every week. That small change gave me visibility into whether I was overshooting my estimates before the month ended.
Get the Full Details

A Common Mistake That Breaks The System
The biggest mistake I see is people treating the printable like a permanent record instead of a planning tool. They print one copy, fill it out for January, and never reprint it. By February they are either forcing new data into old pages or abandoning the whole thing. Printables are meant to be cycled monthly. I print a fresh set on the last weekend of every month and file the previous month away in a separate folder. This takes about twelve minutes. If you do not have a separate filing system, just keep the old months at the back of the same binder and leave the current month at the front. Another detail that matters more than people think is the type of pen. Ballpoint pens dig into cheap paper and make it wavy. Gel pens smear if you go over the same spot twice. I use a standard black pilot G2 or a Uniball Signo for long-term entries and a light blue mechanical pencil for estimates and notes. Blue pencil marks fade slightly over six months, which is useful because it signals to me which numbers were projections and which were confirmed spending. This distinction becomes important during tax season.
Where Finance Printable Essential Falls Short
These printables do not sync with your bank account. They do not categorize transactions automatically. They do not send reminders. If you miss a week of filling one out, there is no alert. You are entirely responsible for consistency. For some people that is fine. For others it means the binder gathers dust after three weeks. I also found that printable systems struggle with irregular income. If you are paid biweekly, monthly, or on a commission basis, the standard monthly layout does not match your cash flow. I had to modify my template to track by pay period instead of by calendar month. This meant printing a custom header for each pay period and creating a separate rolling total section. It took me about forty minutes to reconfigure, but once done it worked for over two years without changes. Another limitation is scale. If you have ten credit cards, multiple loans, and several side accounts, a single-page debt tracker will not capture everything. The finance printable essential bundles you find online usually assume a simple debt structure with two or three accounts. You will need to expand the tracker manually or combine multiple printables into one sheet by adjusting the margins in your printer settings.
Picking The Right Template
Not all printables are equal. Some are over-engineered with charts and color coding that require you to spend an hour each week matching categories to a legend. Others are nearly blank and force you to design your own structure. The middle ground is what I recommend. Look for a template that has predetermined categories for housing, utilities, groceries, transportation, debt payments, and discretionary spending, but leaves the category names editable. This gives you a starting point without locking you into someone else's assumptions about where your money goes. When I evaluate a new printable before printing it, I check three things. First, whether the total income line matches the total expense line by design. A broken template will let you fill in numbers that never balance. Second, whether there is a section for one-time or irregular expenses. Medical bills, car repairs, and annual subscriptions destroy monthly budgets if they are not explicitly tracked. Third, whether the printable includes a end-of-month review section where you can compare planned versus actual spending. Without that reflection step, the system becomes just another chore with no feedback loop.

Maintaining The System Long Term
Printable systems survive when they reduce friction, not add to it. If filling one out feels like homework, you will stop. I keep my supplies in a single drawer near where I pay bills so there is no excuse for not grabbing the binder. I also do the tracking on the same day each week, usually Sunday evening, because that is when my paychecks post and I know exactly what I have for the coming week. The consistency matters more than the perfection of any single entry. Some months I lose track for two or three weeks. I do not guilt myself into restarting. I just pick up the binder where it left off and fill in the missing numbers from my bank statement. Corrections are normal. The goal is visibility, not a clean record. Once a quarter I review the entire binder and look for patterns. Did spending in a certain category climb every single month? Is there a recurring fee I forgot about? These insights come from stacking months of data side by side, which is something digital apps do automatically but printables make you do manually. That manual effort is actually the point. You notice things you would otherwise scroll past.