What Actually Happens When You Type a Financial Question Into ChatGPT
Most people treat finance prompts like they are magic incantations. You type "how do I invest $10,000" and expect a five-star stock pick. It does not work that way. The LLM will give you generic advice that sounds plausible but will not hold up in practice, especially when your situation involves something specific like back-testing a strategy, handling tax-loss harvesting in a particular jurisdiction, or reconciling positions across three different brokerages.
I spent about six months building out a set of Finance Prompts templates for my team before we had anything actually usable. We kept getting answers that were either too vague to act on or confidently wrong on technical details. The problem was not the model itself. It was how we framed the input.
The Problem With Basic Finance Prompts
A naive prompt like "analyze this stock" gives you back a Wikipedia summary dressed up in AI language. It does not know your risk tolerance, your tax bracket, your time horizon, or whether you are trading a Roth IRA or a taxable account. None of that matters unless you put it in the prompt yourself.
Here is what actually works, based on hundreds of iterations and a lot of failed experiments.
You start by giving the model a concrete frame. Tell it what format you want, what constraints apply, and what not to do. For example, instead of asking "should I buy NVDA," you say: "I have a $15,000 taxable account, 10-year horizon, moderate risk tolerance. I own no semiconductor exposure currently. Give me a position sizing recommendation with entry zones, stop levels, and a max allocation percentage. Do not give general investment advice. Cite data sources with dates." The response you get back is dramatically more useful because you forced the model to operate inside actual boundaries. That second part is the one most people skip. "Do not give general investment advice" is not just a disclaimer request. It is a functional constraint that tells the model to stay in analytical mode rather than reverting to safe hedging language that nobody needs.
How to Structure Effective Prompts for Financial Analysis
I keep a running document of Finance Prompts structures that I reuse and adapt. There are three layers to every good financial prompt: context, task, and output specification.
The context layer answers the question of what the model needs to know before it can give you a decent answer. Your account type, your current holdings, your time horizon, your tax situation, your geographic location for regulatory reasons. If you are in the EU and asking about US equities, the model should know that MiFID II constraints may apply. If you are in Canada, RRSP vs TFSA distinctions matter enormously for tax-efficiency calculations.
The task layer is where you state exactly what you want. "Compare these three ETFs on expense ratio, tracking error, and turnover" is infinitely better than "which ETF should I buy." The second prompt opens the door to a hundred generic paragraphs. The first one forces the model into a structured comparison.
The output specification is the part that actually saves time. Tell the model to return a markdown table, a bullet list, a CSV block, whatever you need. If you are feeding results into a spreadsheet later, ask for a delimited format upfront. This is something I learned the hard way after spending an hour reformatting a nicely generated investment comparison into something I could actually paste into Excel.
A Specific Edge Case That Broke Everything
About three months into this process, I ran into a problem that took me two weeks to resolve. I was trying to get the model to calculate the exact tax impact of selling a position in a Canadian non-registered account while also triggering the superficial loss rule. The prompt was fine. The model understood the question. The answer it gave was technically correct but missed the fact that I had already bought back the same securities within the 30-day window through a different brokerage account.
The superficial loss rule in Canada applies across all accounts owned by the same taxpayer, not just within a single brokerage. No prompt I wrote could force the model to know that I had already triggered this rule because the information simply was not in my context. I had to explicitly add: "Note: I repurchased the same security on March 12, 2024, in account number ending 4471 at another broker. Apply superficial loss rules accordingly."
That changed everything. The model then correctly identified the disallowed loss, calculated the adjusted cost base of the replacement shares, and showed the deferred tax impact. Without that single line, the answer was misleading in a way that would have cost me real money if I had followed it.
The takeaway here is that Finance Prompts for tax scenarios require you to pre-emptively include every boundary condition the model cannot possibly know. This includes purchase dates, account types, prior transactions, and jurisdiction-specific rules.
Prompt Patterns That Actually Work in Practice
I use four standard prompt structures repeatedly, each adapted for a specific financial task.
For portfolio analysis, I use this pattern: "You are analyzing a portfolio with the following characteristics [insert details]. Identify concentration risk, sector exposure, and any single-position risk exceeding [threshold]. Return findings as a structured list with severity ratings." This usually takes about 30 seconds to generate and gives me a quick risk scan that I can then verify manually.
For tax optimization, the pattern shifts: "Given [transactions, account types, jurisdiction], calculate the after-tax outcome of [action A vs action B]. Include capital gains implications, loss carryforwards, and any rule-specific constraints. Show the calculation steps." The key here is asking for calculation steps. It forces the model to show its work, which makes it far easier to catch errors.
For investment research, I use: "Research [asset/strategy] using data available through [date]. Summarize the bull case, the bear case, and the consensus view. Cite each claim with a source and date. Flag any data older than 12 months." Older data in finance is worse than useless. The model will happily cite a 2021 analysis for a 2024 situation unless you explicitly restrict the timeframe.
For personal financial planning, the pattern is: "I am [age], earning [income], with [debts, assets, dependents]. My goal is [specific goal] by [date]. Outline a prioritized action plan with estimated timelines and potential obstacles." This is where prompts tend to be most vague and most useless. The model will give you a generic plan unless you force specificity into every parameter.
Where This Approach Fails Completely
Finance Prompts do not work for real-time market data. No matter how well you phrase the prompt, the model cannot tell you the current price of a stock unless it has browsing capabilities and you explicitly enable them. Even then, the data may be minutes or hours stale. I lost credibility with my team after someone tried to use a standard prompt to get live cryptocurrency prices and got a response from three months earlier.
They also fail at complex regulatory compliance. If you are asking about ERISA rules, SEC registration requirements, or cross-border tax treaties, the model will construct answers that sound authoritative but may contain subtle inaccuracies. These are the areas where a small wording mistake in the model's output could have serious legal consequences. I now explicitly state in every compliance-related prompt: "If you are uncertain about any regulatory detail, state your uncertainty explicitly rather than guessing." This does not eliminate the risk but it at least makes the model flag its own confidence levels.
The biggest failure mode is over-reliance. People read a well-generated financial analysis and treat it as final. It is not. It is a starting point, a first draft of thinking that you still need to validate against primary sources, your own records, and professional advice where the stakes are high enough to warrant it.
Building a Personal Finance Prompt Library
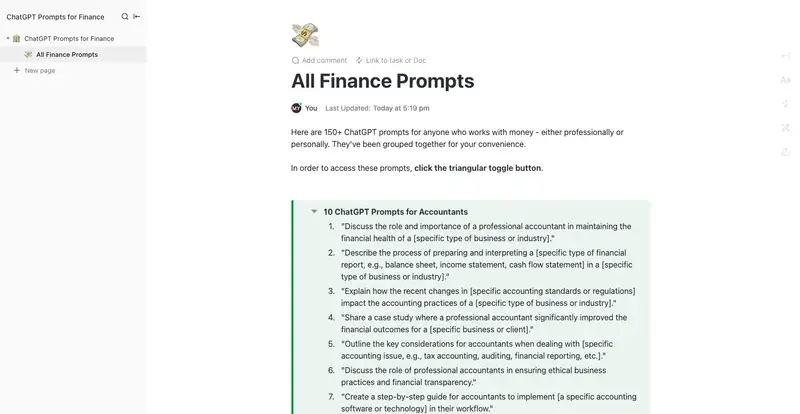
What I ended up doing was creating a folder of Finance Prompts templates organized by use case, with variables marked in brackets for easy substitution. I kept the most effective ones in a single reference document and updated it weekly as I discovered better phrasings or found edge cases that broke existing templates.
The templates I use most often generate in under a minute and give me results that save me between 20 and 40 minutes of manual research per week. That is not a dramatic time saving but it compounds quickly when you are doing this kind of analysis regularly. The real value is in reducing the friction between having a question and getting a usable answer, even if that answer still requires verification.