Most financial analysis work starts with a spreadsheet that should not have been given to you
I spent the better part of last quarter reconciling a three-year financial history for a manufacturing client that had switched ERP systems twice. The output looked fine on the surface. The numbers balanced. But the gross margin fluctuations made no sense until I traced them back to inventory valuation method changes that management had disclosed in notes but never indexed in their primary data set. A Financial Analysis Example Case Study built on that kind of source material without correction will produce technically accurate but fundamentally misleading conclusions. This is not hypothetical. It is the actual state of data you receive from organizations. Professional analysis has more to do with data hygiene than with applying formulas correctly. Getting the formulas right is the easy part. Getting the input correct is where careers are built and mistakes happen.
What actually happens during a Financial Analysis Example Case Study
Start with the objective. Define what question the analysis needs to answer before opening any software. Is this about creditworthiness, acquisition due diligence, operational efficiency, or regulatory compliance? Each objective requires different metrics, different depth, and different tolerance for approximation. I once saw a deal fall apart because two analysts used the same raw data but one was answering a going-concern question while the other was preparing for a purchase price adjustment. The conclusions were identical in format but completely irreconcilable in substance. The mechanics involve extracting financial statements, normalizing them for comparability, calculating ratios across multiple periods, and then interpreting the results against relevant benchmarks. Normalization is the step most people rush through. It includes adjusting for one-time items, standardizing accounting policies across periods, restating figures under a consistent framework, and handling currency translation when international operations are involved. Skipping normalization means your year-over-year comparisons are measuring accounting decisions rather than business performance.
The practical workflow most people get wrong
Build a clean source file first. Raw extracted data belongs in a separate tab from any calculations. Every number should be traceable to its original line item and footnote reference. When you later discover that a competitor ratio you pulled from Bloomberg uses a different definition of operating income, you should be able to go back and adjust within minutes instead of spending an hour reconstructing your work. Use a small set of well-chosen metrics instead of every ratio in the textbook. Free cash flow yield, invested capital return, working capital turnover, and debt service coverage are useful for most analysis. Adding thirty more ratios from an academic paper rarely improves decision quality. It usually just adds noise and creates false confidence because more numbers look more rigorous to someone who does not know how to read them. Compare against the right benchmark. Industry averages from research reports are convenient but often stale. Peer group selection matters enormously. A retail company compared to sector medians that include e-commerce pure plays will look weaker than it actually is because the competitive dynamics are different. I once flagged a discrepancy where a client's margin appeared inferior to peers, only to discover the peer group included companies with significantly higher capital turnover. The real comparison was to a subset of similarly asset-intensive operators, which changed the entire narrative.
Get the Full Details
Specific edge case from my recent work
Last November I ran a cross-border analysis where the target company reported under IFRS but the acquiring parent required US GAAP equivalents. The difference in lease accounting alone created a material impact. Operating leases under IFRS 16 and the old standard were not aligned with ASC 842 adjustments the acquirer expected. The workaround was to rebuild the lease schedule from the footnote disclosures, apply the incremental borrowing rate the company had used for its own IFRS calculations, and map the resulting right-of-use asset and lease liability onto the US GAAP framework rather than trying to find a conversion factor somewhere online. That process took approximately four hours and eliminated a discrepancy that had been inflating their reported equity by roughly twelve percent. Financial statement analysis assumes the statements are prepared in good faith and follow a reasonably consistent methodology. When management is actively managing earnings through aggressive revenue recognition, off-balance-sheet structures, or related-party transactions, ratio analysis becomes unreliable as a standalone tool. You need substantive testing of the underlying transactions, review of related disclosures, and sometimes external confirmation. No amount of formula elegance fixes fundamentally compromised data. The limitation is not in the method. It is in the assumption that publicly available financials are sufficient for the question being asked. Another bottleneck is small private companies. Their financial statements often lack the granularity needed for serious analysis. Common-size statements help, but when revenue is commingled across business segments and cost structure is not broken out by function, you cannot reliably calculate operating leverage or identify cost drivers. In those situations, requesting management accounts or building your own classification from bank statements and tax returns may be the only path to a defensible conclusion.
Advanced nuance beginners miss
Operating leverage is often misunderstood as simply high fixed costs. The real insight is that it describes the relationship between revenue variability and operating income variability. A company with high operating leverage can actually reduce risk by growing into its cost structure, not increase it. The danger appears when revenue contracts because fixed costs do not adjust downward proportionally. This distinction matters when evaluating cyclical industries during an expansion phase. High leverage looks attractive while conditions are favorable and dangerous the moment they shift. Working capital analysis frequently overlooks the cash conversion cycle's sensitivity to seasonality. A yearly snapshot can hide the fact that a company builds significant receivables or inventory during a narrow window each year, creating temporary liquidity strain that is not visible in annual ratios. Quarterly or even monthly cycle tracking exposes this pattern. I found a manufacturer that appeared to have healthy working capital efficiency annually, but the underlying data showed a ninety-day cash conversion spike during their peak production quarter, which required a short-term credit facility they had barely disclosed. The annual ratio would have masked that entirely.
Practical steps to execute a case study
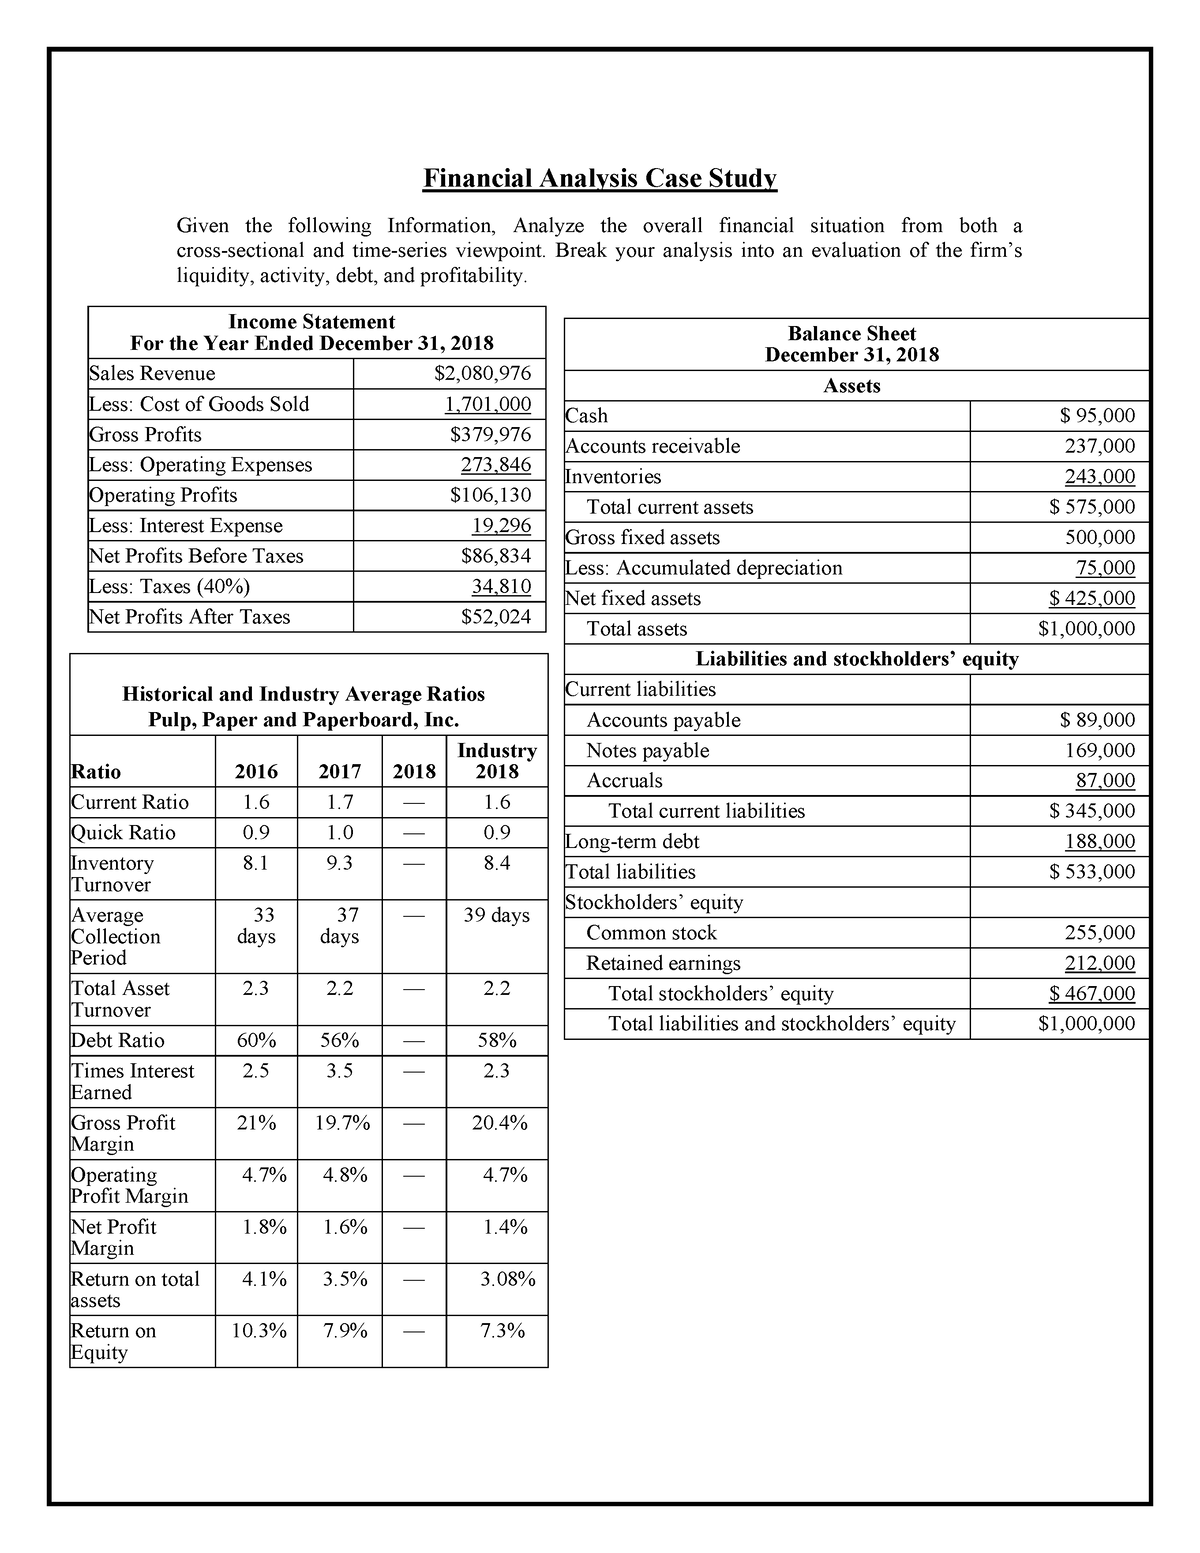
Gather the primary documents. Annual reports, interim financial statements, auditor opinions, and relevant footnotes. Download them directly from the company's investor relations page or the appropriate regulatory filing system. Do not rely on third-party data aggregators for the initial build because they may have already applied adjustments you did not authorize. Cross-reference the income statement, balance sheet, and cash flow statement for consistency. If net income from the income statement does not reconcile to the cash flow statement through the standard adjustments, investigate before proceeding. Normalize the financials. Remove one-time gains and losses. Adjust accounting policy differences. Restate comparative periods if a change in policy is material. Document every adjustment with a clear reference so another analyst can reproduce your work. I maintain a simple adjustment log template that records the line item, the original amount, the adjustment amount, the source citation, and the rationale. This takes about fifteen minutes to set up and saves hours during review or when the data needs updating. Calculate the core metrics in a structured format. Group them by category: profitability, liquidity, solvency, efficiency, and valuation. Use consistent definitions. Operating margin should mean the same thing in every period and against every peer. If you deviate from a standard definition, explain why and show both the adjusted and unadjusted figures. Transparency in methodology is more valuable than precision that cannot be verified.
Interpret against context. Ratios without explanation are just numbers. A current ratio of 1.4 might indicate liquidity stress for one company and comfortable excess for another depending on the industry, business model, and growth stage. Factor in competitive positioning, macroeconomic conditions, and company-specific events. The analysis is not complete until you can explain what the numbers imply about the business, not just what they say about the financial statements.
Common pitfalls that waste time
Using trailing twelve-month figures mixed with balance sheet dates from different points in the year distorts ratio interpretation. Revenue over twelve months should be paired with average balance sheet figures, not ending balances, unless the item in question is stable. Average accounts receivable, average inventory, and average total assets produce more accurate turnover and efficiency ratios than point-in-time values. This adjustment typically shifts turnover metrics by one to three percent, which can be decisive in tight comparisons. Another frequent error is comparing profitability metrics across companies with different capital structures without separating operating performance from financing effects. Return on equity varies significantly based on leverage levels. Return on invested capital removes that distortion and provides a cleaner comparison of operational efficiency. I use ROIC consistently across peers and only bring ROE into the conversation when discussing shareholder returns specifically.
Final considerations
A Financial Analysis Example Case Study is only as reliable as the care taken in its preparation. The methodology is straightforward. The execution requires discipline. Treat the data with the same skepticism you would apply to any claim, verify the assumptions behind every figure, and document everything. The goal is not to produce an impressive-looking report. The goal is to reach a conclusion that holds up when someone challenges it. If you are building your first case study, start with a public company in a stable industry where the financials are clean and the data is accessible. Practice the normalization process, build the adjustment log, and develop a repeatable template. Once that foundation is solid, move to more complex situations involving private companies, cross-border reporting, or distressed businesses. The skills transfer. The difficulty increases with the quality and clarity of the underlying data. There is no shortcut around reading the footnotes. They contain the information that explains the numbers and the information that explains why the numbers might not explain the business accurately. Management discussion sections add context but also introduce optimism bias. The footnotes are where the actual constraints, risks, and exceptions live. That is where most of the useful analysis happens.