What Financial Arrangement Forms Actually Are (And Why Most Dentists Get Them Wrong)
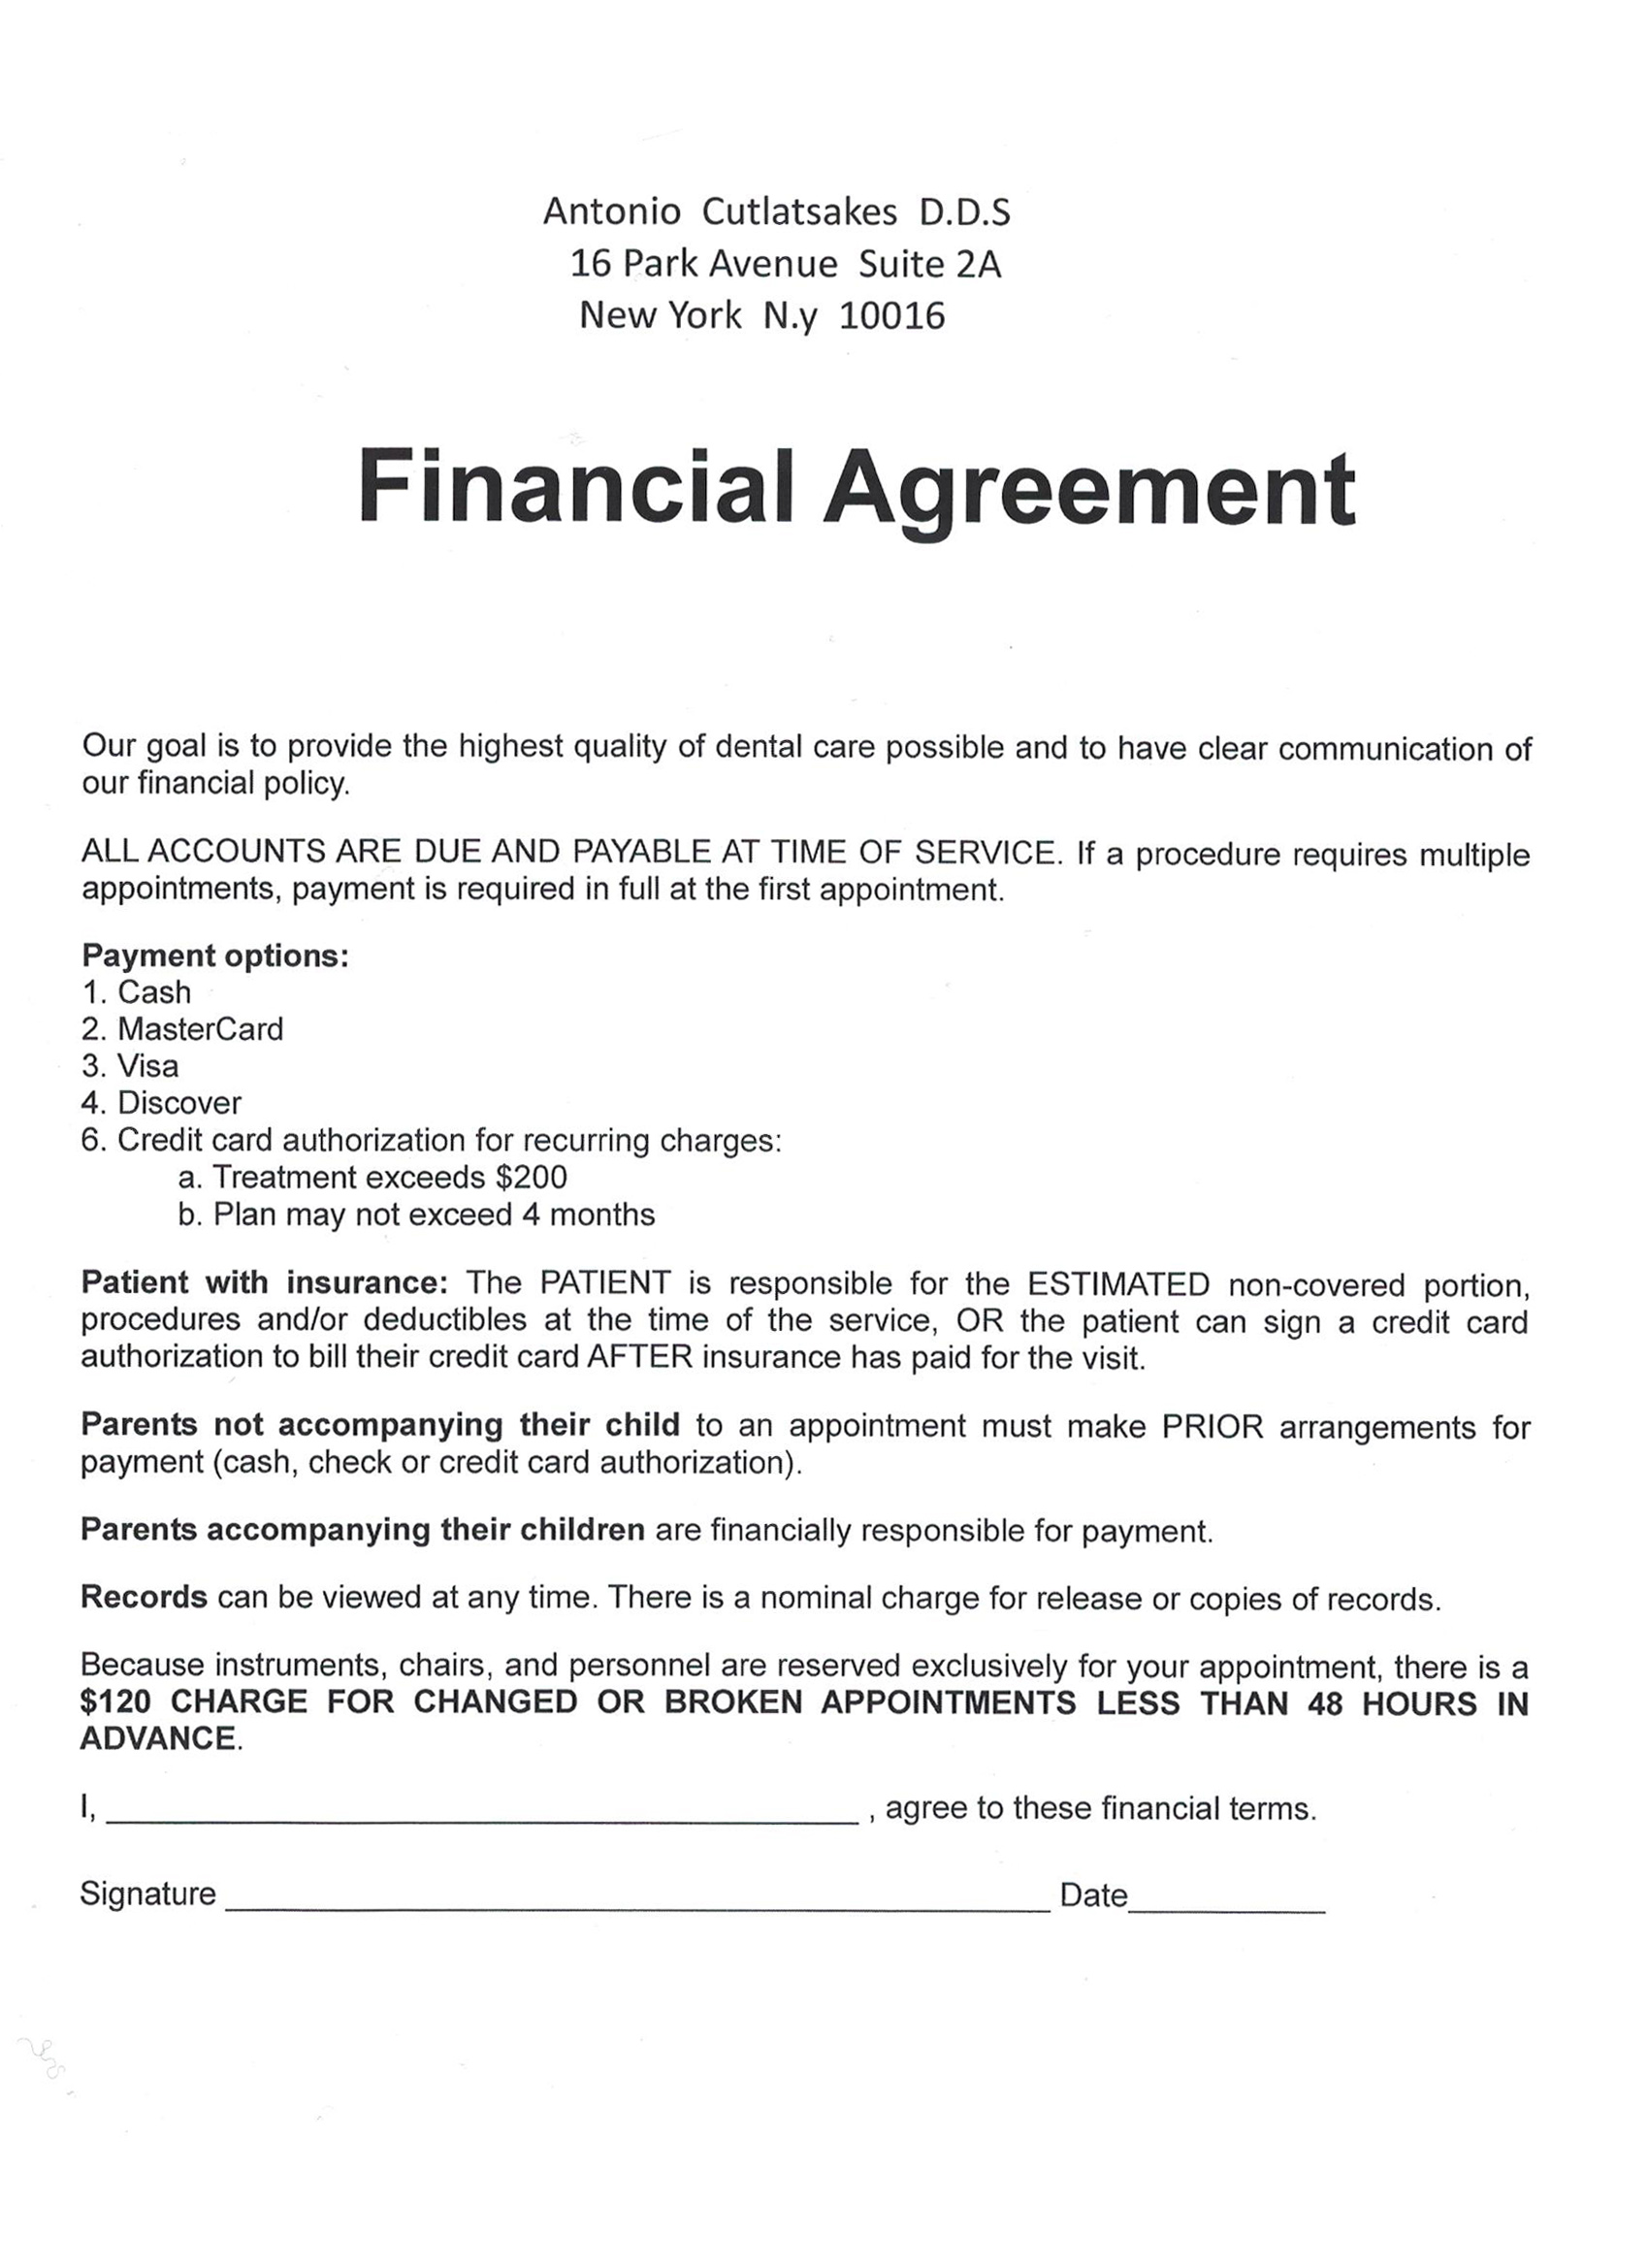
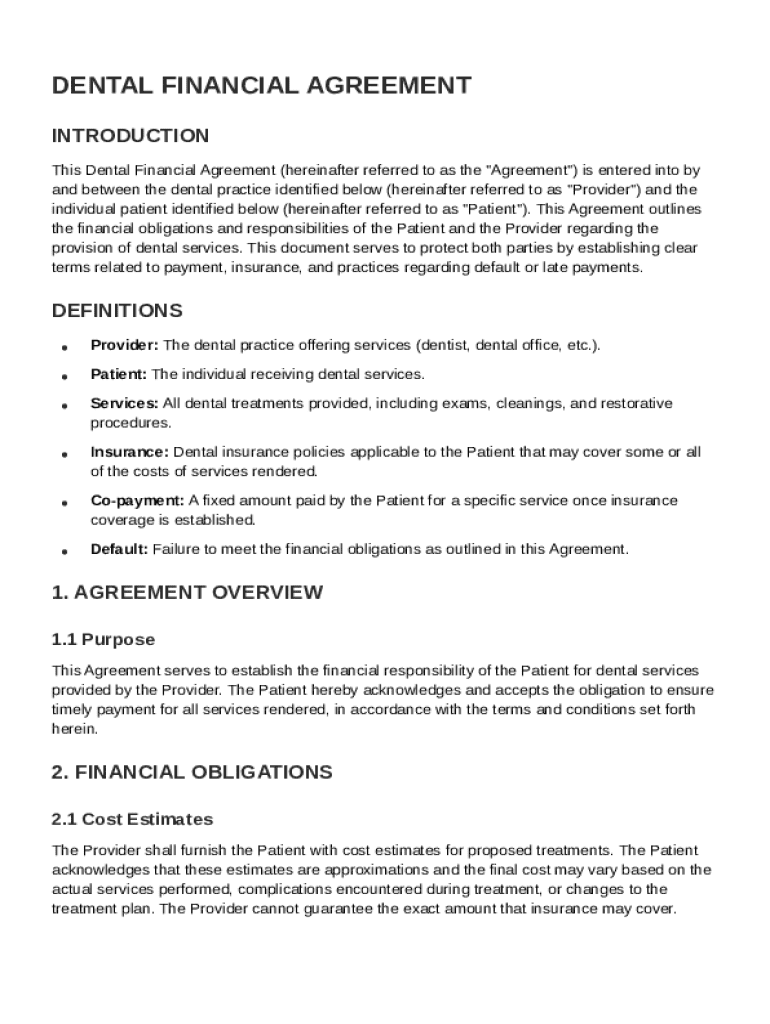
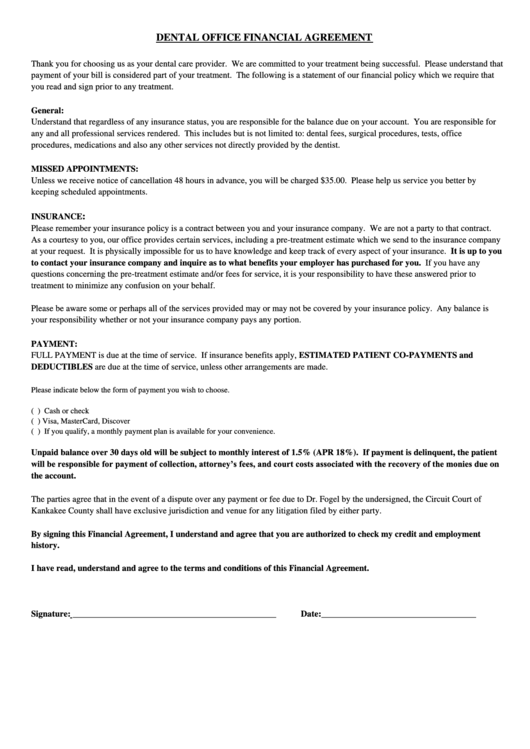
Financial arrangement forms in a dental office are the paperwork that documents a patient's agreement to pay for treatment. They cover payment plans, third-party financing, insurance authorizations, and out-of-pocket responsibility acknowledgments. The standard form includes the patient's full legal name, contact information, social security number (required by most financing companies), a detailed breakdown of the proposed treatment plan cost, and signatures from both the patient and guarantor. Most practice management software has a built-in financial form module, but the generic templates are usually inadequate. They don't account for state-specific consent language, they miss the arbitration clause requirements that matter if you ever need to pursue a collection, and they rarely handle the situation where the treatment plan changes mid-course. I spent years trying to make those default forms work across three states with different regulations before building a custom system that actually holds up under scrutiny.
How to Set Up Financial Arrangement Forms Dental Office Workflows
Start by identifying every scenario where money changes hands between patient and practice. That includes direct patient payments, CareCredit and similar medical credit lines, LendingClub Patient Finance, Sunbit, in-house payment plans, insurance co-pay collections, and self-pay sliding scale agreements. Each one needs its own document with slightly different legal language. A CareCredit application is a hard credit pull that requires specific disclosures. An in-house payment plan is a simple promissory note. Mixing them up creates compliance gaps. The workflow should trigger at the treatment plan presentation stage, not at checkout. Here's how it typically runs: the front desk pulls up the estimated fee schedule, the patient reviews it, and the financial coordinator explains the payment options before any work begins. The patient signs the appropriate form on a tablet or paper. A copy goes into the clinical chart, a digital scan is uploaded to the practice management system, and the original is filed in the financial records. This process usually takes about 8 to 12 minutes per patient when done correctly. I've seen practices skip steps and end up spending three times that chasing signatures after the fact, which is worse for patient relations and terrible for collection outcomes. One thing that catches people off guard: the guarantor signature. If the patient is a minor, deceased, or legally incapacitated, the form is essentially worthless without the actual financial responsible party signing it. I once had a practice try to collect from an estate after the patient passed away, and the form only had the patient's signature with no guarantor noted. The case went nowhere. Now I require the guarantor field to be filled and signed in every single instance, even for adult patients, because it eliminates that vulnerability entirely.
Common Pitfalls and What Actually Works
Payment plan structures are where most offices make mistakes. A lot of dentists offer "pay over six months, no interest" as a patient perk, but they never document the monthly amount, the due date, or what happens if a payment bounces. Without that detail, you can't enforce the plan later. The form needs to specify: the total balance, the number of installments, the dollar amount of each payment, the due date for each one, acceptable payment methods, and late fee policies if your state allows them. Some states cap late fees at very low amounts, so check your local regulations before writing anything into the form. Another issue is the automatic withdrawal authorization. It's a powerful tool, but it requires explicit patient consent with clear written instructions. You cannot just assume a patient agrees to auto-draft because they said they'd pay monthly. The form needs a separate section authorizing electronic funds transfer, with the patient's bank routing number, account number, and a statement that they understand the withdrawals will occur on specified dates. I keep a separate EFT authorization addendum rather than cramming it into the main form because the banking details are sensitive and some patients prefer not to share that information upfront. Here's a practical tip that isn't obvious: attach the signed financial form to the specific procedure codes in your practice management system. When you generate the statement or send it to collections, the system should automatically include a reference to the signed agreement number. This links the debt to the documentation and makes the paper trail airtight. Without that connection, collections agencies and courts need you to manually assemble the evidence, which slows everything down and increases the chance of something getting lost.
Get the Full Details
When Financial Arrangement Forms Break Down
No form handles every situation perfectly. There are edge cases that will trip you up. Patients who change their mind after signing, for example. If a patient signs a payment plan for a $4,000 procedure and then backs out two days later, the contract is still valid, but collecting on it becomes much more complicated and often not worth the effort. Some offices write a clause allowing cancellation within 72 hours of signing, which reduces friction with patients who sign under pressure. It's a judgment call, but I've found that offering a short cancellation window actually improves patient satisfaction scores without meaningfully increasing bad debt. Insurance denials are another failure mode. A patient might sign a financial responsibility form acknowledging they owe a certain amount based on their insurance coverage, and then the insurance company denies the claim entirely or pays far less than expected. The form should include a clause stating that the patient's obligation is independent of insurance reimbursement. That way, a denied claim doesn't erase the debt. I learned this the hard way when a patient's secondary insurance turned out to be invalid, and the office had written the financial form without the non-reliance clause. The patient walked away owing nothing, and the practice absorbed the loss. Third-party financing through companies like CareCredit has its own complications. Those applications are processed externally, and the financing company becomes the creditor, not the dental office. Your form should clearly state this distinction so patients understand they're entering into a separate financial agreement. When patients get confused about who they owe money to, disputes arise, and the financing company often sides with the patient if the documentation is ambiguous. Clear language in the form that says "the dental office is not a party to this financing agreement" prevents that confusion.
Building or Buying Your Financial Forms
You can develop these forms yourself, use templates from your state dental association, or purchase a customized package from a dental practice consulting firm. The DIY route saves money but requires legal review in each state you operate in. Dental association templates are a decent starting point but often lack the specificity that modern practice management software can leverage. Professional packages from firms like Dentistry Works or Dental Design Studio typically cost between $500 and $1,500 and include state-specific addendums, which is worth it if you practice in multiple states or handle a high volume of financed cases. If you're using a practice management system like Dentrix, OpenDental, or Eaglesoft, start by examining what their financial form modules already offer. Fill in the gaps with custom addendums for your specific needs. Don't overwrite the system defaults unless you have a reason to, because those defaults are usually updated when regulations change. Custom forms require you to stay on top of regulatory updates yourself, and that's a significant ongoing burden. The bottom line is that financial arrangement forms are not just paperwork. They're the legal foundation of your practice's revenue cycle. Getting them right prevents collection problems before they happen. Getting them wrong means you're constantly reacting to missed payments, disputed charges, and compliance headaches. Spend the time to build a system that works for your specific practice structure, and maintain it annually with a legal review. The hours you invest upfront save dozens of hours in billing and collection later.