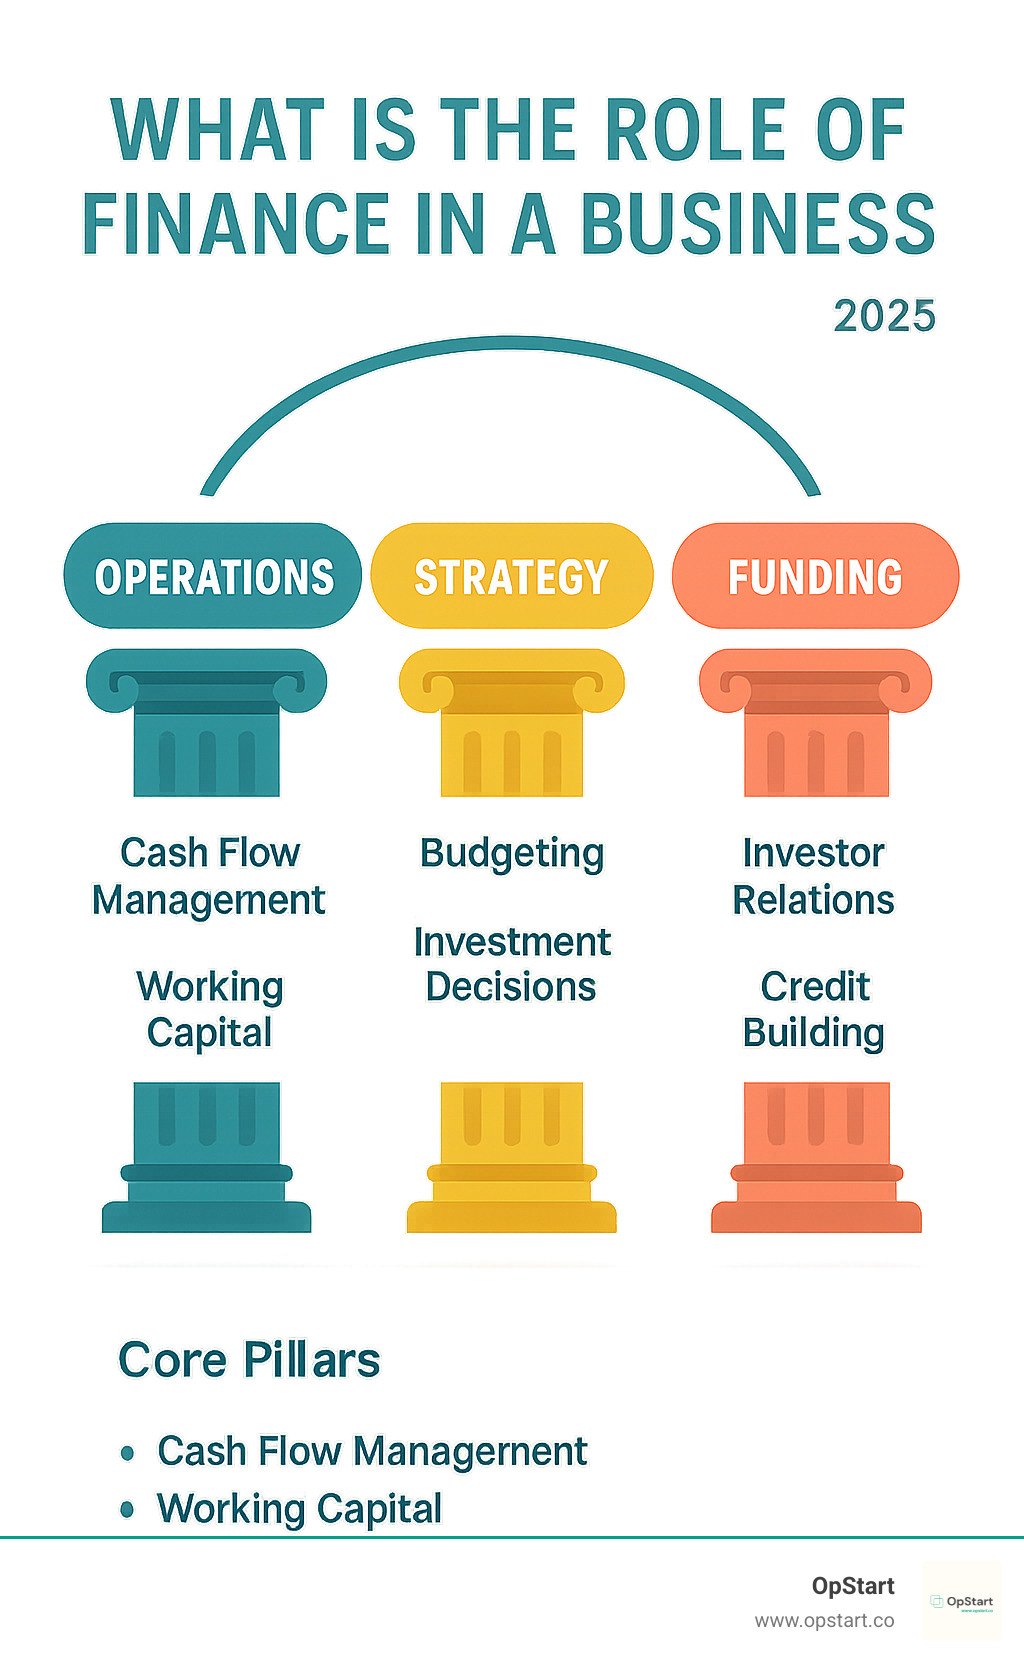
Setting Up A Practical Financial System For Your Small Business
Most small business owners don't have a financial problem because they lack income. They have one because their numbers live in three different spreadsheets, a personal checking account that still receives some client payments, and a receipt folder on their phone they never organize. Fixing that doesn't require an MBA. It requires picking a system and refusing to deviate from it for at least ninety days. You need five things tracked weekly: revenue by source, cost of goods sold, operating expenses, accounts receivable aging, and cash on hand. Everything else is secondary until those four are working. I built my first system around a simple Google Sheet with five tabs and a habit of entering receipts within twenty-four hours of purchase. It was ugly. It worked because it was fast enough that I actually used it. The most common mistake I see is conflating profit with cash. You can be profitable on paper and still miss payroll. That happens when you invoice on net-60 terms and pay your vendors on net-30. The gap between what comes in and what goes out is where businesses die. Track your cash conversion cycle like it's a vital sign, not something you check quarterly.
I ran into this exact problem with a freelance consulting client who had $47,000 in outstanding invoices but couldn't cover a $12,000 contractor payment due that week. She thought she was fine because her P&L looked healthy. The workaround was setting up a separate short-term line of credit specifically for timing mismatches, not for growth spending. When the invoices started coming in over the next three weeks, she paid down the line without panic. That single change prevented what would have been a real crisis.
How To Structure Your Bookkeeping Without Burning Out
Weekly entry beats perfect monthly entry every time. I learned this the hard way when a client came to me with eighteen months of scattered receipts, a partially reconciled QuickBooks file, and a tax extension that was already overdue. It took us six weeks to clean it up. If she had spent forty-five minutes every Friday organizing and entering, that entire project would have been a three-hour check-up instead. Here's the actual workflow I recommend: Every Friday, pull your bank and credit card statements. Match each transaction to an invoice, expense receipt, or category. If a transaction doesn't fit neatly, flag it and move on. Don't chase perfection. At the end of the month, reconcile your accounts and review your Profit & Loss statement against the previous month. Look for anything over twenty percent variance and investigate only those line items. Most months nothing will look wrong, which is exactly what you want.
Get the Full Details

For software, Wave works for businesses under about $200,000 in annual revenue. It's free, handles invoicing and basic expense tracking, and connects to most US bank accounts. Beyond that threshold, QuickBooks Online or Xero becomes worth the $30 to $60 monthly fee because the reporting gets detailed enough to actually support decisions. I've seen too many owners stay on the free tier past the point where the manual work starts eating into their actual business time.
Cash Flow Management That Doesn't Require A CFO
Cash flow forecasting is simpler than people think. Take your current bank balance. Add any confirmed incoming payments over the next thirty days. Subtract any known outgoing obligations. The result is your projected end-of-month balance. If it dips below your minimum operating threshold, you've got about forty-five days to adjust before it becomes a problem. Adjust by accelerating receivables, delaying non-essential payables, or accessing a line of credit before you're desperate. I keep a rolling twelve-week cash flow forecast in a separate tab from my main bookkeeping file. It's not exact, and that's the point. It's a directional tool. When I saw a client's forecast show a negative projection in week eight, we proactively contacted their three largest overdue clients and offered a two-percent discount for immediate payment. Two of them paid within four days. That one habit of looking ahead instead of reacting has probably saved more businesses than any other single practice I've recommended. The limitation here is that forecasts break when revenue is unpredictable. If you're on a project basis with irregular income, your forecast will be wrong more often. In that case, shift to a worst-case scenario model: what if half your expected revenue disappears for sixty days? Can you still cover fixed costs? If the answer is no, build a cash reserve equal to at least one month of operating expenses before you do anything else with profit.
Understanding Your Numbers Without Getting Lost In Them
Gross margin tells you whether your pricing is working. Net margin tells you whether your operations are efficient. Most owners focus on net margin because it feels like the bottom line, but gross margin is the earlier warning system. If your gross margin drops from forty-five percent to thirty-eight percent over three months, something changed before your net margin has time to reflect it. Investigate immediately. It could be a vendor price increase you didn't notice, a product mix shift toward lower-margin items, or a pricing mistake. Accounts receivable aging is another early signal. If your average collection period creeps from thirty-two days to forty-five days, your cash conversion cycle is lengthening even if your revenue looks fine. Send a polite reminder at day thirty, not day forty-five. The difference between collecting at thirty and collecting at forty-five is significant when you're running lean. I once handled a situation where a business had consistent revenue growth but declining cash balances. Their receivables were aging out, and they were so focused on closing new deals that they weren't following up on old invoices. The fix wasn't more sales. It was a thirty-minute weekly receivables review where we identified the oldest outstanding invoices and took direct action on each one. Cash improved within sixty days without a single new customer.

Taxes, Compliance, And The Stuff You Can't Ignore
Schedule quarterly estimated taxes if you're a sole proprietor or partnership. Miss them and the penalties compound faster than most people expect. I calculate mine using the prior year's tax liability divided by four, then adjust each quarter if income has shifted significantly. It's not precise, but it's close enough to avoid surprises. For corporations and LLCs taxed as corporations, the rules change and you should consult a CPA, but the principle remains the same: don't wait until April to think about your tax position. Separate business and personal finances completely from day one. I know it's tempting to pay a vendor from your personal account because it's faster. It's faster now and expensive later. Mixing funds complicates your bookkeeping, weakens your liability protection, and makes audit preparation unnecessarily painful. A simple business checking account and a business credit card cover ninety percent of what you need. Anything above that is an operational choice, not a necessity. One counter-intuitive insight that took me years to accept: recording every expense isn't the same as deducting every expense. The IRS allows ordinary and necessary business deductions, but personal mixed-use items create ambiguity. A phone used for both business and personal calls gets a percentage deduction, not a full one. I've seen business owners lose more money chasing small deductions than they'd save in taxes. Focus on the high-impact items first: payroll, rent, major equipment, and COGS. The small stuff matters less than you think.
When To Bring In Professional Help
A good bookkeeper pays for themselves within the first few months if they free up enough of your time for revenue-generating work. A bad one costs you in corrections and missed patterns. Look for someone who asks about your business model, not just your transactions. The right bookkeeper will notice that your software subscription expense doubled when you added two features, or that your travel costs spiked during a period you thought was slow. That kind of observation is worth far more than data entry. If you're generating under $100,000 annually, you can likely handle bookkeeping yourself with a tool like Wave or even a well-organized spreadsheet. Between $100,000 and $500,000, a part-time bookkeeper becomes a smart investment. Above $500,000, you should have full-time bookkeeping support or a dedicated accounting firm. These are rough guidelines, not rules, but they've held up across the businesses I've worked with over the years. The financial aspects of running a business aren't glamorous. They're repetitive, sometimes frustrating, and entirely necessary. The people who do them well aren't the ones with the best spreadsheets or the most expensive software. They're the ones who showed up every week, paid attention to the patterns, and adjusted before problems became crises. That's it. Nothing dramatic about it.