Recognizing The Patterns Before They Become Permanent
Most people don't realize they are experiencing financial bullying in marriage until things have already escalated to the point where leaving feels impossible. It doesn't usually start with overt hostility. It starts small, with "we don't need to tell your family about our situation," or with the slow accumulation of small decisions made unilaterally over months. By the time someone flags it, the economic entanglement is so deep that separation appears financially suicidal. I've seen this play out in ways that don't match the textbook descriptions. One specific case comes to mind that I thought was unique until I realized how common it actually is. A client of mine came to me because her husband had gradually moved their joint savings into a certificate of deposit under his name only, using language on the paperwork that made it look like an individual account. He didn't lock her out of the checking account. He didn't restrict her spending. He simply removed the visible evidence of shared assets from everywhere she would normally check. When she asked about it six months later, he told her it was "for tax purposes" and that she could access it whenever she wanted. The CD had a 90-day penalty for early withdrawal, effectively locking the funds. It wasn't technically fraud. It was something harder to prove and easier to live with because no single act looked wrong in isolation.
Financial Bullying In Marriage: How It Actually Works
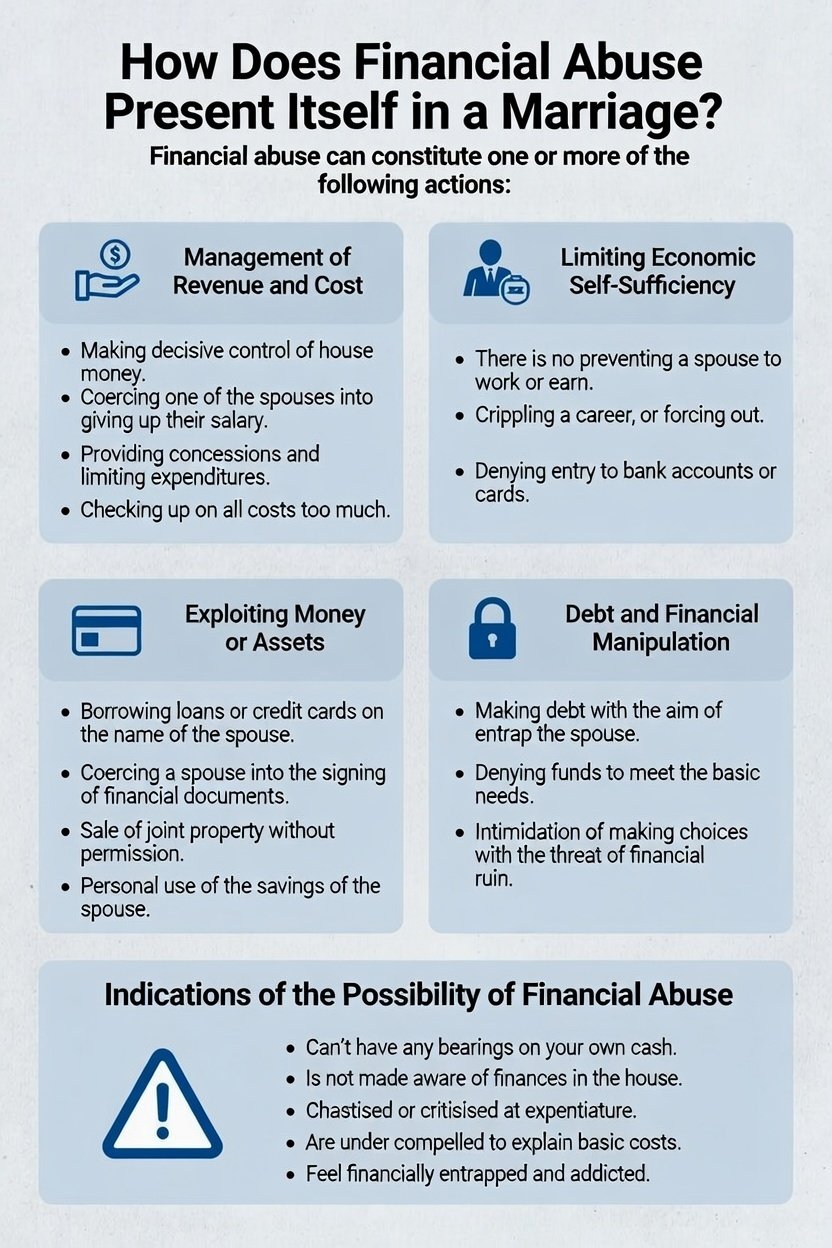
The core mechanism is control through economic dependency, not through direct aggression. The person exercising control doesn't need to be loud or violent. They just need to make the other person economically unable to leave or unable to challenge decisions without risking catastrophic loss. This is why it persists. Victims often tolerate behavior that would be immediately recognized as abusive in any other context because the financial consequences of pushing back are too severe. There are several common structures this takes. One is complete information withholding. One spouse controls all accounts, all statements, all financial knowledge. The other spouse has no idea what their household income actually is, what debts exist, or what assets are available. Another structure is the permission economy. One partner gets an allowance, a spending limit, or has to justify every purchase. The person being controlled learns to self-censor spending before asking, which creates a psychological dependency that extends far beyond the money itself. A third structure is asset dissipation, where one spouse systematically reduces the couple's net worth through reckless decisions, gambling, or unauthorized borrowing, knowing the other partner lacks the resources or knowledge to stop them. The counter-intuitive part that most people miss is that financial abuse often escalates precisely when the victim starts gaining independence. If someone gets a job, starts building their own credit, or reconnects with family, the controlling partner may intensify the financial pressure. This is a warning sign that the behavior is intentional, not incidental. Financial mismanagement and financial control look similar on the surface but have completely different intents and trajectories. Mismanagement gets worse randomly. Control gets worse when the victim gains power.
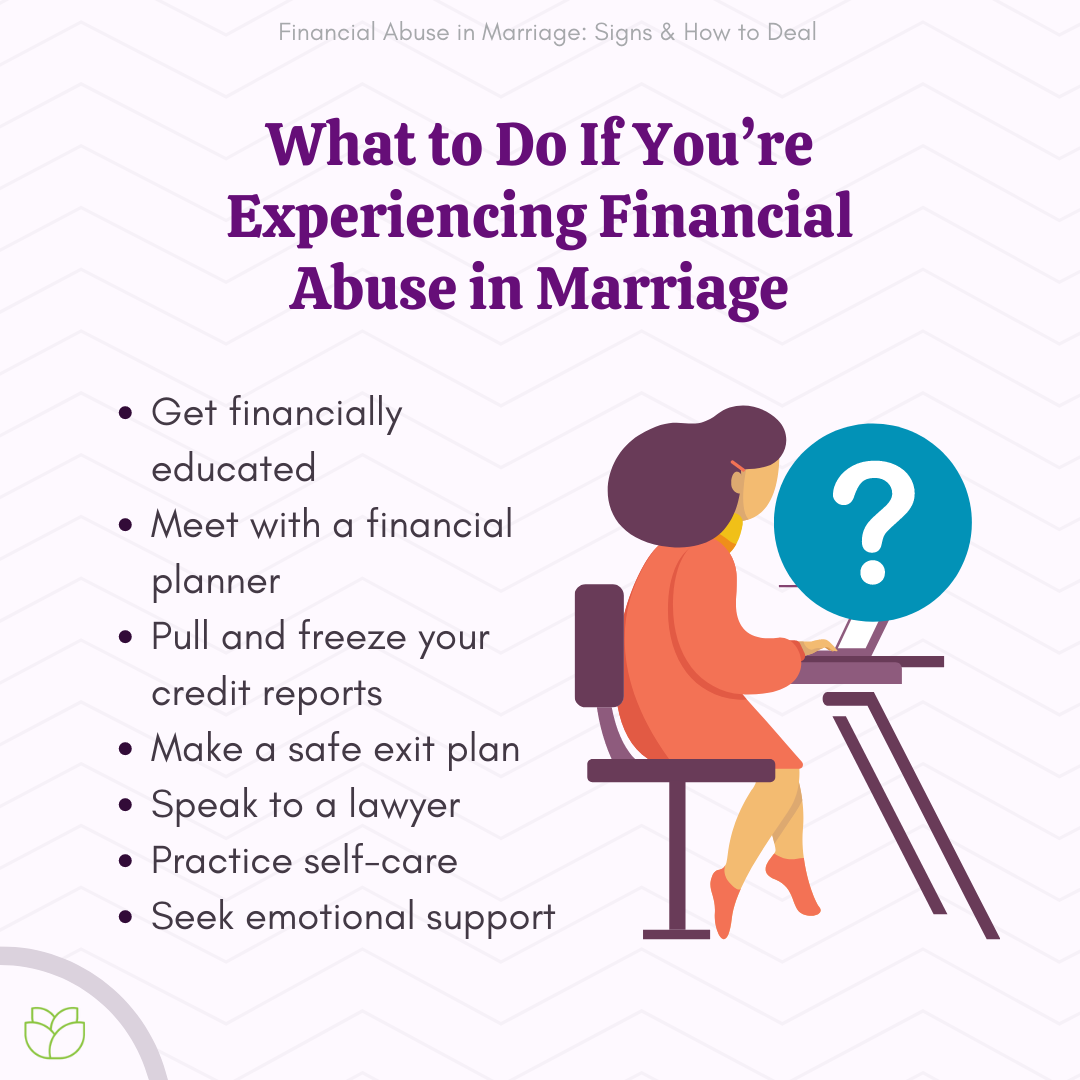
I want to be blunt about what works and what doesn't. Getting a separate bank account is the first recommendation everyone gives, but it rarely works the way people expect. If your income deposits into a joint account and you transfer a portion to a separate account, the controlling partner will likely demand to know why. They may frame it as distrust or secrecy. You end up explaining basic financial autonomy for months before anyone accepts it as normal. The workaround I suggest is setting up direct deposit to your own account from day one of any new employment. Don't convert existing income streams. Just establish the new pattern before it becomes a conversation. Another thing that doesn't work is confrontation about the financial abuse itself. The person doing the abusing typically has a well-rehearsed set of explanations for every behavior. "I'm just better with money," "I'm protecting our future," "You would spend it all." These statements sound reasonable to outsiders and often sound reasonable to the victim too, because they have been repeated enough times. The more effective approach is documentation, not debate. Start keeping records of everything. Account statements, text messages about money decisions, receipts, emails. Not because you think you'll use them immediately, but because three months from now you won't remember the details clearly and having paper trails changes the power dynamic even if you never show anyone. Here is a practical step that gets overlooked. Pull your personal credit report from annualcreditreport.com. It's free and it takes about ten minutes. Check for accounts you didn't open, inquiries you didn't authorize, or changes to your credit utilization that you didn't make. A controlling partner may have run credit checks on you, opened small accounts in your name, or deliberately spiked your utilization to keep your credit score low. Low credit scores make independent living dramatically more expensive. Renting an apartment, getting a phone plan, securing a car loan — all of these cost significantly more with poor credit. This is a deliberate strategy when done intentionally.
Get the Full Details
The legal landscape around financial abuse in marriage varies by jurisdiction and is notoriously difficult to litigate. Most states operate under equitable distribution or community property rules, which means that in a divorce, assets are divided regardless of who earned them or who holds them. This sounds protective but it creates a major problem. The controlling partner knows that dividing assets equally removes their primary leverage. So they move the assets. They liquidate, transfer, hide, or convert them into forms that are harder to trace. Hard cash is the most common method. Small withdrawals over time, placed in safety deposit boxes or with trusted friends. By the time a divorce filing happens, the paper trail may show nothing unusual even though significant assets disappeared. My recommendation for protecting yourself in this scenario is to obtain a forensic accountant if you suspect active asset dissipation. This isn't cheap. Expect to pay between $3,000 and $8,000 depending on complexity. But a forensic accountant can trace transactions that a standard accountant would classify as normal. They look for patterns like repeated cash withdrawals just below reporting thresholds, transfers to accounts that don't appear on regular statements, or payments to individuals who aren't family members. The cost is real, and I should note that many people cannot access these funds without court intervention, which creates a catch-22. If you have any independent income or savings outside the marriage, paying for this upfront avoids that problem entirely. There is also a psychological component that deserves attention. Financial bullying in marriage damages decision-making ability over time. When you can't make small financial decisions without justification or fear, your confidence in larger decisions erodes too. This is sometimes called learned helplessness and it is one of the hardest things to reverse. People who have experienced financial control often second-guess basic financial choices after they leave, even when those choices are objectively sound. Therapy focused specifically on financial trauma can help with this. It's not about building budgeting skills. It's about rebuilding the assumption that you are capable of making financial decisions without punishment.
One more practical consideration. If you are reading this and recognizing patterns in your own life, the most important thing you can do right now is document without being detected. Don't warn your partner that you're gathering information. Don't tell a friend or family member who might accidentally mention it to them. Keep digital records on a device they don't have access to. A personal email account, a cloud storage service they can't see, even photos of documents saved to a phone they don't use. The goal is to have evidence available if you ever need it, without giving the controlling partner an opportunity to destroy it preemptively. The reality is that financial bullying in marriage doesn't always end with legal action or therapy. Sometimes it ends with a quiet, gradual shift in power where one person slowly reclaims autonomy over months or years. Sometimes it ends with a clean break. Sometimes it continues indefinitely because the economic practicalities of separation are simply too severe. None of those outcomes are failures. They are just different realities. What matters is having accurate information about what you're dealing with, rather than waiting for someone else to tell you whether your situation is serious enough to act on.